



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


Income taxes for financial accounting purposes are apportioned to each of the following items except

Free
(Multiple Choice)
4.8/5  (82)
(82) Correct Answer: Verified
C
Differences between pretax financial income and taxable income in an accounting period that will not reverse in a later accounting period are called
Free
(Multiple Choice)
4.9/5 (86)
(86) Correct Answer:Verified
VerifiedB
At the end of the current year, Brothers company claims a $225,000 tax credit on its income tax return. Brothers is uncertain about whether the IRS will accept the credit. After some research it is determined that the IRS may not accept all of the tax credit. Brothers estimates the likelihood using the following probability distribution:
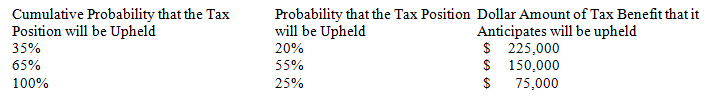 Required:
For the current year determine:
1) the amount Brothers will be able to recognize as a current tax benefit
2) the amount that will be record as the unrecognized tax benefit.
Required:
For the current year determine:
1) the amount Brothers will be able to recognize as a current tax benefit
2) the amount that will be record as the unrecognized tax benefit.
Free
(Essay)
4.8/5 (84)
(84) Correct Answer:Verified
Verified
Combining the net deferred tax asset and liability amounts in the current or noncurrent group is one of the few situations in which GAAP allows offsetting assets and liabilities.
(True/False)
4.7/5 (86)
(86) In 2014, its first year of operations, Richmond Corporation reported pretax financial income of $80,000 for the year ended December 31. Richmond depreciates its fixed assets using an accelerated cost recovery method for tax purposes and straight-line depreciation for financial reporting. On assets acquired in 2014, the following are differences between depreciation on the tax return and accounting income during the asset's five-year life:
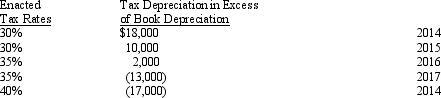 Assuming no other temporary or permanent differences, Richmond's December 31, 2014 balance sheet should include
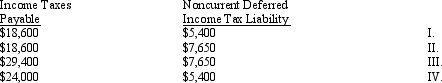
Assuming no other temporary or permanent differences, Richmond's December 31, 2014 balance sheet should include
(Multiple Choice)
4.9/5 (69)
(69) Bourne Company received rent in advance of $9,000 on December 31, 2014, which was taxable when received for income tax purposes. The company's effective tax rate was 30%, and this was the only temporary difference. Which of the following should be reported on the December 31, 2014 balance sheet?
(Multiple Choice)
4.7/5 (75)
(75) Which one of the following requires intraperiod tax allocation?
(Multiple Choice)
4.7/5 (72)
(72) Differences between pretax financial accounting and taxable income that are expected to reverse in one or more future accounting periods are called
(Multiple Choice)
4.8/5 (79)
(79) Deductions that are allowed for income tax purposes but do not qualify as expenses under GAAP are permanent differences.
(True/False)
4.8/5 (87)
(87) It is more likely that a corporation will not need a valuation allowance for a deferred tax asset related to an operating loss carryforward if the operating loss itself provides negative evidence to the likelihood of future taxable income.
(True/False)
4.8/5 (83)
(83) On December 31, 2013, Jefferson Lake, Inc. reported a deferred tax liability of $1,875, based on the following schedule of future taxable amounts and enacted tax rates: 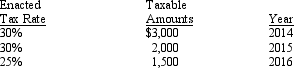 On February 7, 2014, Congress amended a previously passed tax law. The amendment changed the tax rate to 35% for 2014 and all future years.
Required:
Prepare the income tax journal entry for Jefferson Lake, Inc. necessary on February 7, 2014.
On February 7, 2014, Congress amended a previously passed tax law. The amendment changed the tax rate to 35% for 2014 and all future years.
Required:
Prepare the income tax journal entry for Jefferson Lake, Inc. necessary on February 7, 2014. (Essay)
5.0/5 (72)
(72) Which of the following is false concerning deferred tax assets and liabilities?
(Multiple Choice)
4.8/5 (70)
(70) Shane Company uses an accelerated depreciation method for income tax purposes and the straight-line depreciation method for financial reporting purposes. As of December 31, 2014, Shane has a deferred tax liability balance related to depreciation temporary differences of $80,000. In 2015, depreciation for income tax purposes was $360,000, while depreciation for financial reporting purposes was $300,000. If the income tax rate is 30%, no other temporary or permanent differences exist, and taxable income is $400,000, the entry to record income tax expense on December 31, 2015, would include a
(Multiple Choice)
5.0/5 (83)
(83) Pruett Corporation began operations in 2013 and appropriately recorded a deferred tax liability at the end of 2013 and 2014 based on the following depreciation temporary differences between pretax financial income and taxable income: 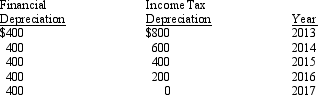 The income tax rate for 2013 and 2014 was 30%. In February 2015, due to budget constraints, Congress enacted an income tax rate of 35%. The journal entry required to adjust the Deferred Tax Liability account in February 2015 would be
(Multiple Choice)
4.7/5 (88)
(88) Exhibit 18-1 On December 31, 2013, Fredericksburg, Inc. had no temporary differences that created deferred income taxes. On January 2, 2014, a new machine was purchased for $30,000. Straight-line depreciation over a four-year life (no residual value) was used for financial accounting. Depreciation expense for tax purposes was $11,000 in 2014, $9,000 in 2015, $6,000 in 2016, and $4,000 in 2013. In each year, the income tax rate was 20% and Fredericksburg had no other items that created differences between pretax financial income and taxable income. Fredericksburg reported the following pretax financial income for 2014 through 2017: 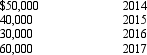 - Refer to Exhibit 18-1. The entry to record income taxes on December 31, 2016, would include a
 (Multiple Choice)
5.0/5 (79)
(79) Permanent differences between pretax financial income and taxable income result when
(Multiple Choice)
4.7/5 (79)
(79) At the end of its first year of operations on December 31, 2014, the GAC Company reported taxable income of $30,000 and a pretax financial loss of $40,000. Differences between taxable income and pretax financial income included estimated bad debt expense for which accounts were expected to be written off in 2015, $20,000, and warranty costs expensed for accounting purposes in excess of cash paid for warranty claims, $50,000. The warranty costs are expected to be paid in 2015. The enacted tax rate for 2014 and 2015 is 30%.
Required:
a.Prepare the income tax journal entry for the GAC Company on December 31, 2014, assuming that it is more likely than not that the deferred tax asset will be realized.
b.Prepare the income tax journal entry for the GAC Company on December 31, 2014, assuming that it is more likely than not that 40% of the deferred tax asset from the warranty costs will not be realized.
(Essay)
4.9/5 (86)
(86) In applying intraperiod income tax allocation to discontinued operations, extraordinary items, retrospective adjustments, and prior period adjustments, what tax rate should be used?
(Multiple Choice)
5.0/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)