



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


The Flintstone Company incurred the following expenses in 2014, which are reported differently for financial reporting purposes and taxable income: 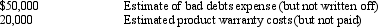 If the tax rate is 40%, the total temporary difference is
 (Multiple Choice)
4.9/5  (85)
(85) What should a corporation disclose for the provisions for income taxes and the effective tax rates?
(Essay)
4.8/5 (69)
(69) Temporary differences arise when revenues or gains are included in pretax financial income 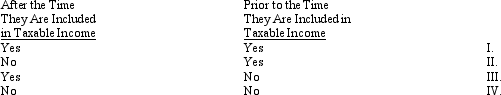
(Multiple Choice)
4.9/5 (87)
(87) At the beginning of 2014, Jasper Company had a deferred tax asset of $7,000 related to the warranty liability on its balance sheet. At the end of 2014, the company estimates that its ending warranty liability is $40,000. Taxable income is $60,000, and the tax rate is 40%.
Required:
a.Prepare the journal entry to record income taxes for the year.
b.Assume the company decides at the end of the year that it is "more likely than not" that $11,000 of the deductible temporary difference will not be realized. Prepare the appropriate journal entry.
c.Show how the deferred tax asset would be reported on the balance sheet for 2014.
(Essay)
4.9/5 (76)
(76) What two objectives did FASB identify for accounting for income taxes?
(Essay)
4.9/5 (83)
(83) Fairfax Company had a balance in Deferred Tax Liability of $840 on December 31, 2014, resulting from depreciation timing differences. Differences in tax and accounting depreciation for assets purchased on January 1, 2014, are as follows:
 In addition to the 2014 depreciation timing difference, Fairfax Company expensed $2,000 of warranty costs that will be deducted for tax purposes when paid in future years. Fairfax's taxable income in 2014 was $35,000. The 2014 income tax rate was 35%, and no changes in the tax rate for future years have been enacted.
Required:
Prepare the income tax journal entry for the Fairfax Company for December 31, 2014.
In addition to the 2014 depreciation timing difference, Fairfax Company expensed $2,000 of warranty costs that will be deducted for tax purposes when paid in future years. Fairfax's taxable income in 2014 was $35,000. The 2014 income tax rate was 35%, and no changes in the tax rate for future years have been enacted.
Required:
Prepare the income tax journal entry for the Fairfax Company for December 31, 2014. (Essay)
4.8/5 (80)
(80) GAAP requires intraperiod income tax allocation to income or loss as they relate to discontinued operations and extraordinary items but not to retrospective adjustments or prior period adjustments.
(True/False)
4.9/5 (93)
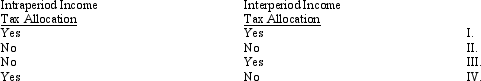
(93) Assuming there are no prior period adjustments during the fiscal year, net income would be affected by
(Multiple Choice)
4.8/5 (85)
(85) All of the following involve a temporary difference for purposes of income tax allocation except
(Multiple Choice)
4.8/5 (81)
(81) Exhibit 18-1 On December 31, 2013, Fredericksburg, Inc. had no temporary differences that created deferred income taxes. On January 2, 2014, a new machine was purchased for $30,000. Straight-line depreciation over a four-year life (no residual value) was used for financial accounting. Depreciation expense for tax purposes was $11,000 in 2014, $9,000 in 2015, $6,000 in 2016, and $4,000 in 2013. In each year, the income tax rate was 20% and Fredericksburg had no other items that created differences between pretax financial income and taxable income. Fredericksburg reported the following pretax financial income for 2014 through 2017: 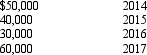 -Refer to Exhibit 18-1. The entry to record income taxes on December 31, 2015, would include a
 (Multiple Choice)
4.9/5 (87)
(87) The intraperiod tax allocation is used to provide a faithful representation of the matching of income tax expense against the components of its pretax income which shows the after-tax impact of each of these items.
(True/False)
4.9/5 (88)
(88) Permanent differences arise due to timing differences between the corporation's pretax financial income and taxable income, which results in deferred tax assets and liabilities.
(True/False)
4.9/5 (75)
(75) In accounting for income taxes, percentage depletion in excess of cost depletion is an example of
(Multiple Choice)
4.8/5 (77)
(77) Income tax expense as determined by GAAP differs from amount determined under the Internal Revenue Code; the differences arise due to measurement and timing.
(True/False)
4.8/5 (83)
(83) The following information relates to the Kill Devil Hills Company for the year ending December 31, 2014:  * Of this amount $5,500 relates to extraordinary items; $4,800 relates to the pretax income from the operations of discontinued division; pretax loss on the disposal of division resulted in a tax savings of $13,350; and pretax correction of the depreciation error resulted in a tax savings of $1,500.
Required:
1) Prepare the year end journal entry necessary to record the 2014 intraperiod income tax allocation.
2) Prepare Kill Devil Hill's 2014 income statement and statement of retained earnings.
* Of this amount $5,500 relates to extraordinary items; $4,800 relates to the pretax income from the operations of discontinued division; pretax loss on the disposal of division resulted in a tax savings of $13,350; and pretax correction of the depreciation error resulted in a tax savings of $1,500.
Required:
1) Prepare the year end journal entry necessary to record the 2014 intraperiod income tax allocation.
2) Prepare Kill Devil Hill's 2014 income statement and statement of retained earnings. (Essay)
4.9/5 (82)
(82) For the year ended December 31, 2014, the Bowling Green Company reported income of $350,000 before provision for income tax. In arriving at taxable income for income tax purposes, the following differences were identified: 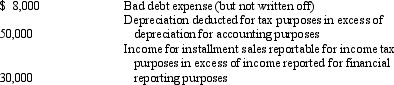 Assuming a corporate income tax rate of 30%, Huntsville's current income tax liability as of December 31, 2014, is
 (Multiple Choice)
4.8/5 (88)
(88) Under IFRS valuation allowances for deferred tax assets are not recorded.
(True/False)
4.9/5 (70)
(70) Moore Company reported the following operating results during its first three years of operations:
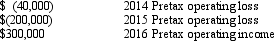 No permanent or temporary differences occurred during these fiscal periods. Assuming an income tax rate of 35%, Moore should report a current income tax liability as of December 31, 2016, in the amount of
 (Multiple Choice)
4.8/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)