



 Chat with AI
Exam 20: Accounting for Leases

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


When a lessee makes periodic cash payments for a capital lease, which of the following accounts is decreased?

Free
(Multiple Choice)
4.7/5  (93)
(93) Correct Answer: Verified
C
(This problem requires use of PV tables with an 11% rate, a financial calculator or the formulas.)
Taquito Company leased equipment to Baja Company on January 1, 2014. The lease was for five years and required annual payments of $24,500 on January 1 of each year with the first payment due January 1, 2014. The equipment had a cost to Taquito of $85,000 and no expected residual value at the end of the lease term. The lease was appropriately accounted for as a sales-type lease by Taquito. Taquito used a 11% rate of return to establish the lease payments.
Required: Required:
a.Prepare all 2014 journal entries for Taquito related to the lease.
b.What amount of interest revenue would Taquito recognize for the year ended December 31, 2015?
Free
(Essay)
4.9/5 (70)
(70) Correct Answer:Verified
Verified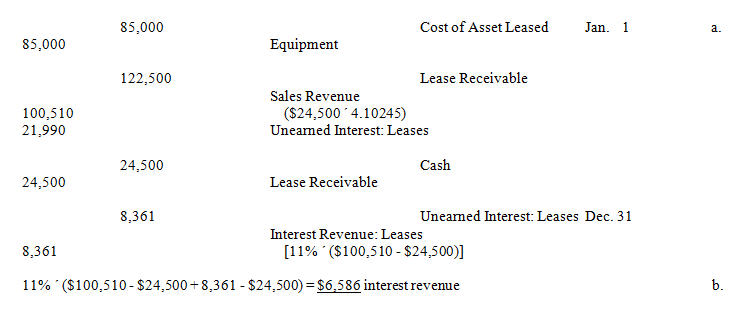
According to current GAAP, leased property recorded as a capital lease normally should be reported as a long-term or intangible asset on the balance sheet of the lessee and the lessor as follows: 
Free
(Multiple Choice)
5.0/5 (85)
(85) Correct Answer:Verified
VerifiedB
Merchant Company found themselves in need of cash. In an effort to shore up their financial situation they sold land to Natalie Company for $3.5 million and immediately leased it back.
1) The land was recorded on Merchant's book at $1.5 million
2) The term of the noncancelable lease is 20 years.
3) The lease agreement requires equal rental payments of $439,518 at the end of each year.
4) The incremental borrowing rate of Merchant's is 12% but the annual rental rate of 11% was set by Natalie, and Merchant is aware of the rate.
5) Merchant pays all executory costs which amount to $11,500 per year which includes taxes and insurance.
6) There are no important uncertainties surrounding the amount of unreimbursable costs yet to be incurred by the lessor, and the collectibility is reasonably assured.
7) The land's fair value is $3.5 million.
8) Natalie provided Merchant with the option to purchase the land at the end of the 20 years for $1,000.
Required:
1) Prepare the seller-lessee journal entries for Merchant, for the 2014 sale and leaseback agreement. (Ignore the bargain purchase option because it is immaterial)
2) Prepare any journal entry that Merchant should make related to the gain at the end of 2014.
(Essay)
4.8/5 (82)
(82) The lessee's disclosures should include the future minimum rental payments as of the date of the latest balance sheet presented, in the aggregate and for a certain number of succeeding fiscal years. This number of years is
(Multiple Choice)
4.9/5 (85)
(85) Depreciation expense will be recorded in the accounts of the
(Multiple Choice)
4.9/5 (74)
(74) Which of the following facts would require a lessor to classify a lease as an operating lease?
(Multiple Choice)
4.9/5 (76)
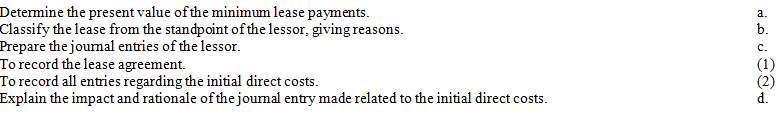
(76) Beatrice, Inc. purchased equipment at a cost of $97,220 on January 1, 2014. Beatrice immediately leased the equipment to Corvalis Company for a seven-year period with rental payments of $17,223 to be paid at the beginning of each year. The lessor's implicit interest rate in connection with the lease is 9%. The equipment is expected to have a guaranteed residual value of $5,000 at the end of the lease term, and an estimated useful life of 11 years. Beatrice paid $6,000 initial direct costs for the lease. The lessor knows all costs, and collection of lease payments is expected.  Required:
Required: (Essay)
4.8/5 (80)
(80) From the lessee's viewpoint, all of the following are advantages of leasing except that
(Multiple Choice)
4.7/5 (80)
(80) A required disclosure of a direct financing lease is that the cost and carrying amount, if different, of property on lease or held for leasing by major classes of property and the amount of the total accumulated depreciation must be disclosed in the company's financial statements.
(True/False)
4.8/5 (76)
(76) A lease must be treated as a direct financing lease by the lessor when
(Multiple Choice)
4.9/5 (68)
(68) On January 1, 2014, Renee Corp., a lessee, signed a five-year capital lease for new equipment. The lease requires annual payments of $8,000. The first payment is due on December 31, 2014. Renee guaranteed a residual value of $2,000. On December 31, 2018, Renee returned the asset to the lessor, and the asset was appraised at a value of $1,500. Renee should record which of the following on December 31, 2018?
(Multiple Choice)
4.8/5 (65)
(65) Which of the following statements is true about initial direct costs?
(Multiple Choice)
4.8/5 (78)
(78) Exhibit 20-3 On January 1, 2014, Quinn Company enters into a five-year sales-type lease with Andy Company. The lease requires Andy to make five annual payments at the beginning of the year, with the first payment due January 1, 2014. The lease includes a bargain purchase price of $10,000. Quinn requires a 10% rate of return. The cost to Quinn of the property is $100,000, and it has a fair value of $150,000. Present value factors for a 10% interest rate are as follows:  -Refer to Exhibit 20-3. The sales revenue to be recognized by Quinn on January 1, 2014, is
 (Multiple Choice)
4.9/5 (91)
(91) (This problem requires use of present value tables.)
Paolo, Inc. (the lessor) entered into a sales-type lease with another company on January 1, 2014. The lease was for five years with $40,000 due at the end of each year. The cost of the equipment on Paolo's books was $140,000. Paolo uses an interest rate of 8%.
Required:
(Round all answers to the nearest dollar.) (Round all answers to the nearest dollar.)
a.Prepare all journal entries for Paolo for the year 2014.
b.If Paolo has mistakenly accounted for this lease as an operating lease, by how much would the company's 2014 income be overstated or understated because of this error? (Be sure to indicate under or over.)
(Essay)
4.8/5 (80)
(80) Which of the following statements regarding the calculation of the lessee's depreciation expense for a capital lease is true?
(Multiple Choice)
4.8/5 (82)
(82) If at any time the lessee and lessor change a lease so that the lease would have been classified differently, the revised agreement is considered a change in the agreement and business proceeds as if the change never occurred.
(True/False)
4.9/5 (83)
(83) What are the four capitalization criteria in which to determine whether to record a lease as operating or capital lease?
(Essay)
4.9/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)