



 Chat with AI
Exam 18: Accounting for Income Taxes

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


A corporation must recognize a valuation allowance, if based on available evidence; it is more likely than not that the deferred liability will not be realized.
(True/False)
4.9/5  (88)
(88) A corporation must report its deferred tax liabilities and assets in two classifications, which are gross current amount and gross noncurrent amounts.
(True/False)
4.8/5 (87)
(87) In 2014, Waterford Corporation reported pretax financial income of $400,000. Included in that pretax financial income was $150,000 of nontaxable life insurance proceeds received as a result of the death of an officer; $120,000 of warranty expenses accrued but unpaid as of December 31, 2014; and $10,000 of bad debts estimated to be uncollectible (but not written off as of December 31, 2014). Assuming that no income taxes were previously paid during the year and an income tax rate of 30%, the amount of income taxes payable on December 31, 2014, would be
(Multiple Choice)
4.8/5 (84)
(84) Interest received on municipal bonds is taxable; this is because the bonds pay a lower rate of interest than corporate bonds. The fact that they are taxable reduces the cost of borrowing for the municipalities.
(True/False)
4.8/5 (80)
(80) Each of the following can result in a temporary difference between pretax financial income and taxable income except
(Multiple Choice)
4.7/5 (74)
(74) Smyrna Company had financial and taxable incomes as follows:
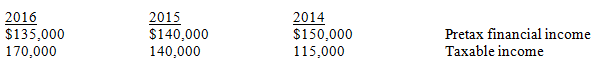 The tax rate for all three years was 30%.
Required:
a.Prepare the journal entries to record income taxes for all three years.
b.Explain why the taxes paid in 2016 are different from the tax return and the amount reported in the financial statements and provide an example of what could cause this difference.
The tax rate for all three years was 30%.
Required:
a.Prepare the journal entries to record income taxes for all three years.
b.Explain why the taxes paid in 2016 are different from the tax return and the amount reported in the financial statements and provide an example of what could cause this difference. (Essay)
4.9/5 (71)
(71) A company would determine whether to recognize an uncertain tax position by evaluating whether the tax position is "more likely than not" which is a less than 50% probability of being upheld during a tax audit by the IRS, based on the technical merits of the position.
(True/False)
4.9/5 (82)
(82) What two issues does FASB have to consider in regards to operating loss carrybacks?
(Essay)
4.9/5 (62)
(62) When congress makes a tax law or rate change, a corporation recognizes financial statement impact by adjusting the deferred assets or liabilities as of the beginning of the year in which the change is made.
(True/False)
4.8/5 (75)
(75) The amount owed the IRS is recorded in the accounting records in which account?
(Multiple Choice)
4.8/5 (91)
(91) During its first year of operations ending on December 31, 2014, the Dakota Company reported pretax accounting income of $600,000. The only difference between taxable income and accounting income was $80,000 of accrued warranty costs. These warranty costs are expected to be paid as follows:
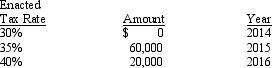 Assuming an income tax rate of 30% in 2014, Dakota should report income tax expense on its 2014 income statement in the amount of
 (Multiple Choice)
4.9/5 (87)
(87) Which one of the following statements regarding operating losses is false?
(Multiple Choice)
4.9/5 (86)
(86) Which of the following would not result in a permanent difference between pretax financial income and taxable income?
(Multiple Choice)
4.7/5 (78)
(78) The Pink Diamonds Company installs fire alarm systems for large manufacturing enterprises and golf courses. Due to the design of their systems, some projects frequently extend over a two-year period. Pink Diamonds uses the percentage-of-completion method for financial accounting purposes and the completed-contract method for tax purposes. As of December 31, 2014, all projects were completed. The following information relates to projects started but not completed as of December 31, 2015:
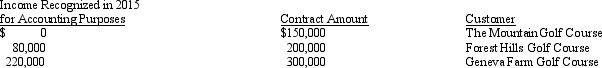 Assuming an income tax rate of 30%, what amount should be included in the deferred tax liability account at December 31, 2015?
 (Multiple Choice)
4.9/5 (83)
(83) What are the three types of permanent differences between a corporation's pretax financial income and taxable income?
(Essay)
4.8/5 (67)
(67) The Mishka Corporation reported the following income for both accounting and tax purposes:
 Mishka Corporation uses the carryback provision for net operating losses when possible. The enacted tax rate for 2018 and future years is 32%. Mishka believes that sufficient verifiable positive evidence exists so that a valuation allowance is not necessary at the end of 2017.
Required:
Prepare the entries for income tax expense and related assets and liabilities for the Mishka Corporation for the years 2014 through 2017.
Mishka Corporation uses the carryback provision for net operating losses when possible. The enacted tax rate for 2018 and future years is 32%. Mishka believes that sufficient verifiable positive evidence exists so that a valuation allowance is not necessary at the end of 2017.
Required:
Prepare the entries for income tax expense and related assets and liabilities for the Mishka Corporation for the years 2014 through 2017. (Essay)
4.8/5 (59)
(59) When Congress changes the tax laws or rates, a corporation's deferred tax liability and asset accounts
(Multiple Choice)
4.9/5 (92)
(92) A corporation's deferred tax expense or benefit is the change in its deferred tax liabilities or assets during the year.
(True/False)
4.9/5 (82)
(82) At December 31, 2014, the Blue Agave Company had a current deferred tax asset of $60,000, arising from cash for magazine subscriptions received and taxed in 2014 but that will be recognized as income for accounting purposes in 2015; a noncurrent deferred tax liability of $160,000 arising from an excess of MACRS tax depreciation over straight-line accounting depreciation of plant assets; and a long-term deferred tax asset of $80,000, arising from contingency expenses for accounting purposes that will be tax deductible when paid (estimated to be in 2016). The 2015 pretax financial income and taxable income for Blue Agave are as follows:
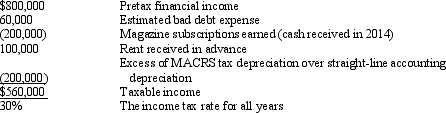 Required:
Prepare the income tax journal entry for the Blue Agave Company at the end of 2015.
Required:
Prepare the income tax journal entry for the Blue Agave Company at the end of 2015. (Essay)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)