



 Chat with AI
Exam 22: Accounting for Changes and Errors

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


The Opal Company was incorporated and began operations on January 1, 2014. Opal used the weighted-average method for costing inventories. Effective January 1, 2015, Opal changed to FIFO for costing inventories and can justify the change. Information related to 2014 and 2015 inventory cost and net income is presented below: 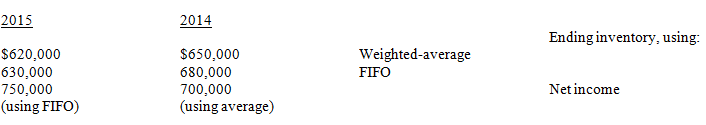 Opal's income tax rate is 30% for both 2014 and 2015.
Required:
Calculate the amount of the cumulative effect of the change on beginning retained earnings on January 1, 2015, that would appear on Opal's statement of retained earnings for the year ended December 31, 2015.
Opal's income tax rate is 30% for both 2014 and 2015.
Required:
Calculate the amount of the cumulative effect of the change on beginning retained earnings on January 1, 2015, that would appear on Opal's statement of retained earnings for the year ended December 31, 2015. (Essay)
4.9/5  (90)
(90) Several items related to accounting changes appear below.  Required:
Indicate the appropriate method of accounting for each case by placing an "X" in the appropriate column. Part (a) has been completed as an example.
Required:
Indicate the appropriate method of accounting for each case by placing an "X" in the appropriate column. Part (a) has been completed as an example. (Essay)
4.7/5 (81)
(81) The Max Company began its operations on January 1, 2014, and used an accelerated method of depreciation for its machinery and equipment. On January 1, 2016, Max adopted the straight-line method of depreciation. The following information is available regarding depreciation expense for each method:
 What is the before-tax cumulative effect on prior years' income that would be reported as of January 1, 2016, due to changing to a different depreciation method?
 (Multiple Choice)
4.8/5 (79)
(79) Langley Company received merchandise on December 31, 2014. Langley failed to record the purchase on account because the invoice was inadvertently destroyed. The merchandise was, however, included in ending inventory. The effect of this event on the financial statements as of December 31, 2014, would be
(Multiple Choice)
4.9/5 (93)
(93) Exhibit 22-5
Daniel Company, having a fiscal year ending on December 31, discovered the following errors in 2014:
A collection of $12,000 from a customer for rent related to January, 2015, was recorded as revenue in 2014.
Depreciation was understated by $600 in 2014.
The January 1, 2013, inventory was overstated by $10,000.
The January 1, 2014, inventory was understated by $6,000.
Exhibit 22-5
Daniel Company, having a fiscal year ending on December 31, discovered the following errors in 2014:
Insurance premiums of $2,000 that relate to 2015 were expensed in 2014 when paid.
Assume no other errors have occurred and ignore income taxes.
-Refer to Exhibit 22-5. Total assets at December 31, 2014, were
(Multiple Choice)
5.0/5 (77)
(77) A counterbalancing error will automatically correct itself in the next accounting period even if it is never discovered.
(True/False)
5.0/5 (82)
(82) The following are independent events:  For each change or error indicate how it would be accounted for using the following:

For each change or error indicate how it would be accounted for using the following: (Essay)
4.9/5 (75)
(75) The 2014 and 2015 financial statements for Angelica Company had the following errors:
•Ending inventory was overstated by $8,000 on December 31, 2014, and overstated by $5,000 on December 31, 2015.
•A five-year insurance policy costing $20,000 was charged to expense when paid in advance on January 1, 2014.
•Depreciation expense of $12,000 on new equipment was omitted from the 2014 financial statements.
•Major improvements to Angelica's manufacturing plant costing $25,000 were charged to expense in 2014 and should have been capitalized. Consequently, annual depreciation expense of $2,500 was omitted from the 2014 and 2015 financial statements.
•Wages of $7,000 earned in 2014 but not paid until 2015 were recorded as an expense in 2015 instead of 2014.
Angelica Company had reported net income of $90,000 in 2014 and $95,000 in 2015.
Required:
Prepare a schedule to determine the correct net income for 2014 and 2015. Begin the schedule with reported net income for 2014 and 2015 and work to a corrected figure. Ignore income taxes.
(Essay)
4.9/5 (92)
(92) When changing from LIFO to FIFO, the least likely result would be
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)