



 Chat with AI
Exam 22: Accounting for Changes and Errors

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


An unstatement of reported net income for the current year may result from
(Multiple Choice)
4.8/5  (82)
(82) The Catherine Company, effective January 1, 2016, made the following accounting change: Catherine changed its depreciation method from double-declining-balance to the straight-line method on equipment purchased on January 1, 2014, at a cost of $400,000. The equipment had an estimated useful life of five years and a $30,000 residual value.
Catherine is subject to an income tax rate of 30% and can justify the changes.
Required:
Calculate the following amounts:
a.2016 depreciation expense
b.the December 31, 2016, accumulated depreciation balance on the equipment
(Essay)
4.8/5 (81)
(81) Lilly Company has been depreciating equipment for 10 years with an estimated total useful life of 25 years. Lilly has revised the estimated life to be only 17 years, with 7 years remaining in the asset's useful life. Lilly should
(Multiple Choice)
4.9/5 (76)
(76) A change in accounting estimate affected by a change in accounting principle should be reported as
(Multiple Choice)
4.9/5 (96)
(96) Which of the following accounting treatments is proper for a change in reporting entity?
(Multiple Choice)
4.8/5 (89)
(89) Exhibit 22-6 North Company has a fiscal year ending on December 31. Its financial statements for the years ended December 31, 2014 and 2015 contained the following errors: 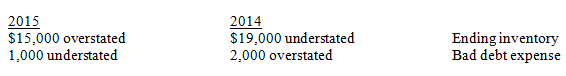 Assume no correcting entries have been made.
-Refer to Exhibit 22-6. By how much was North's 2015 net income overstated or understated?
Assume no correcting entries have been made.
-Refer to Exhibit 22-6. By how much was North's 2015 net income overstated or understated? (Multiple Choice)
4.8/5 (89)
(89) Bethany Corp. reported $80,000 of net income for 2014. The following errors were then discovered:
Ending 2014 accrued expense was overstated by $2,000.
2014 earned revenue was overstated by $3,000.
Ending 2014 prepaid expense was overstated by $500.
Ignoring income taxes, the correct 2014 net income is
(Multiple Choice)
4.9/5 (86)
(86) Sometimes a change in estimate and a change in accounting principle are undistinguishable therefore a company should account for the change as a change in accounting principle.
(True/False)
4.9/5 (71)
(71) On January 1, 2014, Sarah Company purchased for $60,000 a truck that had an estimated life of five years and no residual value at the end of its useful life. Sarah uses straight-line depreciation. The cost of the truck was charged to Repairs Expense when purchased in 2014.
Required:
a.Ignoring income taxes, prepare the journal entry to correct the error if it was discovered and corrected on January 1, 2017 (Sarah's year ends on December 31).
b.When preparing the 2017 financial statements, how much depreciation expense should be reported on the comparative 2015 and 2016 income statements?
(Essay)
4.9/5 (89)
(89) A change to GAAP from a principle that is not generally accepted
(Multiple Choice)
4.8/5 (83)
(83) Generally accepted methods of accounting for a change in accounting principle include
(Multiple Choice)
4.8/5 (81)
(81) Most errors are discovered automatically through proper use of the double-entry system or by the internal or external auditors. However, some errors escape detection until after they have been included in the published financial statements of a company.
Required:
Describe three types of errors that occur in financial statements and indicate the appropriate corrective action to take when the errors are discovered.
(Essay)
4.8/5 (86)
(86) Mark Company overstated the beginning inventory on January 1, 2014, by $20,000. No other errors were identified. If the error is not discovered, which of the following net income effects related to the inventory error are true? 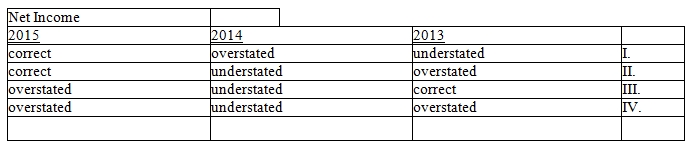
(Multiple Choice)
4.7/5 (82)
(82) A change in accounting principle from one that is not generally accepted to one that is generally accepted should be treated as
(Multiple Choice)
4.9/5 (66)
(66) Errors affecting only the balance sheet are corrected with a journal entry and do not require a restatement of financial statements.
(True/False)
4.8/5 (75)
(75) Exhibit 22-2 On January 1, 2015, Nathan, Inc. purchased a machine for $56,000. Eight-year, straight-line depreciation with no salvage value was used through December 31, 2016. On January 1, 2017, it was estimated that the total useful life of the machine from acquisition date was ten years.
-Refer to Exhibit 22-2. Accordingly, the appropriate accounting change was made in 2017. How much depreciation expense for this machine should Nathan record for the year ended December 31, 2017?
(Multiple Choice)
4.8/5 (65)
(65) Leah Co. reported $7,000 of net income for 2014. The following errors were then discovered:
Ending 2013 accrued expense was understated by $800.
Ending 2014 unearned revenue was overstated by $75.
Ending 2013 unearned revenue was overstated by $380.
Ignoring income taxes, compute correct 2014 net income.
(Multiple Choice)
4.8/5 (96)
(96) What are the 4 steps involved in the basic framework for the analysis and correction of an error?
(Essay)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)