



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


An LLC apportions and allocates its annual taxable income in the same manner used by any other business operating in the state.
(True/False)
4.8/5  (65)
(65) The sale of a used auto probably is exempt from sales/use tax under the _________________________ rule.
(Short Answer)
4.9/5 (71)
(71) State and local politicians tend to apply new and increased taxes to taxpayers who are visitors to the jurisdiction and cannot vote to reelect the lawmaker.
(True/False)
4.8/5 (75)
(75) Indicate for each transaction whether a sales (S)or use (U)applies,or whether the transaction is nontaxable (N).Where the laws vary among various states,assume that the most common rules apply.All taxpayers are individuals.
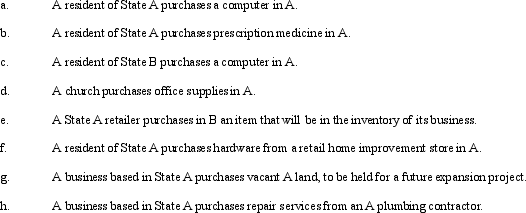
(Essay)
4.8/5 (79)
(79) In the apportionment formula,most states assign more than a one-third weight to the ____________________ factor.
(Short Answer)
4.8/5 (76)
(76) State A applies a throwback rule.General Corporation is taxable in a number of states.This year,General made a $100,000 sale from its A headquarters to an agency of the U.S.government.In which state(s)will the sale be included in the sales factor?
(Multiple Choice)
4.8/5 (85)
(85) ____________________ is a method under which specific components of a corporation's income are directly assigned to a specific state.
(Short Answer)
4.9/5 (86)
(86) Typical indicators of nexus include the presence of employees based in the state,and the ownership or lease of realty there.
(True/False)
5.0/5 (79)
(79) In most states,a limited liability company (LLC)is subject to the state income tax:
(Multiple Choice)
4.9/5 (88)
(88) Judy,a regional sales manager,has her office in State X.Her region includes several states,as indicated in the sales report below.Determine how much of Judy's $200,000 compensation is assigned to the payroll factor of State X. 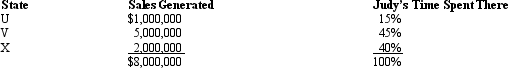
(Multiple Choice)
4.9/5 (94)
(94) The typical state sales/use tax falls on sales of both products and services.
(True/False)
4.9/5 (74)
(74) Usually a business chooses a location where it will build a new plant based chiefly on tax considerations.
(True/False)
4.7/5 (83)
(83) In determining a corporation's taxable income for state income tax purposes,which of the following does not constitute a subtraction from Federal income?
(Multiple Choice)
4.9/5 (73)
(73) Hermann Corporation is based in State A (corporate income tax rate 10%.It sells its goods to customers in both A and State B (corporate income tax rate 4%).Hermann's state taxable income for the year is $1 million,30% of which relates to B customers.Hermann's level of activities in B is insufficient to create nexus there,but A has adopted a throwback rule as to multistate sales.Would Hermann reduce its total state income tax liability by creating nexus with B,say by allowing its sales force to make credit decisions? Elaborate.
(Essay)
4.8/5 (77)
(77) Wailes Corporation is subject to a corporate income tax only in State X.The starting point in computing X taxable income is Federal taxable income.Wailes' Federal taxable income is $750,000,which includes a $75,000 deduction for state income taxes.During the year,Wailes received $20,000 interest on Federal obligations.X tax law does not allow a deduction for state income tax payments. Wailes' taxable income for X purposes is:
(Multiple Choice)
4.9/5 (69)
(69) A state or local tax on a corporation's income might be called a franchise tax or a business privilege tax.
(True/False)
4.8/5 (80)
(80) List some of the most commonly encountered state income tax modifications,used in computing state taxable income.
(Essay)
4.7/5 (82)
(82) In most states,a taxpayer's income is apportioned on the basis of a formula measuring the extent of business contact,and allocated according to the location of property owned or used.
(True/False)
4.9/5 (74)
(74) Identify some state/local income tax issues facing pass-through entities such as S corporations,partnerships,and LLCs.
(Essay)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)