



 Chat with AI
Exam 19: Corporations: Distributions Not in Complete Liquidation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


Brenda owns 900 shares of Eagle Corporation stock at a time when Eagle has 1,500 shares of stock outstanding.The remaining shareholders are unrelated to Brenda.What is the minimum number of shares Eagle must redeem from Brenda so that the transaction will qualify as a disproportionate redemption?
(Multiple Choice)
4.8/5  (78)
(78) Of the § 179 expense deducted in the current year,80% must be added to this year's taxable income to determine current E & P.
(True/False)
4.8/5 (77)
(77) As of January 1,Warbler Corporation has a deficit in accumulated E & P of $150,000.For the year,current E & P (accrued ratably)is $260,000 (prior to any distributions).On July 1,Warbler Corporation distributes $295,000 to its sole shareholder.The amount of the distribution that is a dividend is:
(Multiple Choice)
4.9/5 (93)
(93) Kingbird Corporation (E & P of $800,000)has 1,000 shares of stock outstanding.That stock is held by Amata (550 shares)and Esteban (450 shares),who are unrelated individuals.Kingbird redeems 200 of Amata's shares for $1,000 per share.Amata paid $300 per share for her Kingbird stock nine years ago.Which of the following statements is correct with respect to the stock redemption?
(Multiple Choice)
4.7/5 (74)
(74) Maria and Christopher each own 50% of Cockatoo Corporation,a calendar year taxpayer.Distributions from Cockatoo are: $750,000 to Maria on April 1 and $250,000 to Christopher on May 1.Cockatoo's current E & P is $300,000 and its accumulated E & P is $600,000.How much of the accumulated E & P is allocated to Christopher's distribution?
(Multiple Choice)
4.9/5 (93)
(93) Pursuant to a qualifying stock redemption,Redbird Corporation (E & P of $400,000)transfers land held for investment purposes to Bob,a 10% shareholder.On the date of the distribution,Redbird has a basis of $200,000 in the land and its fair market value is $150,000.Bob has a basis of $40,000 in the shares redeemed.With respect to the redemption:
(Multiple Choice)
4.9/5 (73)
(73) Which of the following is a correct statement regarding a redemption to pay death taxes under § 303?
(Multiple Choice)
5.0/5 (72)
(72) The dividends received deduction is added back to taxable income to determine E & P.
(True/False)
4.9/5 (64)
(64) In a not essentially equivalent redemption [§ 302(b)(1)],the family attribution rules of § 318 apply.
(True/False)
4.8/5 (69)
(69) Canary Corporation has 1,000 shares of stock outstanding.It redeems in a qualifying stock redemption 200 shares for $200,000 at a time when it has paid-in capital of $100,000 and E & P of $800,000.What would be the charge to Canary's E & P as a result of the redemption?
(Multiple Choice)
4.8/5 (84)
(84) Jose receives a nontaxable distribution of stock rights during the year from Gold Corporation on January 30.Each right entitles the holder to purchase one share of stock for $50.One right is issued for every share of stock owned.Jose owns 100 shares of stock purchased two years ago for $5,000.At the date of distribution,the rights are worth $1,000 (100 rights at $10 per right)and Jose's stock in Gold is worth $6,000 (or $60 per share).On December 1,Jose sells all stock rights for $13 per right.How much gain does Jose recognize on the sale?
(Multiple Choice)
4.9/5 (84)
(84) When current E & P is positive and accumulated E & P has a deficit balance,the two accounts are netted for dividend determination purposes.
(True/False)
4.8/5 (80)
(80) Dividends from foreign corporations are not qualified dividends.
(True/False)
4.9/5 (71)
(71) Distributions by a corporation to its shareholders are presumed to be a return of capital unless the parties can prove otherwise.
(True/False)
4.9/5 (83)
(83) In the current year,Loon Corporation made a distribution in redemption of some of its shares.Loon incurred expenditures in connection with the redemption totaling $30,000 (accounting fees of $10,000,legal fees of $15,000,and brokerage fees of $5,000).The distribution was a qualifying stock redemption.How much of the $30,000 is deductible in the current year?
(Multiple Choice)
4.9/5 (91)
(91) Jill has a capital loss carryover in the current tax year of $80,000.She owns 1,000 shares of stock in Black Corporation which she purchased nine years ago for $75 per share.In the current year,Black Corporation (E & P of $800,000)redeems all of her shares for $600,000.Jill is in the 35% tax bracket.What are the tax consequences to Jill if:
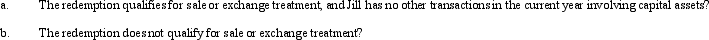
(Essay)
4.9/5 (90)
(90) If stock rights are taxable,the recipient has income to the extent of the fair market value of the rights.
(True/False)
4.8/5 (77)
(77) Blue Corporation distributes property to its sole shareholder,Zeke.The property has a fair market value of $450,000,an adjusted basis of $305,000,and is subject to a liability of $250,000.Current E & P is $550,000.With respect to the distribution,Blue has a gain of:
(Multiple Choice)
5.0/5 (92)
(92) Explain the requirements for waiving the family attribution rules in the case of complete termination redemptions.
(Essay)
4.9/5 (96)
(96) Sam's gross estate includes stock in Tern Corporation and Wren Corporation,valued at $700,000 and $900,000,respectively.At the time of Sam's death in 2009,the stock represented 27% of Tern's outstanding stock and 38% of Wren's outstanding stock.Sam's adjusted gross estate equals $4,400,000.Death taxes and funeral and administration expenses for Sam's estate total $700,000.Sam had a basis of $120,000 in the Tern stock and $300,000 in the Wren stock at the time of his death.None of the beneficiaries of Sam's estate own (directly or indirectly)any stock in Wren Corporation,but some of the beneficiaries own stock of Tern Corporation.Consider the following independent questions.
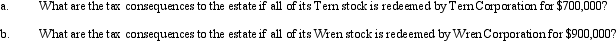
(Essay)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)