



 Chat with AI
Exam 16: Accounting Periods and Methods

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


A doctor's incorporated medical practice,generally,must have a business purpose for using a tax year that does not end on December 31.
(True/False)
4.9/5  (69)
(69) In 2010,Father sold land to Son for $75,000 cash and an installment note for $225,000.Father's basis was $120,000.In 2011,after paying $24,000 interest but nothing on the principal,Son sold the land for $300,000 cash.As a result of the second disposition,what gain must Father recognize in 2011?
(Multiple Choice)
4.8/5 (87)
(87) Brown Corporation had consistently reported its income by the cash method.The corporation should have used the accrual method because inventories are material to the business.In 2010,Brown timely filed a request to change to the accrual method.At the beginning of 2010,Brown had accounts receivable of $60,000.Also,Brown had merchandise on hand with a cost of $80,000 and accounts payable for merchandise of $25,000.The accounts receivable,inventory,and accounts payable balance per books were zero.Determine the adjustment to income due to the change in accounting method and the amount that is allocated to 2010.
(Essay)
4.9/5 (77)
(77) Karen,an accrual basis taxpayer,sold goods in October 2010 for $10,000.The customer was unable to pay cash.So the customer gave Karen a note for $10,000 that was payable in April 2011.The note bore interest at the Federal rate.The fair market value of the note at the end of 2010 was $9,000.Karen collected $10,000 from the customer in April 2011.Under the accrual method:
(Multiple Choice)
4.8/5 (79)
(79) Which of the following taxpayers is required to use the accrual method of accounting?
(Multiple Choice)
4.8/5 (79)
(79) Ramon sold land in 2010 with a cost of $60,000 for $100,000.The sales agreement called for a $25,000 down payment and a $25,000 payment on the first day of each year plus 8% interest.What would be the consequences of the following (treat each part independently and assume Ramon uses the installment method whenever possible):

(Essay)
4.9/5 (85)
(85) Terry,Inc. ,makes gasoline storage tanks.All production is done under contract.The company makes three basic models,but each model must be adapted to customer specifications for the location of outlets,insulation,and paint.It takes from three to six months to complete a tank.How should Terry account for the income for the business?
(Essay)
4.8/5 (72)
(72) Ted,a cash basis taxpayer,received a $100,000 bonus in 2010 when he was in the 35% marginal tax bracket.In 2011,when Ted was in the 28% marginal tax bracket,it was discovered that the bonus was incorrectly computed,and Ted was required to refund $25,000 to his employer.As a result of the refund,Ted can reduce his 2011 tax liability by $8,750 (.35 * $25,000).
(True/False)
4.9/5 (74)
(74) Which of the following statements regarding a 52-53 week tax year is not correct?
(Multiple Choice)
4.9/5 (80)
(80) If an installment sale contract does not charge interest on the sale of a capital asset,the IRS will impute interest and thereby increase the taxpayer's capital gain and interest income.
(True/False)
4.7/5 (69)
(69) Gold Corporation,Silver Corporation,and Copper Corporation are equal partners in the GSC Partnership.The partners' tax year-ends are as follows: 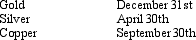
(Multiple Choice)
4.9/5 (72)
(72) The installment method applies where a payment will be received after the tax year of the sale:
(Multiple Choice)
4.7/5 (68)
(68) For purposes of determining the partnership's tax year,there may be more than one principal partner.
(True/False)
4.8/5 (78)
(78) The taxpayer has consistently,but incorrectly,used an allowance for bad debts.At the beginning of the year,the balance in the allowance account is $90,000.
(Multiple Choice)
4.8/5 (72)
(72) Related-party installment sales include all of the following except the first seller's:
(Multiple Choice)
4.8/5 (85)
(85) Albert is in the 35% marginal tax bracket.He sold a building in the current year for $450,000.Albert received $110,000 cash at closing,the buyer assumed Albert's mortgage for $120,000,and the buyer gave Albert a 6% note for $220,000 due in two years.The Federal rate was 6%.Albert's basis in the building was $180,000 ($500,000 cost - $320,000 accumulated straight-line depreciation).Assuming he did not elect out of the installment method,Albert's § 1231 gain and gain taxed at the 25% rate in the year of sale are what amounts? Section 1231 Gain Unrecaptured § 1250 Gain Taxed at 25%
(Multiple Choice)
4.8/5 (87)
(87) When the IRS requires a taxpayer to change accounting methods:
(Multiple Choice)
4.8/5 (79)
(79) For a taxpayer who is required to use the percentage of completion method,the taxpayer can elect to defer the recognition of income and the related costs until the taxable year in which cumulative contract costs are at least 10 percent of the estimated contract costs.
(True/False)
4.9/5 (92)
(92) Franklin Company began business in 2008 and has consistently used the cash method to report income from the sale of inventory in income tax returns filed for 2008 through 2010.As a result of an audit by the IRS,Franklin was required to change to the accrual method of accounting beginning with 2011.The accounts receivable and inventory on hand at the end of 2010 are treated as a positive adjustment to income and the accounts payable for inventory at the end of 2010 is a negative adjustment to income.These adjustments result from changing accounting methods and must be included in the 2010 taxable income.
(True/False)
4.9/5 (86)
(86) In the case of an accrual basis taxpayer,an item of income:
(Multiple Choice)
5.0/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)