



 Chat with AI
Exam 15: Alternative Minimum Tax

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law139 Questions
Exam 2: Working With the Tax Law78 Questions
Exam 3: Computing the Tax130 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General144 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses90 Questions
Exam 8: Depreciation,cost Recovery,amortization,and Depletion108 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses150 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions100 Questions
Exam 11: Investor Losses94 Questions
Exam 12: Tax Credits and Payments104 Questions
Exam 13: Part 1--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges199 Questions
Exam 13: Part 2--Property Transactions: Determination of Gain or Loss,basis Considerations,and Nontaxable Exchanges82 Questions
Exam 14: Property Transactions: Capital Gains and Losses,1231,and Recapure Provisions144 Questions
Exam 15: Alternative Minimum Tax119 Questions
Exam 16: Accounting Periods and Methods86 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation136 Questions
Exam 20: Distributions in Complete Liquidation and an Overview of Reorganizations66 Questions
Exam 21: Partnerships157 Questions
Exam 22: S Corporations144 Questions
Exam 23: Exempt Entities132 Questions
Exam 24: Multistate Corporate Taxation119 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics135 Questions
Exam 27: The Federal Gift and Estate Taxes144 Questions
Exam 28: Income Taxation of Trusts and Estates132 Questions
Select questions type


As to the AMT,a C corporation has no adjustments or preferences for itemized deductions.
(True/False)
4.8/5  (74)
(74) Tammy expensed mining exploration and development costs of $100,000 incurred in 2010.She will be required to make negative AMT adjustments for each of the next nine years and a positive AMT adjustment in the current tax year.
(True/False)
4.9/5 (81)
(81) The AMT adjustment for mining exploration and development costs can be avoided if the taxpayer elects to write off the expenditures over a 10-year period,rather than being expensed in the year incurred for regular income tax purposes.
(True/False)
4.9/5 (83)
(83) Erin owns a mineral property that had a basis of $10,000 at the beginning of the year.The property qualifies for a 15% depletion rate.Gross income from the property was $120,000 and net income before the percentage depletion deduction was $50,000.What is Erin's tax preference for excess depletion?
(Multiple Choice)
4.8/5 (62)
(62) Land that originally cost $100,000 is sold for $80,000.There is a negative AMT adjustment of $20,000 associated with the sale of the land.
(True/False)
4.8/5 (70)
(70) All of a corporation's AMT is available for carryover as a minimum tax credit regardless of whether the adjustments and preferences originate from timing differences or AMT exclusions.
(True/False)
4.7/5 (75)
(75) In September,Dorothy purchases a building for $900,000 to use in her business as a warehouse.Dorothy uses the depreciation method which will provide her with the greatest deduction for regular income tax purposes.

(Essay)
4.8/5 (87)
(87) Peter incurred circulation expenditures of $210,000 in 2010 and deducted that amount for regular income tax purposes.Peter has a $70,000 negative AMT adjustment for 2011,for 2012,and for 2013.
(True/False)
4.9/5 (92)
(92) Andrea,who is single,has a personal exemption deduction in calculating her 2010 taxable income.She has no dependency deductions.What is the amount of the AMT adjustment in calculating AMTI?
(Essay)
4.9/5 (74)
(74) Durell owns a construction company that builds residential housing.The company is eligible to use the completed contract method for regular income tax purposes.What can Durell do to minimize his AMT?
(Essay)
4.9/5 (87)
(87) Joel placed real property in service in 2010 that cost $500,000 and used MACRS for regular income tax purposes.He is required to make a positive adjustment for AMT purposes in 2010.
(True/False)
4.7/5 (77)
(77) Since most tax preferences are merely timing differences,they eventually will reverse and net to zero.
(True/False)
4.8/5 (93)
(93) Robin,who is a head of household and age 42,provides you with the following information from his financial records for 2010.  Calculate his AMT for 2010.
 (Multiple Choice)
4.9/5 (74)
(74) For a building placed in service before 1999,the adjusted basis can be different for regular income tax purposes and for AMT purposes.
(True/False)
4.9/5 (87)
(87) The phaseout of the AMT exemption amount for a taxpayer filing as a head of household both begins and ends at a lower income level than it does for a married taxpayer who files a joint return.
(True/False)
4.7/5 (75)
(75) If a single taxpayer has regular income tax liability of $19,500 and AMTI of $130,000,calculate the AMT for 2010.
(Multiple Choice)
4.8/5 (74)
(74) In 2010,Olive incurs circulation expenses of $150,000 which she deducts in calculating taxable income.
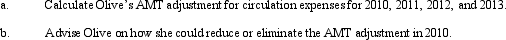
(Essay)
4.8/5 (94)
(94) Discuss the tax year in which an AMT adjustment is first required for an ISO.
(Essay)
5.0/5 (88)
(88) The AMT exemption for C corporations is $40,000 reduced by 25% of the amount by which AMTI exceeds $150,000.
(True/False)
4.9/5 (84)
(84) Jan's tentative AMT is $32,500.Her regular income tax liability is $29,000.Jan's AMT is $3,500.
(True/False)
4.7/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)