



 Chat with AI
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


A monopolistically competitive firm can increase its profits beyond the long-run equilibrium break-even level by deliberately lowering its price to force some of its competitors out of the market.
(True/False)
4.9/5  (82)
(82) Figure 13-17 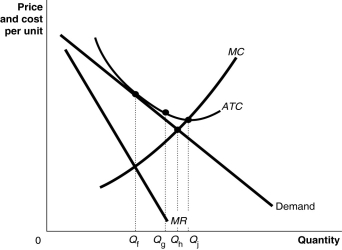 -Refer to Figure 13-17. Suppose the firm is currently producing Qf units. What happens if it increases its output to Qg units?
 (Multiple Choice)
4.9/5 (74)
(74) Firms in monopolistic competition compete by selling similar, but not identical products.
(True/False)
4.8/5 (78)
(78) If a monopolistically competitive firm is producing 50 units of output where marginal cost equals marginal revenue, total cost is $1,674 and total revenue is $2,000, its average profit is
(Multiple Choice)
4.8/5 (80)
(80) Monopolistically competitive firms can differentiate their products
(Multiple Choice)
5.0/5 (86)
(86) Which of the following statements is true about advertising by a monopolistically competitive firm?
(Multiple Choice)
4.9/5 (89)
(89) When a monopolistically competitive firm lowers it price one bad thing happens to the firm. What is this "one bad thing" called?
(Multiple Choice)
4.8/5 (87)
(87) A firm that is first to the market with a new product frequently discovers that there are design flaws or problems with the product that were not anticipated. How do these problems affect the innovating firm?
(Multiple Choice)
4.9/5 (72)
(72) Table 13-2
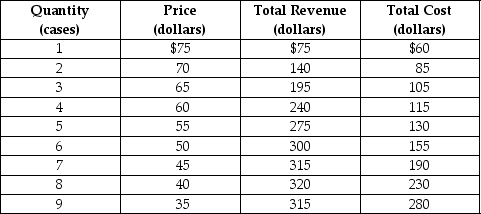 Eco Energy is a monopolistically competitive producer of a sports beverage called Power On. Table 13-2 shows the firm's demand and cost schedules.
-Refer to Table 13-2. What is Eco Energy's profit?
Eco Energy is a monopolistically competitive producer of a sports beverage called Power On. Table 13-2 shows the firm's demand and cost schedules.
-Refer to Table 13-2. What is Eco Energy's profit? (Multiple Choice)
4.9/5 (77)
(77) In the long run, firms in both monopolistically competitive markets and perfectly competitive markets earn zero economic profits, but unlike perfectly competitive firms in the long run, monopolistically competitive firms
(Multiple Choice)
4.8/5 (71)
(71) New firms are able to enter monopolistically competitive markets because there are low barriers to entry.
(True/False)
4.9/5 (72)
(72) When a monopolistically competitive firm lowers its price, one good thing happens to the firm. What is this "one good thing" called?
(Multiple Choice)
4.8/5 (79)
(79) What is the difference between the terms "marketing" and "advertising"?
(Essay)
4.9/5 (80)
(80) The entry and exit of firms in a monopolistically competitive market guarantee that
(Multiple Choice)
4.7/5 (83)
(83) Figure 13-6 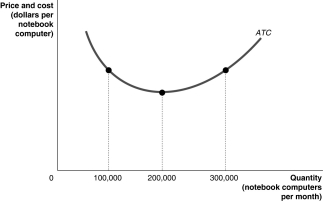 -You are planning to open a new Italian restaurant in your hometown where there are three other Italian restaurants. You plan to distinguish your restaurant from your competitors by offering northern Italian cuisine and using locally grown organic produce. What is likely to happen in the restaurant market in your hometown after you open?
 (Multiple Choice)
4.9/5 (72)
(72) Table 13-4
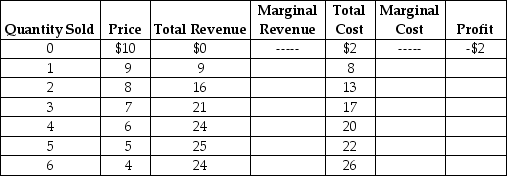 Table 13-4 lists estimated revenues and costs (per week) for plastic vials (100 vials per box) for the Victoria Biological Supplies Company. Victoria sells plastic vials to university and private research laboratories.
-Refer to Table 13-4. Victoria's profit-maximizing quantity sold (Q) and price (P) are
Table 13-4 lists estimated revenues and costs (per week) for plastic vials (100 vials per box) for the Victoria Biological Supplies Company. Victoria sells plastic vials to university and private research laboratories.
-Refer to Table 13-4. Victoria's profit-maximizing quantity sold (Q) and price (P) are (Multiple Choice)
4.8/5 (80)
(80) Economists have long debated whether there is a significant loss of well-being to society in markets that are monopolistically competitive rather than perfectly competitive. Which of the following offers the best reason why some economists believe that monopolistically competitive markets benefit consumers despite any loss of well-being?
(Multiple Choice)
4.9/5 (80)
(80) Figure 13-5 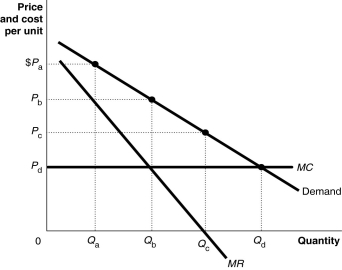 -Refer to Figure 13-5. The candy store represented in the diagram is currently selling Qa units of candy at a price of Pa. Is this candy store maximizing its profit and if it is not, what would you recommend to the firm?
 (Multiple Choice)
4.9/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)