



 Chat with AI
Exam 7: Asset Pricing Models

Exam 1: The Investment Setting72 Questions
Exam 1: The Investment Setting: Part A6 Questions
Exam 2: Asset Allocation and Security Selection77 Questions
Exam 2: Asset Allocation and Security Selection: Part A3 Questions
Exam 3: Organization and Functioning of Securities Markets87 Questions
Exam 4: Security Market Indexes and Index Funds89 Questions
Exam 5: Efficient Capital Markets, Behavioral Finance, and Technical Analysis162 Questions
Exam 6: An Introduction to Portfolio Management114 Questions
Exam 6: An Introduction to Portfolio Management: Part A2 Questions
Exam 6: An Introduction to Portfolio Management: Part B2 Questions
Exam 7: Asset Pricing Models152 Questions
Exam 8: Equity Valuation83 Questions
Exam 9: The Top-Down Approach to Market, Industry, and Company Analysis216 Questions
Exam 10: The Practice of Fundamental Investing60 Questions
Exam 11: Equity Portfolio Management Strategies65 Questions
Exam 12: Bond Fundamentals and Valuation138 Questions
Exam 13: Bond Analysis and Portfolio Management Strategies125 Questions
Exam 14: An Introduction to Derivative Markets and Securities102 Questions
Exam 15: Forward, Futures, and Swap Contracts148 Questions
Exam 16: Option Contracts122 Questions
Exam 17: Professional Money Management, Alternative Assets, and Industry Ethics109 Questions
Exam 18: Evaluation of Portfolio Performance111 Questions
Select questions type


Cho, Elton, and Gruber tested the APT by examining the number of factors in the return generating process and found that
(Multiple Choice)
4.8/5  (78)
(78) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
You expect the risk-free rate (RFR) to be 3 percent and the market return to be 8 percent. You also have the following information about three stocks.
 -Refer to Exhibit 7.2. What are the expected (required) rates of return for the three stocks (in the order X, Y, Z)?
 (Multiple Choice)
4.8/5 (68)
(68) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Stocks A, B, and C have two risk factors with the following beta coefficients. The zero-beta return ( 0) = .025 and the risk premiums for the two factors are ( 1) = .12 and ( 0) = .10.
 -Refer to Exhibit 7.10. Suppose that you know that the prices of stocks A, B, and C will be $10.95, 22.18, and $30.89, respectively. Based on this information,
 (Multiple Choice)
4.8/5 (79)
(79) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
You expect the risk-free rate (RFR) to be 4 percent and the market return to be 10 percent. You also have the following information about three stocks.
 -Refer to Exhibit 7.7. What are the estimated rates of return for the three stocks (in the order A, B, C)?
 (Multiple Choice)
4.8/5 (92)
(92) Assume the risk-free rate is 4.5 percent and the expected return on the market is 11 percent. You anticipate Stock XYZ to sell for $28 at the end of next year and pay a dividend of $2. The stock is currently selling for $26.50 with a beta of 1.2. You currently hold stock XYZ in a well-diversified portfolio. Assuming you have money to invest, you should
(Multiple Choice)
5.0/5 (82)
(82) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
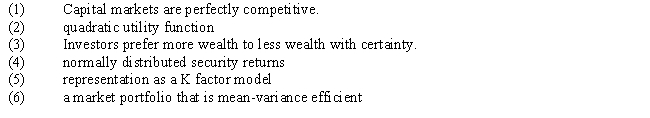 -Refer to Exhibit 7.8. In the list above, which are NOT assumptions of the Arbitrage Pricing model?
 (Multiple Choice)
5.0/5 (80)
(80) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
 -Refer to Exhibit 7.3. What is the beta for Radtron using the true index?
 (Multiple Choice)
4.9/5 (77)
(77) The table below provides factor risk sensitivities and factor risk premia for a three-factor model for a particular asset, where factor 1 is MP (the growth rate in U.S. industrial production), factor 2 is UI (the difference between actual and expected inflation), and factor 3 is UPR (the unanticipated change in bond credit spread). 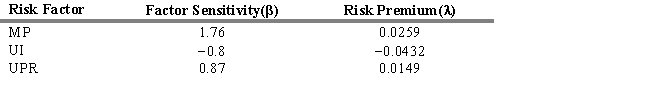 Calculate the expected excess return for the asset.
 (Multiple Choice)
4.8/5 (68)
(68) A 1994 study by Burmeister, Roll, and Ross defined all of the following risk factors EXCEPT
(Multiple Choice)
4.7/5 (78)
(78) Consider the following list of risk factors: 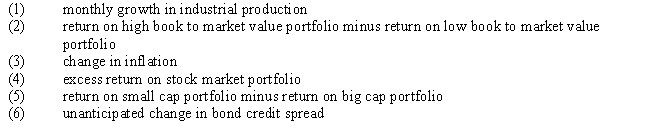 Which of the following factors would you use to develop a macroeconomic-based risk factor model?
 (Multiple Choice)
4.9/5 (80)
(80) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
Consider the three stocks, stock X, stock Y, and stock Z, that have the following factor loadings (or factor betas).
 The zero-beta return ( 0) = 3 percent, and the risk premia are 1 = 10 percent and 2 = 8 percent. Assume that all three stocks are currently priced at $50.
-Refer to Exhibit 7.9. The expected prices one year from now for stocks X, Y, and Z are
The zero-beta return ( 0) = 3 percent, and the risk premia are 1 = 10 percent and 2 = 8 percent. Assume that all three stocks are currently priced at $50.
-Refer to Exhibit 7.9. The expected prices one year from now for stocks X, Y, and Z are (Multiple Choice)
4.9/5 (78)
(78) Studies strongly suggest that the CAPM be abandoned and replaced with the APT.
(True/False)
4.9/5 (88)
(88) Calculate the expected return for A Industries, which has a beta of 1.75 when the risk free rate is 0.03 and you expect the market return to be 0.11.
(Multiple Choice)
4.8/5 (88)
(88) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
 -Refer to Exhibit 7.1. If you expected the return on the Market Index to be 12%, what would you expect the return on RA Computer to be?
 (Multiple Choice)
4.9/5 (76)
(76) Consider a two-factor APT model in which the first factor is changes in the 30-year T-bond rate, and the second factor is the percent growth in GNP. Based on historical estimates, you determine that the risk premium for the interest rate factor is 0.02, and the risk premium on the GNP factor is 0.03. For a particular asset, the response coefficient for the interest rate factor is -1.2, and the response coefficient for the GNP factor is 0.80. The rate of return on the zero-beta asset is 0.03. Calculate the expected return for the asset.
(Multiple Choice)
4.9/5 (76)
(76) An investor wishes to construct a portfolio by borrowing 30 percent of his initial wealth at the risk-free rate of 3 percent and investing all the money in a stock index. The expected return on the stock index is 12 percent. Calculate the expected return on the portfolio.
(Multiple Choice)
4.7/5 (88)
(88) Under the following conditions, what are the expected returns for stocks A and C? 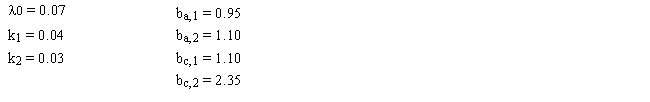
(Multiple Choice)
4.8/5 (86)
(86) Multifactor models of risk and return can be broadly grouped into models that use macroeconomic factors and models that use microeconomic factors.
(True/False)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)