



 Chat with AI
Exam 7: Asset Pricing Models

Exam 1: The Investment Setting72 Questions
Exam 1: The Investment Setting: Part A6 Questions
Exam 2: Asset Allocation and Security Selection77 Questions
Exam 2: Asset Allocation and Security Selection: Part A3 Questions
Exam 3: Organization and Functioning of Securities Markets87 Questions
Exam 4: Security Market Indexes and Index Funds89 Questions
Exam 5: Efficient Capital Markets, Behavioral Finance, and Technical Analysis162 Questions
Exam 6: An Introduction to Portfolio Management114 Questions
Exam 6: An Introduction to Portfolio Management: Part A2 Questions
Exam 6: An Introduction to Portfolio Management: Part B2 Questions
Exam 7: Asset Pricing Models152 Questions
Exam 8: Equity Valuation83 Questions
Exam 9: The Top-Down Approach to Market, Industry, and Company Analysis216 Questions
Exam 10: The Practice of Fundamental Investing60 Questions
Exam 11: Equity Portfolio Management Strategies65 Questions
Exam 12: Bond Fundamentals and Valuation138 Questions
Exam 13: Bond Analysis and Portfolio Management Strategies125 Questions
Exam 14: An Introduction to Derivative Markets and Securities102 Questions
Exam 15: Forward, Futures, and Swap Contracts148 Questions
Exam 16: Option Contracts122 Questions
Exam 17: Professional Money Management, Alternative Assets, and Industry Ethics109 Questions
Exam 18: Evaluation of Portfolio Performance111 Questions
Select questions type


If the assumption that there are no transaction costs is relaxed, the SML will be a
(Multiple Choice)
4.8/5  (72)
(72) The usefulness of CAPM theory is limited in practice due to benchmark error.
(True/False)
4.7/5 (97)
(97) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
 -Refer to Exhibit 7.3. The covariance between Radtron and the proxy index is
 (Multiple Choice)
4.8/5 (83)
(83) The ____ the number of stocks in a portfolio and the ____ the time period, the ____ the portfolio beta.
(Multiple Choice)
4.8/5 (78)
(78) Dhrymes, Friend, and Gultekin, in their study of the APT, found that
(Multiple Choice)
4.8/5 (82)
(82) If an individual owns only one security the most appropriate measure of risk is
(Multiple Choice)
4.8/5 (77)
(77) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
You expect the risk-free rate (RFR) to be 4 percent and the market return to be 10 percent. You also have the following information about three stocks.
 -Refer to Exhibit 7.7. What are the required rates of return for the three stocks (in the order A, B, C)?
 (Multiple Choice)
4.8/5 (76)
(76) Under the following conditions, what are the expected returns for stocks X and Y? 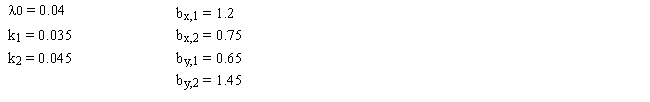
(Multiple Choice)
4.8/5 (75)
(75) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
You expect the risk-free rate (RFR) to be 3 percent and the market return to be 8 percent. You also have the following information about three stocks.
 -Refer to Exhibit 7.2. What are the estimated rates of return for the three stocks (in the order X, Y, Z)?
 (Multiple Choice)
4.8/5 (79)
(79) The error caused by NOT using the true market portfolio has become known as the
(Multiple Choice)
4.9/5 (79)
(79) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
You expect the risk-free rate (RFR) to be 3 percent and the market return to be 8 percent. You also have the following information about three stocks.
-Refer to Exhibit 7.2. What is your investment strategy concerning the three stocks?
-Refer to Exhibit 7.2. What is your investment strategy concerning the three stocks? (Multiple Choice)
4.9/5 (75)
(75) According to the APT model, all securities should be priced such that riskless arbitrage is possible.
(True/False)
4.9/5 (80)
(80) Findings by Fama and French that stocks with high Book Value to Market Price ratios tended to produce larger risk adjusted returns than stocks with low Book Value to Market Price ratios challenge the efficacy of the CAPM.
(True/False)
4.8/5 (84)
(84) Under the following conditions, what are the expected returns for stocks X and Y? 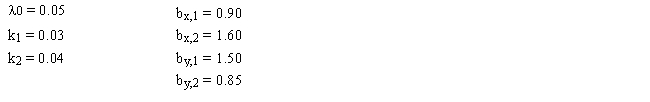
(Multiple Choice)
4.9/5 (69)
(69) Under the following conditions, what are the expected returns for stocks A and B? 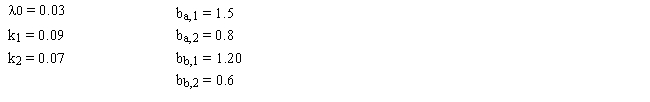
(Multiple Choice)
4.9/5 (84)
(84) Overall, the correlation coefficients of industries to the market portfolio vary widely, which is expected due to the wide variance of industry Betas.
(True/False)
4.8/5 (95)
(95) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
 -Refer to Exhibit 7.4. What are the expected returns for stocks X, Y, and Z for the next period based on the above prices and dividends? X Y Z
 (Multiple Choice)
4.8/5 (77)
(77) All of the following are assumptions of the Capital Asset Pricing Model (CAPM) EXCEPT
(Multiple Choice)
4.9/5 (79)
(79) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
You expect the risk-free rate (RFR) to be 4 percent and the market return to be 10 percent. You also have the following information about three stocks.
-Refer to Exhibit 7.7. What is your investment strategy concerning the three stocks?
-Refer to Exhibit 7.7. What is your investment strategy concerning the three stocks? (Multiple Choice)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)