



 Chat with AI
Exam 7: Asset Pricing Models

Exam 1: The Investment Setting72 Questions
Exam 1: The Investment Setting: Part A6 Questions
Exam 2: Asset Allocation and Security Selection77 Questions
Exam 2: Asset Allocation and Security Selection: Part A3 Questions
Exam 3: Organization and Functioning of Securities Markets87 Questions
Exam 4: Security Market Indexes and Index Funds89 Questions
Exam 5: Efficient Capital Markets, Behavioral Finance, and Technical Analysis162 Questions
Exam 6: An Introduction to Portfolio Management114 Questions
Exam 6: An Introduction to Portfolio Management: Part A2 Questions
Exam 6: An Introduction to Portfolio Management: Part B2 Questions
Exam 7: Asset Pricing Models152 Questions
Exam 8: Equity Valuation83 Questions
Exam 9: The Top-Down Approach to Market, Industry, and Company Analysis216 Questions
Exam 10: The Practice of Fundamental Investing60 Questions
Exam 11: Equity Portfolio Management Strategies65 Questions
Exam 12: Bond Fundamentals and Valuation138 Questions
Exam 13: Bond Analysis and Portfolio Management Strategies125 Questions
Exam 14: An Introduction to Derivative Markets and Securities102 Questions
Exam 15: Forward, Futures, and Swap Contracts148 Questions
Exam 16: Option Contracts122 Questions
Exam 17: Professional Money Management, Alternative Assets, and Industry Ethics109 Questions
Exam 18: Evaluation of Portfolio Performance111 Questions
Select questions type


Under the following conditions, what are the expected returns for stocks Y and Z? 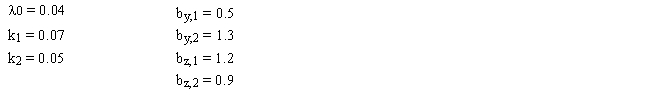
(Multiple Choice)
4.7/5  (82)
(82) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
 -Refer to Exhibit 7.3. What is the beta for Radtron using the proxy index?
 (Multiple Choice)
4.9/5 (88)
(88) Fama and French suggest a four-factor model approach that explains many prior market anomalies.
(True/False)
4.9/5 (94)
(94) A friend has information that the stock of Zip Incorporated is going to rise from $62.00 to $65.00 per share over the next year. You know that the annual return on the S&P 500 has been 10 percent and the 90-day T-bill rate has been yielding 6 percent per year over the past 10 years. If beta for Zip is 0.9, will you purchase the stock?
(Multiple Choice)
4.9/5 (69)
(69) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
 -Refer to Exhibit 7.1. Compute the intercept of the characteristic line for RA Computer.
 (Multiple Choice)
5.0/5 (81)
(81) Calculate the expected return for F Inc., which has a beta of 1.3 when the risk-free rate is 0.06 and you expect the market return to be 0.125.
(Multiple Choice)
4.8/5 (89)
(89) CML and SML measure total risk by the standard deviation of the investment.
(True/False)
4.9/5 (87)
(87) Which of the following is NOTa relaxation of the assumptions for the CAPM?
(Multiple Choice)
4.8/5 (83)
(83) An investor wishes to construct a portfolio consisting of a 70 percent allocation to a stock index and a 30 percent allocation to a risk-free asset. The return on the risk-free asset is 4.5 percent, and the expected return on the stock index is 12 percent. The standard deviation of returns on the stock index is 6 percent. Calculate the expected standard deviation of the portfolio.
(Multiple Choice)
4.8/5 (84)
(84) The existence of transaction costs indicates that at some point the additional cost of diversification relative to its benefit would be excessive for most investors.
(True/False)
4.8/5 (79)
(79) To date, the results of empirical tests of the Arbitrage Pricing Model have been
(Multiple Choice)
4.8/5 (73)
(73) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
 -Refer to Exhibit 7.4. Which of the following statements is correct?
 (Multiple Choice)
4.9/5 (87)
(87) The fact that tests have shown the CAPM intercept to be greater than the RFR is consistent with a(n)
(Multiple Choice)
4.7/5 (65)
(65) Calculate the expected return for C Inc., which has a beta of 0.8 when the risk-free rate is 0.04 and you expect the market return to be 0.12.
(Multiple Choice)
4.9/5 (89)
(89) Consider the following two factor APT model: E(R) = 0 + 1b1 + 2b2
(Multiple Choice)
4.9/5 (67)
(67) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
-Refer to Exhibit 7.3. The covariance between Radtron and the true index is
-Refer to Exhibit 7.3. The covariance between Radtron and the true index is (Multiple Choice)
5.0/5 (85)
(85) Consider the following list of risk factors: 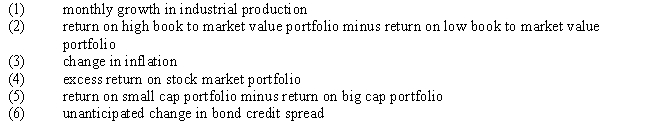 Which of the following factors would you use to develop a microeconomic-based risk factor model?
 (Multiple Choice)
4.8/5 (78)
(78) USE THE INFORMATION BELOW FOR THE FOLLOWING PROBLEM(S)
-Refer to Exhibit 7.1. Compute the correlation coefficient between RA Computer and the Market Index.
-Refer to Exhibit 7.1. Compute the correlation coefficient between RA Computer and the Market Index. (Multiple Choice)
4.7/5 (81)
(81) Assume that the risk-free rate of return is 3 percent and the market portfolio on the Capital Market Line (CML) has an expected return of 11 percent and a standard deviation of 14 percent. How should you invest $100,000 if you are only willing to accept a total portfolio risk of 8 percent?
(Multiple Choice)
4.7/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)