



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


An S shareholder's basis in his or her stock can be reduced below zero.
(True/False)
4.9/5  (71)
(71) Depreciation recapture income is a ____________________ computed amount.
(Short Answer)
4.7/5 (96)
(96) An S shareholder who dies during the corporate tax year must report his or her share of the pro rata income (or loss)up to the date of death on the final individual tax return.
(True/False)
4.8/5 (74)
(74) List some of the separately stated items listed on Schedule K of the Form 1120S.
(Essay)
4.7/5 (70)
(70) Net operating losses incurred before an S election do not flow through to the shareholders once the election is in effect.
(True/False)
4.8/5 (86)
(86) A distribution of cash or other property by an S corporation to shareholders that does not exceed the balance of AAA during a one-year period following an S election termination receives special capital gain treatment.
(True/False)
4.8/5 (71)
(71) Mock Corporation converts to S corporation status in 2012.Mock used the LIFO inventory method in 2011 and had a LIFO inventory of $435,000 (FIFO value of $550,000)on the date of the S election.How much tax must be added to the 2011 corporate tax liability,assuming that Mock is subject to a 35% tax rate.
(Multiple Choice)
5.0/5 (76)
(76) An S corporation may not have a ____________________ alien shareholder.
(Short Answer)
4.8/5 (78)
(78) During 2012,Rasic,the sole shareholder of a calendar year S corporation,received a distribution of $16,000.On December 31,2011,Rasic's stock basis was $4,000.The corporation earned $11,000 ordinary income during the year.Calculate the amount and type of income that Rasic recognizes in 2012,assuming that there is no C corporation AEP.
(Essay)
4.9/5 (83)
(83) Which statement is correct with respect to an S corporation?
(Multiple Choice)
4.9/5 (87)
(87) Towne,Inc. ,a calendar year S corporation,has an AAA amount of $627,050 at the beginning of 2012.During the year,the following items occur.
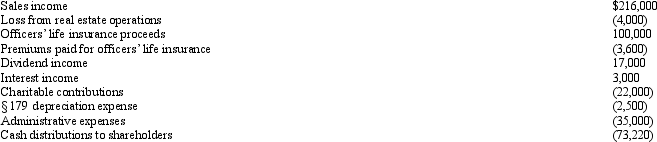 Calculate Towne's ending AAA balance.
 (Essay)
4.8/5 (67)
(67) ____________________ common stock and ____________________ preferred stock (with preference on dividends)are treated as two different classes of stock by the S corporation rules.
(Short Answer)
4.7/5 (83)
(83) Which statement is incorrect with respect to an S shareholder's consent?
(Multiple Choice)
4.9/5 (79)
(79) The carryover period for the NOLs of a C corporation continues to run during S corporation years.
(True/False)
4.9/5 (80)
(80) To make a valid S election,the entity must file a properly completed Form ____________________.
(Short Answer)
5.0/5 (84)
(84) A capital loss allocated to a shareholder always reduces the Other Adjustments Account.
(True/False)
4.7/5 (82)
(82) As a general rule,S corporation treatment is not advantageous when the individual tax rate far exceeds the applicable corporate tax rate.
(True/False)
4.9/5 (70)
(70) Distribution of appreciated property is taxable to an S corporation.
(True/False)
4.9/5 (74)
(74) If an S corporation shareholder's basis in a loan to the entity has been _________________,the shareholder recognizes gross income when the S corporation repays the shareholder.
(Short Answer)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)