



 Chat with AI
Exam 3: Corporations: Special Situations


During 2012,Gold Corporation (a calendar year taxpayer)has $3,500,000 of taxable income and the following transactions:  Gold Corporation's alternative minimum tax (AMT)for 2012 is:
 (81)
 Verified
C
Why is the DPAD benefit somewhat unique?
(98) VerifiedThe domestic production activities deduction (DPAD)is designed to provide a tax benefit in a somewhat unique manner.Unlike other deductions,DPAD is not the result of a direct expenditure or other outlay.Instead,it is a deduction based on the net income earned from a specified source.A manufacturing concern,therefore,will determine its DPAD not on the cost of production but on the profit from the sale of the item produced.Thus,DPAD is a deduction based on income!
How is DPAD handled in an S corporation or a partnership situation?
(74) VerifiedIn the case of a pass-through entity,such as an S corporation or partnership,special rules apply for handling DPADs.Thus,because the deduction is determined at the owner level,each partner or shareholder must make the computation separately.Thus,the entity allocates to each owner his or her share of QPAI.The QPAI allocated is then combined with the domestic production activities the owner may have from other sources (e.g. ,a partner also conducts a manufacturing activity of his or her own).
In working with the wage limitation in a pass-through setting,an allocable portion of W-2 wages of the pass-through entity is passed through to the owner,but only those wages properly allocable to DPGR.The partner or shareholder,however,may add any wages separately paid to the amount allocated from the entity.In the case of a partnership,guaranteed payments are not regarded as W-2 wages.Also,if QPAI (computed taking into account only partnership items allocated to the partner for the tax year)is not greater than zero,a partner cannot use any partnership W-2 wages in calculating the DPAD.
Generally,the DPAD is determined at the owner level in a pass-through entity situation.In some instances,however,the pass-through of the data needed to make this determination can be cumbersome and burdensome.To simplify matters,therefore,the IRS allows eligible partnerships and S corporations to calculate QPAI and W-2 wages for some or all of the owners at the entity level.
Macon Corporation manufactures an exercise machine at a cost of $800 and sells the machine to Kershaw Corporation for $1,000 in 2012.Kershaw incurs TV advertising expenses of $300 and sells the machine by phone order for $1,500.If Macon and Kershaw corporations are members of an expanded affiliated group (EAG),their DPGR is:
(70) Some of the meals a food service company prepares for its chain of restaurants is frozen and shipped to supermarkets for resale.The proceeds from such sales will qualify as DPGR.
(77) Trahan,Inc. ,an S corporation,has taxable income of $12 million in 2012.Assume there are two shareholders,each in the top individual tax bracket.What is the maximum total DPAD tax savings for the S corporation shareholders?
(79) Maroon Corporation incurred the following taxes for the year 2012: 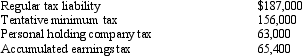 Maroon Corporation's total tax liability is:
 (76) A sole proprietor shows the DPAD as a deduction for adjusted gross income (DFOR)on Form 1040.
(68) Blue,Inc. ,a calendar year closely held corporation,is not a PHC.If the company reports the following items,the accumulated taxable income is: 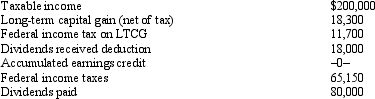
(85) In connection with the construction of a housing project,a contractor pays an architect to design the homes being built.The architect's fee is an embedded service that qualifies as DPGR.
(71) a. Calculate the personal holding company tax in 2012 based upon the following information.
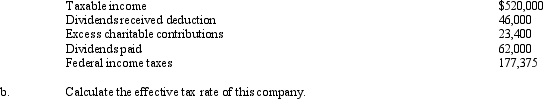
(79) In working with the W-2 wage limitation on DPAD,a partner can count any guaranteed payments he receives from the partnership.
(77) The lower a taxpayer's W-2 wages,the less the potential DPAD amount.
(91) The accumulated earnings credit is always the greater of the minimum credit of $250,000 or the current E & P for the year needed to meet the reasonable needs of the business.
(73) The ACE adjustment applies to business entities other than corporations.
(77) Nontaxable dividend payments reduce both ATI and undistributed PHCI.
(81) The regular foreign tax credit is available to reduce AMT liability.
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)