



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


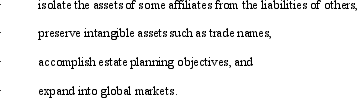
List some of the non-tax reasons that groups of corporations form conglomerates and may be eligible also to file consolidated Federal income tax returns.

Free
(Essay)
4.8/5  (76)
(76) Correct Answer: Verified
Conglomerates are formed to reduce overall tax liabilities,but also to:
A penalty can be assessed by the IRS if the parent corporation does not keep good records to support the computation of a subsidiary's stock basis.
Free
(True/False)
4.9/5 (82)
(82) Correct Answer:Verified
VerifiedTrue
With the filing of its first consolidated return,the parent corporation of a Federal consolidated group makes an irrevocable election as to how the group will allocate a tax year's income tax liability among the group members.
Free
(True/False)
4.9/5 (80)
(80) Correct Answer:Verified
VerifiedFalse
Consider AB,a brother-sister group of U.S.corporations,and CD,a parent-subsidiary group of U.S.corporations.Which of these could comprise a controlled group? An affiliated group?
(Essay)
4.9/5 (70)
(70) If there is a balance in the excess loss account when a subsidiary's stock is sold,the balance is recognized as ____________________ gain/income.
(Short Answer)
4.8/5 (99)
(99) When a member departs a consolidated group,it forfeits the use of any NOLs it generated while in the group.
(True/False)
4.7/5 (94)
(94) The "SRLY" and § 382 limitation rules for Federal consolidated tax returns are designed to keep corporations from "trafficking" their net operating losses.These rules are restrictive and somewhat complex.Explain why these rules exist,and how they interact if both apply in the same tax year.
(Essay)
4.7/5 (76)
(76) ParentCo purchased 100% of SubCo's stock on January 1,2012,and the companies have filed consolidated returns since then.Taxable income computations for the members include the following.Neither group member incurred any capital gain or loss transactions during these years,nor did they make any charitable contributions. 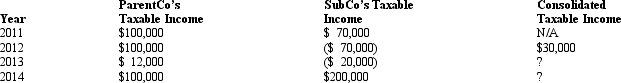 The 2013 net operating loss:
 (Multiple Choice)
4.9/5 (90)
(90) ParentCo and SubCo had the following items of income and deduction for the current year. 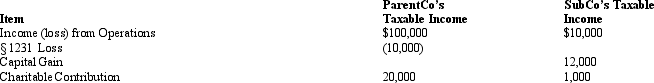 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo (Multiple Choice)
4.8/5 (76)
(76) The calendar year Sterling Group files its Federal corporate income tax return on a consolidated basis.The group's Form 1120 is due on March 15,or September 15 if an extended due date is approved by the IRS.
(True/False)
4.8/5 (86)
(86) ParentCo's separate taxable income was $200,000,and SubCo's was $50,000.Consolidated taxable income before contributions was $200,000.Charitable contributions made by the affiliated group included $60,000 by ParentCo and $10,000 by SubCo.Compute the group's maximum charitable contribution deduction.
(Multiple Choice)
4.8/5 (74)
(74) A subsidiary corporation must leave the consolidated group if it is restructured as an LLC.
(True/False)
4.9/5 (78)
(78) ParentCo and SubCo had the following items of income and deduction for the current year. 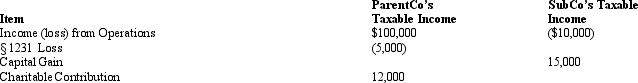 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo (Multiple Choice)
4.8/5 (85)
(85) The rules for computing Federal consolidated taxable income are some of the most complex in the tax law.
(True/False)
4.8/5 (86)
(86) In a Federal consolidated tax return group,who is responsible to pay the tax liability-the parent,the subsidiaries,or both? How are these tax-payable amounts determined?
(Essay)
4.8/5 (81)
(81) Discuss how a parent corporation computes its stock basis for a subsidiary that joins in a Federal consolidated income tax return.
(Essay)
4.8/5 (76)
(76) A consolidated Federal income tax return may be the product of a merger of the affiliates,or of some other tax-favored reorganization.
(True/False)
4.9/5 (81)
(81) In an affiliated group,the parent must own at least 80% of each of the subsidiaries.
(True/False)
4.7/5 (82)
(82) Members of the ABCD Federal consolidated group conduct various transactions with each other during the tax year.These include the purchase/sale of land and depreciable assets,the licensing of intangible assets,and the conduct of service arrangements.How does the tax law account for these intercompany items? In your answer,be sure to use the terms matching rule and acceleration rule at least once each.
(Essay)
4.9/5 (71)
(71) Cooper Corporation joined the Duck consolidated Federal income tax return group,when Cooper held a $1 million NOL carryforward.In its first year as a part of the Duck group,Cooper generated a $150,000 operating profit.For that year,Duck can deduct only $150,000 of Cooper's NOL in computing consolidated taxable income.
(True/False)
4.7/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)