



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


SubCo sells an asset to ParentCo at a realized gain.While ParentCo still holds the asset,SubCo leaves the consolidated group.As a result:
(Multiple Choice)
5.0/5  (79)
(79) Which of the following items is not computed on a consolidated basis?
(Multiple Choice)
4.9/5 (87)
(87) Business reasons,and not tax incentives,constitute the primary motivation for most corporations to form a conglomerate and file tax and financial accounting reports on a consolidated basis.
(True/False)
4.7/5 (73)
(73) When an affiliated group elects to file Federal consolidated income tax returns,it gives up the ability to claim a ____________________ deduction for distributions of profits paid to other members.
(Short Answer)
4.9/5 (85)
(85) ParentCo and SubCo had the following items of income and deduction for the current year. 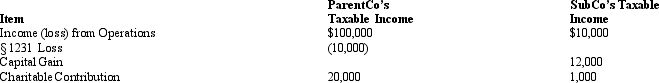 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.9/5 (75)
(75) Calendar year Parent Corporation acquired all of the stock of SubCo on January 1,Year 1,for $400,000.The subsidiary's operating gains and losses are shown below.In addition,a $30,000 dividend is paid early in Year 2.
Complete the following chart,indicating the appropriate stock basis and excess loss account amounts.
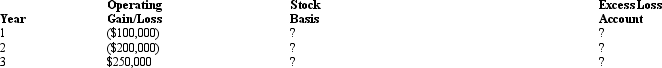
(Essay)
4.9/5 (91)
(91) All affiliates joining in a newly formed consolidated return must consent to the election on Form 1122,as attached to the tax return for the group.
(True/False)
5.0/5 (72)
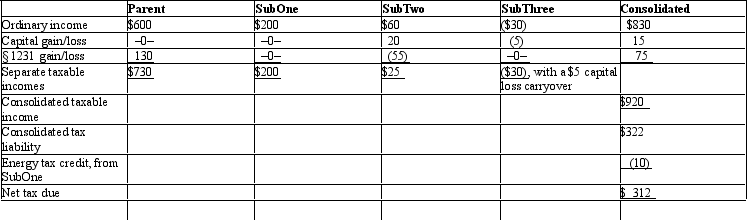
(72) The Parent consolidated group reports the following results for the tax year.Determine each member's share of the consolidated tax liability,assuming that the members all have consented to use the relative tax liability tax-sharing method.Dollar amounts are listed in millions,and a 35% marginal income tax rate applies to all of the entities.
(Essay)
4.7/5 (77)
(77) When a consolidated NOL is generated,each affiliate is allocated a share of the loss.
(True/False)
4.8/5 (85)
(85) The losses of a consolidated group member are subject to both the SRLY rules and a § 382 limitation.When both limitations apply,the SRLY rules override the § 382 restrictions for this affiliate.
(True/False)
5.0/5 (94)
(94) SubCo sells an asset to ParentCo at a realized loss.That loss is not recognized by the group in the year of the sale,because of the:
(Multiple Choice)
4.7/5 (67)
(67) Conformity among the members of a consolidated group must be implemented for which of the following tax items?
(Multiple Choice)
4.7/5 (72)
(72) If subsidiary stock is redeemed or sold outside the group when an excess loss account exists,the selling parent corporation recognizes capital gain income equal to the account balance.
(True/False)
4.9/5 (70)
(70) To be part of a Federal consolidated return,an entity cannot be ineligible to join an affiliated group.List three or more business entities that cannot be part of a Federal consolidated tax return group.
(Essay)
4.9/5 (64)
(64) ParentCo owned 100% of SubCo for the entire year,and both companies use the accrual method of tax accounting.During the year,SubCo purchased $20,000 of supplies from ParentCo.In addition,SubCo provided internal audit services to ParentCo,which were worth $40,000.Including these transactions,ParentCo's separate taxable income was $75,000,and SubCo's separate taxable income was $100,000.What is the group's consolidated taxable income for the year?
(Multiple Choice)
4.8/5 (88)
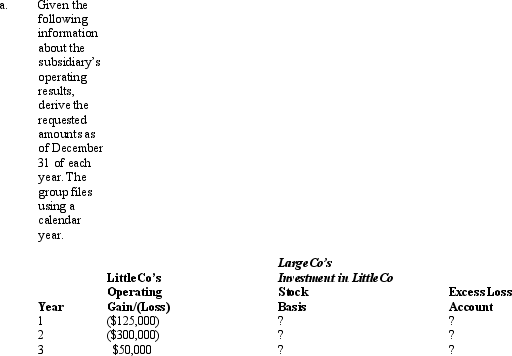
(88) LargeCo files on a consolidated basis with LittleCo.The subsidiary was acquired for $400,000 on January 1,Year 1,and it paid a $75,000 dividend to LargeCo at the end of both Year 2 and Year 3.
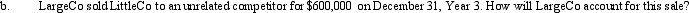
(Essay)
4.9/5 (88)
(88) How are the members of a Federal consolidated group affected by computations related to E & P?
(Multiple Choice)
4.9/5 (71)
(71) Which of the following statements is true with regard to intercompany transactions?
(Multiple Choice)
4.8/5 (66)
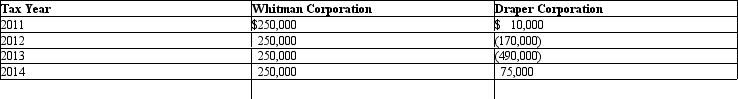
(66) Compute consolidated taxable income for the calendar year Whitman Group,which elected consolidated status immediately upon creation of the two member corporations in January 2011.All recognized income related to the data processing services of the firms.No intercompany transactions were completed during the indicated years.
(Essay)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)