



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


ParentCo and SubCo had the following items of income and deduction for the current year. 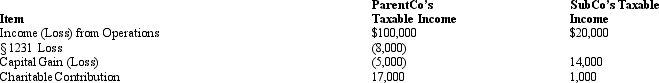 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.9/5  (80)
(80) When the parent acquires 51% of a subsidiary U.S.corporation,the subsidiary can join the consolidated financial statements,but not the consolidated tax return of the parent.
(True/False)
4.8/5 (82)
(82) ParentCo purchased all of the stock of ChildCo on January 2,2012,and the two companies filed consolidated returns for 2012 and thereafter.Both entities were incorporated in 2011.Taxable income computations for the members include the following.Neither group member incurred any capital gain or loss transactions during these years,nor did they make any charitable contributions.No § 382 limit applies. 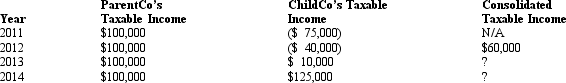 To what extent can ChildCo's 2011 losses be used by the group in 2014?
 (Multiple Choice)
4.8/5 (78)
(78) Calendar year ParentCo acquired all of the stock of SubCo on January 1,2012,for $1,000,000.The parties immediately elected to file consolidated income tax returns.SubCo generated taxable income of $150,000 for 2012 and paid a dividend of $100,000 to ParentCo.In 2013,SubCo generated an operating loss of $350,000,and in 2014 it produced taxable income of $75,000.As of the last day of 2014,what was ParentCo's basis in the stock of SubCo?
(Multiple Choice)
4.7/5 (84)
(84) Which of the following entities is eligible to file Federal income tax returns on a consolidated basis?
(Multiple Choice)
4.9/5 (92)
(92) Deferring recognition of an intercompany loss is one ____________________ (advantage/disadvantage)of electing to file consolidated returns.
(Short Answer)
4.8/5 (81)
(81) An example of an intercompany transaction is the use of the financial accounting software of the parent corporation by a subsidiary for an arm's length management fee.
(True/False)
4.9/5 (81)
(81) Calendar year ParentCo purchased all of the stock of SubCo on January 1,2012,for $500,000.SubCo produced a loss for 2012 of $150,000 and distributed cash of $25,000 to ParentCo.In 2013,SubCo generated a loss of $450,000;in 2014,it recognized net income of $45,000.What is ParentCo's capital gain or loss if it sells all of its SubCo stock to a nongroup member on January 1,2015,for $50,000?
(Multiple Choice)
4.9/5 (82)
(82) In computing consolidated E & P,a negative adjustment is allowed for the group's Federal income tax payments.
(True/False)
4.8/5 (84)
(84) When excessive negative adjustments are made to the stock basis of the subsidiary,a(n)____________________ account is created,rather than giving the parent a negative tax basis in the stock.
(Short Answer)
4.9/5 (84)
(84) Which of the following potentially is a disadvantage of electing to file a Federal consolidated corporate income tax return?
(Multiple Choice)
4.9/5 (82)
(82) ParentCo owned 100% of SubCo for the entire year.ParentCo uses the accrual method of tax accounting,whereas SubCo uses the cash method.During the year,SubCo sold raw materials to ParentCo for $35,000 under a contract that requires no payment to SubCo until the following year. Exclusive of this transaction,ParentCo had income for the year of $30,000,and SubCo had income of $50,000.The group's consolidated taxable income for the year was:
(Multiple Choice)
4.8/5 (87)
(87) All members of an affiliated group have ____________________ and ____________________ liability for each other's Federal income tax liabilities.
or
(Short Answer)
4.8/5 (70)
(70) Consolidated group members each must use the same tax year end.
(True/False)
4.7/5 (74)
(74) ParentCo and SubOne have filed consolidated returns since 2010.SubTwo was formed in 2012 through an asset spin-off from ParentCo.SubTwo has joined in the filing of consolidated returns since then.Taxable income computations for the members include the following.None of the group members incurred any capital gain or loss transactions during these years,nor did they make any charitable contributions. 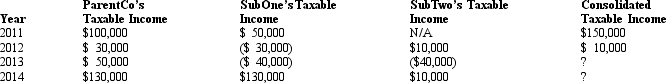 If ParentCo does not elect to forgo the carryback of the 2013 net operating loss,how much of the 2013 consolidated net operating loss is carried back to offset prior years' income?
 (Multiple Choice)
4.8/5 (77)
(77) When both apply,the § 382 NOL limitation rules override the ____________________ limits.
or
(Short Answer)
4.9/5 (77)
(77) Parent's basis in the stock of Child,its subsidiary,is $1 million at the beginning of the year.Child's share of consolidated taxable income this year is a $1.25 million operating loss.Parent's basis in the Child stock now is zero.Explain.
(Essay)
4.8/5 (84)
(84) A parent-subsidiary controlled group exists where there is ____________________ percent ownership of all of the affiliates within the group,and there is an identifiable ____________________ corporation.
or
(Short Answer)
4.8/5 (79)
(79) ParentCo and SubCo had the following items of income and deduction for the current year. 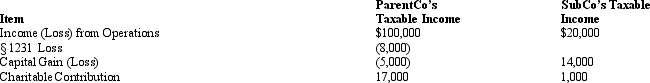 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo (Multiple Choice)
4.8/5 (68)
(68) Which of the following is not a requirement that must be met before a group files a consolidated return?
(Multiple Choice)
4.7/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)