



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


Compare the distribution of property rules for an S corporation with the corresponding partnership rules.
(Essay)
4.8/5  (80)
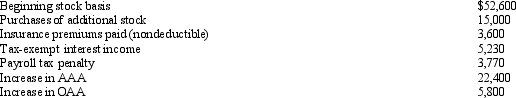
(80) You are a 60% owner of an S corporation.Calculate your ending stock basis,based upon these facts.
(Essay)
4.9/5 (80)
(80) Individuals Adam and Bonnie form an S corporation,with Adam contributing cash of $100,000 for a 50% interest and Bonnie contributing appreciated ordinary income property with an adjusted basis of $20,000 and a fair market value of $100,000.
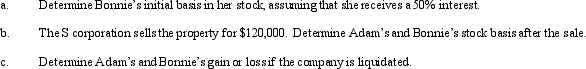
(Essay)
4.9/5 (80)
(80) Four unrelated individuals acquire assets on behalf of Jump Corporation on May 21,2012,purchased assets on June 5,2012,and begin doing business on June 15,2012.They subscribe to shares of stock,file articles of incorporation for Jump,and become shareholders on July 23,2012.The S election must be filed no later than 2 1/2 months after:
(Multiple Choice)
4.8/5 (84)
(84) Depletion in excess of basis in property causes a(n)____________________ adjustment to an S shareholder's basis.
or
(Short Answer)
4.9/5 (72)
(72) During 2012,Oxen Corporation incurs the following transactions.  Oxen maintains a valid S election and does not distribute any assets (cash or property)to its sole shareholder,Megan.As a result,Megan must recognize:
 (Multiple Choice)
5.0/5 (81)
(81) Which,if any,of the following can be an eligible shareholder of an S corporation?
(Multiple Choice)
4.8/5 (81)
(81) Any excess of S corporation losses or deductions over the shareholder's combined stock and debt basis is suspended until there is a subsequent stock or debt basis.
(True/False)
4.9/5 (79)
(79) S corporation status allows shareholders to realize tax benefits from corporate losses ____________________.
(Short Answer)
4.9/5 (88)
(88) Which type of distribution from an S corporation is taxed at the 0/15% Federal income tax rate?
(Multiple Choice)
4.8/5 (81)
(81) Shareholders may deduct losses in excess of their basis in S corporation stock when a shareholder holds a loan basis of zero.
(True/False)
4.8/5 (69)
(69) Meeting the definition of a small business corporation is a ____________________ requirement for maintaining the S status.
(Short Answer)
5.0/5 (78)
(78) Consent to an S election must be in ____________________,and it must be generally filed by the election ____________________.
(Short Answer)
4.9/5 (92)
(92) An S election made before becoming a corporation is valid only beginning with the first 12-month tax year.
(True/False)
4.7/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)