



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


An S corporation reports a recognized built-in gain of $110,000 and taxable income of $98,000.The company has an $8,000 NOL carryforward from a C corporation year,and a $7,000 business credit carryforward from a C corporation year.The built-in gains tax liability is:
(Multiple Choice)
4.9/5  (91)
(91) On January 2,2011,David loans his S corporation $10,000,and by the end of 2011 David's stock basis is zero and the basis in his note has been reduced to $8,000.During 2012,the company's operating income is $10,000.The company also makes distributions to David of $11,000.David reports a(n):
(Multiple Choice)
4.8/5 (74)
(74) Compensation for services rendered to an S corporation is subject to FICA taxes.
(True/False)
5.0/5 (83)
(83) An S corporation shareholder's basis includes his or her direct investments plus a ratable share of any corporate liabilities.
(True/False)
4.8/5 (78)
(78) On January 1,2012,Zundel,Inc. ,an electing S corporation,has $4,000 of AEP and a balance of $10,000 in AAA.Zundel has two shareholders,Erin and Maine,each of whom owns 500 shares of Zundel's stock.Zundel's 2012 taxable income is $5,000.Zundel distributes $6,000 to each shareholder on February 1,2012,and distributes another $3,000 to each shareholder on September 1.How is Erin taxed on this distribution?
(Multiple Choice)
4.8/5 (84)
(84) Form 1120S provides a shareholder's computation of his or her stock basis.
(True/False)
4.7/5 (86)
(86) A calendar year C corporation reports a $41,000 NOL in 2011,but it elects S status for 2012 and generates an NOL of $30,000 in that year.At all times during 2012,the stock of the corporation was owned by the same 10 shareholders,each of whom owned 10% of the stock.Kris,one of the 10 shareholders,holds an S stock basis of $2,300 at the beginning of 2012.How much of the 2012 loss,if any,is deductible by Kris?
(Multiple Choice)
4.8/5 (76)
(76) Grams,Inc. ,a calendar year S corporation,reports $20,000 DPGR and $15,000 of wages,and the S corporation's QPAI is $5,000.Janet has a 40% interest in the S corporation.All expenses that reduce DPGR are from wages,and all wages paid relate to DPGR.How much QPAI and wages are allocated to Janet?
(Multiple Choice)
4.8/5 (74)
(74) When an S corporation liquidates,which of its tax attributes disappear?
(Multiple Choice)
4.9/5 (72)
(72) Distribution of loss property by an S corporation to a shareholder generally should be _________________.
(Short Answer)
4.9/5 (79)
(79) For Federal income tax purposes,taxation of S corporations resembles that of partnerships.
(True/False)
4.8/5 (84)
(84) With respect to passive losses,there are three classes of income,losses,and credits: ____________________,____________________,and passive.
or
(Short Answer)
4.9/5 (82)
(82) An S corporation's separately stated items generally are identical to those separately stated by _________________________.
(Short Answer)
4.9/5 (74)
(74) Non-separately computed loss ____________________ a S shareholder's stock basis.
(Short Answer)
4.8/5 (83)
(83) You are given the following facts about a 40% owner of an S corporation,and you are asked to prepare her ending stock basis. 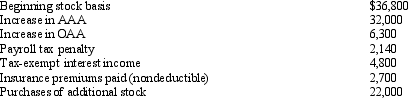
(Multiple Choice)
4.8/5 (83)
(83) Which equity arrangement cannot be used by an S corporation?
(Multiple Choice)
5.0/5 (69)
(69) Post-termination distributions that are charged against OAA are received tax-free.
(True/False)
5.0/5 (63)
(63) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)