



 Chat with AI
Exam 23: Exempt Entities

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Hope, Inc., an exempt organization, owns a factory building that it leases to a taxable corporation for $160,000 per year.Related expenses for Hope are $40,000.Hope's average acquisition indebtedness on the building is $600,000 and the average adjusted basis is $800,000.Calculate Hope's unrelated debt-financed income and expenses.Then indicate the effect of these items on unrelated business taxable income.
(Essay)
4.8/5  (79)
(79) Miracle, Inc., is a § 501(c)(3) organization involved in medical research.Based on its expectation that proposed legislation will adversely affect the funding supporting its mission, Miracle hires a lobbyist to work in Washington to represent its views.
(Essay)
4.9/5 (76)
(76) The general objective of the tax on unrelated business income is to tax such income as if the entity were a taxable corporation.
(True/False)
4.8/5 (74)
(74) Which exempt organizations are not required to file an annual Federal tax return?
(Essay)
4.8/5 (77)
(77) Even though a church is exempt under § 501(c)(3), it is required to obtain IRS approval for its exempt status.
(True/False)
4.9/5 (90)
(90) One of the requirements for an exempt organization being classified as an unrelated trade or business is the "not substantially related" requirement.That is, the trade or business is not substantially related to the exempt purpose of the organization.How can an exempt organization avoid satisfying this requirement?
(Essay)
4.9/5 (87)
(87) Revenue generated by an exempt organization from the distribution of low-cost items is not income from an unrelated trade or business.
(True/False)
4.9/5 (82)
(82) Acquisition indebtedness consists of the unpaid amounts of which of the following for debt-financed property?
(Multiple Choice)
4.7/5 (76)
(76) Personal property rental income is subject to and real property rental income is not subject to the unrelated business income tax.
(True/False)
5.0/5 (92)
(92) Under what circumstances are bingo games not treated as an unrelated trade or business?
(Essay)
4.8/5 (77)
(77) If personal property is leased with real property and more than 45% of the rent income under the lease is from personal property, all of the rent income is subject to the unrelated business income tax.
(True/False)
4.8/5 (75)
(75) In calculating unrelated business taxable income, the exempt organization is permitted to deduct only the charitable contributions associated with the unrelated trade or business.
(True/False)
4.7/5 (67)
(67) Define "trade or business" for purposes of the unrelated business income tax (UBIT).
(Essay)
4.9/5 (75)
(75) An exempt organization that otherwise would be classified as an unrelated trade or businesses will not be subject to the unrelated business income tax if the individuals performing substantially all the work of the trade or business do so without compensation.
(True/False)
4.9/5 (85)
(85) The due date for both Form 990 (Return of Organization Exempt from Income Tax) and Form 990-PF (Return of Private Foundation) is the fifteenth day of the fourth month after the end of the taxable year.
(True/False)
4.9/5 (76)
(76) An exempt organization owns a building for which its adjusted basis is $100,000 at the beginning of the year and $90,000 at the end of the year.One-half of the ground floor is leased to a commercial venture for $10,000 per year.The remainder of the first floor and all of the second floor are used by the exempt organization in carrying out its mission.When the exempt organization constructed the building 20 years ago, it incurred a mortgage of $150,000.The final payment of this mortgage was made in December of the current year.The average acquisition indebtedness for the current year is $30,000.Determine to what extent the building is debt-financed property, the amount of debt-financed income, and the portion of debt-financed income that is treated as unrelated business income.
(Essay)
4.8/5 (80)
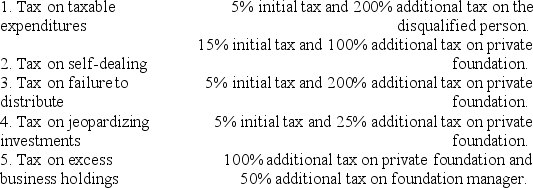
(80) For each of the following taxes which are imposed on private foundations, match the appropriate initial tax or additional tax.
(Essay)
4.8/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)