



 Chat with AI
Exam 7: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Choices and Trade-Offs in the Market192 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply241 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply224 Questions
Exam 5: Economic Efficiency,government Price Setting and Taxes169 Questions
Exam 6: Technology,production and Costs255 Questions
Exam 7: Firms in Perfectly Competitive Markets269 Questions
Exam 8: Monopoly Markets187 Questions
Exam 9: Monopolistic Competition and Oligopoly350 Questions
Exam 10: The Markets for Labour and Other Factors of Production250 Questions
Exam 11: Government Intervention in the Market325 Questions
Exam 12: Social Policy and Inequality125 Questions
Exam 13: Gdp: Measuring Total Production, income and Economic Growth202 Questions
Exam 14: Unemployment and Inflation230 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis166 Questions
Exam 16: Money,banks and the Reserve Bank of Australia110 Questions
Exam 17: Monetary Policy111 Questions
Exam 18: Fiscal Policy138 Questions
Exam 19: Comparative Advantage and the Gains From International Trade131 Questions
Exam 20: Macroeconomics in an Open Economy276 Questions
Select questions type


Figure 7.16 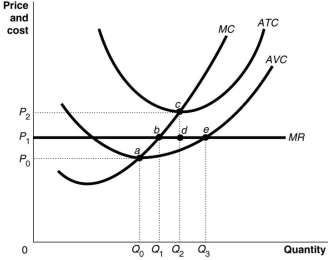 -Refer to Figure 7.16.If the market price is P1,the allocatively efficient output level is -.
 (Multiple Choice)
4.7/5  (87)
(87) Figure 7.9  -Refer to Figure 7.9.If this is a constant-cost industry,the market price in the long-run equilibrium is -.
 (Multiple Choice)
4.9/5 (78)
(78) If a perfectly competitive firm's total revenue is less than its total variable cost,the firm
(Multiple Choice)
4.8/5 (76)
(76) Figure 7.4  Figure 7.4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7.4.If the market price is $30 and if the firm is producing output,the amount of its total variable cost is -.
Figure 7.4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7.4.If the market price is $30 and if the firm is producing output,the amount of its total variable cost is -. (Multiple Choice)
4.8/5 (65)
(65) What demand curve is faced by a perfectly competitive firm?
(Multiple Choice)
4.9/5 (83)
(83) Assuming a market price of $4,fill in the columns in the following table.What is the profit-maximising level of production? What are the two ways to determine the profit-maximising level of production?
Total Total Marginal Quantity Revenue (TR) Cost (TC) Profit Revenue (MR) Marginal 0 3 1 5 2 6 3 9 4 14 5 20 6 28 7 40 __________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
4.9/5 (73)
(73) Table 7.3
Quantity Total Cost Total Cost Marginal 0 \ 10.00 ---- ---- 1 15.00 \ 15.00 \ 5.00 2 17.50 8.75 2.50 3 22.50 7.50 5.00 4 30.00 7.50 7.50 5 40.00 8.00 10.00 6 52.50 8.75 12.50 7 67.50 9.64 15.00 8 85.00 10.63 17.50 9 105.00 11.67 20.00 Arnie sells basketballs in a perfectly competitive market. Table 7.3 summarises Arnie's output per day (Q), total cost (TC), average total cost (ATC), and marginal cost (MC).
-Refer to Table 7.3.What price (P)will Arnie charge and how much profit will he earn if the market price of basketballs is $12.50?
(Multiple Choice)
4.9/5 (80)
(80) Figure 7.6  -Refer to Figure 7.6.Suppose the firm produces 4000 units.The shaded area labelled A represents
 (Multiple Choice)
4.8/5 (83)
(83) A perfectly competitive wheat farmer in a constant-cost industry produces 3000 bushels of wheat at a total cost of $36 000.The prevailing market price is $15.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.8/5 (81)
(81) The long-run supply curve for a perfectly competitive,constant-cost industry
(Multiple Choice)
4.8/5 (82)
(82) The price a perfectly competitive firm receives for its output
(Multiple Choice)
4.8/5 (78)
(78) Figure 7.4 Figure 7.4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7.4.Assuming the firm is profit maximising,the amount of its total fixed cost is -.
Figure 7.4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7.4.Assuming the firm is profit maximising,the amount of its total fixed cost is -. (Multiple Choice)
5.0/5 (71)
(71) Figure 7.2  -Refer to Figure 7.2.What happens if the firm produces more than Q4 units?
 (Multiple Choice)
5.0/5 (88)
(88) Suppose the equilibrium price in a perfectly competitive industry is $10 and a firm in the industry charges $12.Which of the following will happen?
(Multiple Choice)
4.8/5 (79)
(79) A perfectly competitive industry achieves allocative efficiency because
(Multiple Choice)
4.7/5 (72)
(72) Which of the following characteristics of a farmers' market make it a good example of a perfectly competitive market?
(Multiple Choice)
4.8/5 (97)
(97) Figure 7.7  Figure 7.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 7.7.At price P1,the firm would produce
Figure 7.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 7.7.At price P1,the firm would produce (Multiple Choice)
4.8/5 (83)
(83) Why are both buyers and sellers price takers in a perfectly competitive market?
(Multiple Choice)
4.9/5 (69)
(69) Which of the following describes a situation in which a good or service is produced at the lowest possible cost?
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)