



 Chat with AI
Exam 7: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Choices and Trade-Offs in the Market192 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply241 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply224 Questions
Exam 5: Economic Efficiency,government Price Setting and Taxes169 Questions
Exam 6: Technology,production and Costs255 Questions
Exam 7: Firms in Perfectly Competitive Markets269 Questions
Exam 8: Monopoly Markets187 Questions
Exam 9: Monopolistic Competition and Oligopoly350 Questions
Exam 10: The Markets for Labour and Other Factors of Production250 Questions
Exam 11: Government Intervention in the Market325 Questions
Exam 12: Social Policy and Inequality125 Questions
Exam 13: Gdp: Measuring Total Production, income and Economic Growth202 Questions
Exam 14: Unemployment and Inflation230 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis166 Questions
Exam 16: Money,banks and the Reserve Bank of Australia110 Questions
Exam 17: Monetary Policy111 Questions
Exam 18: Fiscal Policy138 Questions
Exam 19: Comparative Advantage and the Gains From International Trade131 Questions
Exam 20: Macroeconomics in an Open Economy276 Questions
Select questions type


Ted's Pancake Kitchen suffers a short-run loss.Ted should decide to shut down rather than continue to produce
(Multiple Choice)
5.0/5  (83)
(83) Which of the following is not an assumption of perfectly competitive markets?
(Multiple Choice)
4.7/5 (91)
(91) In long-run competitive equilibrium,the perfectly competitive firm produces where price equals minimum average total cost.
a.What is this efficiency criterion called?
b.How does it benefit consumers?
__________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
4.9/5 (73)
(73) By what is the price of a seller's product in perfect competition determined?
(Multiple Choice)
4.9/5 (88)
(88) Competition has driven the economic profits in the video rental business to zero.Surya Bacha,who owns a video rental business,would be better off leaving the industry for another alternative.
(True/False)
4.9/5 (73)
(73) Table 7.4
Quantity Average Fixed Cost Average Variable Cost Marginal Cost 20 \ 40 \ 18 \ 18 40 20 14 10 60 13.1 16 20 80 10 22 40 100 8 30 62 120 6.61 40 90 Table 7.4 shows the short-run cost data of a perfectly competitive firm. Assume that output can only be increased in batches of 20 units.
-Refer to Table 7.4.If the market price is $45,the firm
(Multiple Choice)
4.9/5 (94)
(94) A perfectly competitive firm's marginal revenue curve is downward sloping.
(True/False)
4.7/5 (79)
(79) A perfectly competitive firm will maximise its profit at the rate of output where the vertical distance between its total revenue and total cost is the largest.This is the same rate of output where
(Multiple Choice)
4.9/5 (71)
(71) To what does the term 'price taker' apply in a perfectly competitive market?
(Multiple Choice)
4.9/5 (78)
(78) A perfectly competitive wheat farmer in a constant-cost industry produces 1000 bushels of wheat at a total cost of $50 000.The prevailing market price is $48.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.8/5 (77)
(77) If,for the last bushel of apples produced and sold by an apple farm,marginal revenue exceeds marginal cost,then in producing that bushel the farm
(Multiple Choice)
4.8/5 (91)
(91) In early 2007,Pioneer and JVC,two Japanese electronics firms,each announced that their profits were going to be lower than expected because they both had to cut prices for LCD and plasma television sets.Which of the following could explain why these firms did not simply raise their prices and increase their profits?
(Multiple Choice)
4.9/5 (88)
(88) Figure 7.7  Figure 7.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 7.7.At price P2,the firm would produce
Figure 7.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 7.7.At price P2,the firm would produce (Multiple Choice)
4.9/5 (82)
(82) Letters are used to represent the terms used to answer this question: price (P),quantity of output (Q),total cost (TC),and average total cost (ATC).Which of the following equations is equal to a firm's profit?
(Multiple Choice)
5.0/5 (83)
(83) In the short run,a firm that incurs losses might choose to produce rather than shut down if the amount of its revenue is less than its fixed cost.
(True/False)
4.9/5 (78)
(78) In analysing the decision to shut down in the short run,we assume that the firm's fixed costs are
(Multiple Choice)
4.8/5 (79)
(79) Figure 7.10 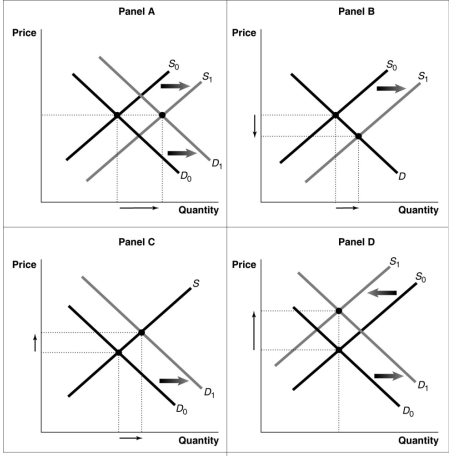 -Refer to Figure 7.10.Consider a typical firm in a perfectly competitive industry that makes short-run profits.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (67)
(67) Figure 7.7 Figure 7.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 7.7.Identify the firm's short-run supply curve.
Figure 7.7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 7.7.Identify the firm's short-run supply curve. (Multiple Choice)
4.9/5 (72)
(72) If a firm's fixed cost exceeds its total revenue,the firm should stop production by shutting down temporarily.
(True/False)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)