



 Chat with AI
Exam 5: Adjustments and the Worksheet

Exam 1: Accounting: The Language of Business84 Questions
Exam 2: Analyzing Business Transactions100 Questions
Exam 3: Analyzing Business Transactions Using T Accounts116 Questions
Exam 4: The General Journal and the General Ledger98 Questions
Exam 5: Adjustments and the Worksheet97 Questions
Exam 6: Closing Entries and Teh Postclosing Trial Balance97 Questions
Exam 7: Accounting for Sales and Accounts Receivable99 Questions
Exam 8: Accounting for Purchases and Accounts Payable111 Questions
Exam 9: Cash Receipts, Cash Payments, and Banking Procedures92 Questions
Exam 10: Payroll Computations, Records, and Payment89 Questions
Exam 11: Payroll Taxes, Deposits, and Reports88 Questions
Exam 12: Accruals, Deferrals, and the Worksheet94 Questions
Exam 13: Financial Statements and Closing Procedures92 Questions
Exam 14: Accounting Principles and Reporting Standards95 Questions
Exam 15: Accounts Receivable and Uncollectible Accounts93 Questions
Exam 16: Notes Payable and Notes Receivable101 Questions
Exam 17: Merchandise Inventory114 Questions
Exam 18: Property, Plant, and Equipment123 Questions
Exam 19: Accounting for Partnerships118 Questions
Exam 20: Corporations: Formation and Capital Stock Transactions104 Questions
Exam 21: Corporate Earnings and Capital Transactions118 Questions
Exam 22: Long-Term Bonds114 Questions
Exam 23: Financial Statement Analysis131 Questions
Exam 24: The Statement of Cash Flows154 Questions
Exam 25: Departmentalized Profit and Cost Centers121 Questions
Exam 26: Accounting for Manufacturing Activities114 Questions
Exam 27: Job Order Cost Accounting111 Questions
Exam 28: Process Cost Accounting99 Questions
Exam 29: Controlling Manufacturing Costs: Standard Costs126 Questions
Exam 30: Cost-Revenue Analysis for Decision Making126 Questions
Select questions type


The process of updating accounts at the end of an accounting period for previously unrecorded items that belong to the period is referred to as making ________.
(Short Answer)
4.9/5  (73)
(73) A consecutive, twelve-month accounting period is called a(n):
(Multiple Choice)
4.9/5 (81)
(81) On January 1, ABC Catering purchased an oven for $5,000. The oven is expected to last five years and have no salvage value. Select the adjusting entry made on December 31, to record the depreciation of the oven for one year.
(Multiple Choice)
4.8/5 (67)
(67) On a worksheet, the adjusted balance of the revenue account Fees Income would be extended to:
(Multiple Choice)
4.8/5 (75)
(75) The account accumulated depreciation has a normal________ balance.
(Short Answer)
4.9/5 (86)
(86) Which of the following entries records the depreciation on equipment for the fiscal year-end adjustment?
(Multiple Choice)
4.8/5 (87)
(87) On a worksheet, the adjusted balance of the Prepaid Rent account is extended to the:
(Multiple Choice)
4.7/5 (91)
(91) Equipment costing $27,000 with an estimated salvage value of $2,040 and an estimated life of 4 years was purchased on October 31, 2019. Using the straight-line depreciation method, what is the amount of depreciation expense to be recorded at December 31, 2019?
(Multiple Choice)
4.9/5 (95)
(95) Match the description with the accounting terms.
Correct Answer: Verified
Premises:
Responses:
(Matching)
4.9/5 (74)
(74) The balances of the ledger accounts for Buffet Services on September 30, 2019, and the information needed for adjustments are shown below. Prepare the Trial Balance section, record the adjustments, and complete the worksheet.
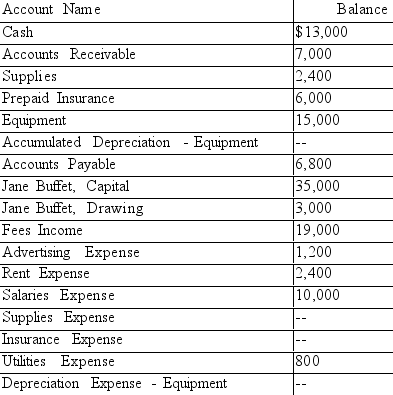 Adjustment information:
(a)The supplies were purchased on September 1, 2019. An inventory of supplies showed $1,200 on hand on September 30, 2019.
(b)The amount of Prepaid Insurance represents a payment made September 1, 2019, for a six-month
insurance policy.
(c)The equipment, purchased September 1, 2019, has an estimated useful life of 5 years with no salvage value. The firm uses the straight-line method of depreciation.
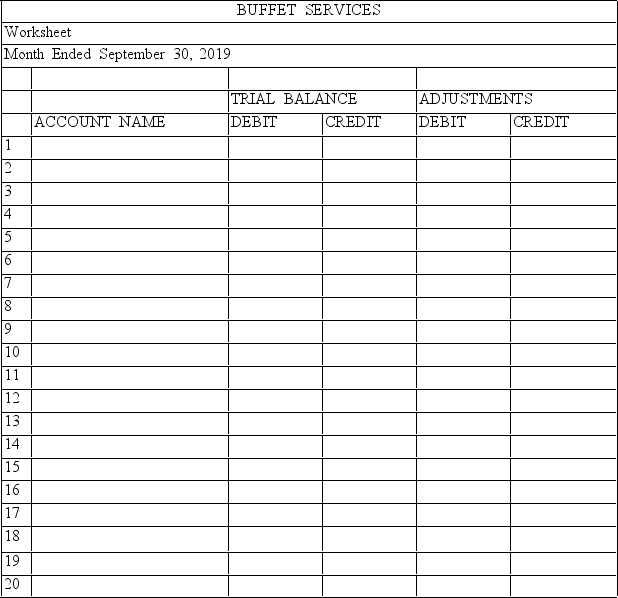
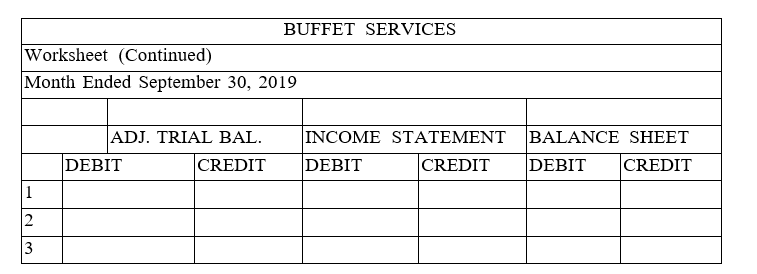
Adjustment information:
(a)The supplies were purchased on September 1, 2019. An inventory of supplies showed $1,200 on hand on September 30, 2019.
(b)The amount of Prepaid Insurance represents a payment made September 1, 2019, for a six-month
insurance policy.
(c)The equipment, purchased September 1, 2019, has an estimated useful life of 5 years with no salvage value. The firm uses the straight-line method of depreciation.
(Essay)
4.9/5 (71)
(71) For each of the accounts listed below, enter the words, Increase or Decrease, in the Debit and Credit columns to indicate the effects of each on the account balance.

(Essay)
4.9/5 (75)
(75) The cost of a long-term asset, such as equipment, is transferred to expense as it is used during its useful life.
(True/False)
4.8/5 (74)
(74) The adjusting entry to account for the expiration of prepaid insurance consists of:
(Multiple Choice)
4.8/5 (79)
(79) The unadjusted net income on the income statement was $46,850. After journalizing and posting the adjusting entry for the $2,300 of supplies used during the year, the adjusted net income is:
(Multiple Choice)
4.8/5 (85)
(85) On September 1, 2019, Jay Walker Company purchased a one-year insurance policy for $1,320. The correct adjusting entry on December 31, 2019, is:
(Multiple Choice)
4.9/5 (67)
(67) The balance in the account Accumulated Depreciation, Equipment will:
(Multiple Choice)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)