



 Chat with AI
Exam 17: Merchandise Inventory

Exam 1: Accounting: The Language of Business84 Questions
Exam 2: Analyzing Business Transactions100 Questions
Exam 3: Analyzing Business Transactions Using T Accounts116 Questions
Exam 4: The General Journal and the General Ledger98 Questions
Exam 5: Adjustments and the Worksheet97 Questions
Exam 6: Closing Entries and Teh Postclosing Trial Balance97 Questions
Exam 7: Accounting for Sales and Accounts Receivable99 Questions
Exam 8: Accounting for Purchases and Accounts Payable111 Questions
Exam 9: Cash Receipts, Cash Payments, and Banking Procedures92 Questions
Exam 10: Payroll Computations, Records, and Payment89 Questions
Exam 11: Payroll Taxes, Deposits, and Reports88 Questions
Exam 12: Accruals, Deferrals, and the Worksheet94 Questions
Exam 13: Financial Statements and Closing Procedures92 Questions
Exam 14: Accounting Principles and Reporting Standards95 Questions
Exam 15: Accounts Receivable and Uncollectible Accounts93 Questions
Exam 16: Notes Payable and Notes Receivable101 Questions
Exam 17: Merchandise Inventory114 Questions
Exam 18: Property, Plant, and Equipment123 Questions
Exam 19: Accounting for Partnerships118 Questions
Exam 20: Corporations: Formation and Capital Stock Transactions104 Questions
Exam 21: Corporate Earnings and Capital Transactions118 Questions
Exam 22: Long-Term Bonds114 Questions
Exam 23: Financial Statement Analysis131 Questions
Exam 24: The Statement of Cash Flows154 Questions
Exam 25: Departmentalized Profit and Cost Centers121 Questions
Exam 26: Accounting for Manufacturing Activities114 Questions
Exam 27: Job Order Cost Accounting111 Questions
Exam 28: Process Cost Accounting99 Questions
Exam 29: Controlling Manufacturing Costs: Standard Costs126 Questions
Exam 30: Cost-Revenue Analysis for Decision Making126 Questions
Select questions type


On July 1, a tornado destroyed the warehouse where The Brooks Boys Sports Equipment Company stored their inventory. The inventory was, for the most part, destroyed by the force of the storm. The usual gross profit rate for the company was 30%. The beginning inventory of
$220,000 was recorded on the prior year's financial reports. The net sales to date are known to be
$886,450, and net purchases (including freight-in charges and purchases returns)were $580,000. Using the gross profit method of inventory valuation, determine the value of the inventory that was destroyed.

Free
(Short Answer)
4.8/5  (82)
(82) Correct Answer: Verified
estimated ending inventory $179,485.
Net Sales minus Gross Profit equals--------- .
Free
(Short Answer)
4.8/5 (74)
(74) Correct Answer:Verified
VerifiedCost of Goods Sold
A business is required to apply the lower of cost or net realizable value rule by comparing and reporting inventory values on an item-by-item basis.
Free
(True/False)
5.0/5 (79)
(79) Correct Answer:Verified
VerifiedFalse
The-------- method of estimating inventory requires the use of data about both cost and selling prices.
(Short Answer)
4.8/5 (80)
(80) For each of the following statements, determine which method of inventory valuation (FIFO or LIFO)it depicts.
1. The ending inventory is higher when using this method when costs are rising.
2. The cost of goods sold is higher when using this method when costs are rising.
3. When prices are rising, this method results in higher net income.
4. If this method is used for federal tax purposes, it must also be adopted for it financial accounting.
5. This method is not accepted in some countries.
6. When prices are rising, the average cost method will result in an ending inventory tha is higher than which method?
(Short Answer)
4.7/5 (79)
(79) Adams Company uses the specific identification method. At the end of the year, it had 24 units of its giant floating tricycles that are sold for use by tourists in the ocean or on large lakes. Explain how the physical count of inventory and the cost of ending inventory will be calculated.
(Essay)
4.8/5 (92)
(92) The gross profit method of estimating inventory enables managers to prepare budgets and pro-forma (forecast or anticipated)financial statements.
(True/False)
4.7/5 (72)
(72) The following information concerns several of the inventory items at DC's.
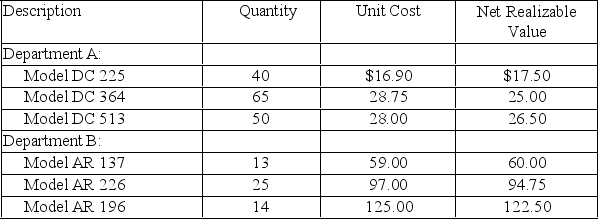 Determine the amount of inventory to be reported on the financial statements using the lower of cos or net realizable value method of valuation under each of the following options.
1. Lower of cost or net realizable value for each item separately
2. Lower of total cost or total net realizable value
3. Lower of total cost or total net realizable value by department
Determine the amount of inventory to be reported on the financial statements using the lower of cos or net realizable value method of valuation under each of the following options.
1. Lower of cost or net realizable value for each item separately
2. Lower of total cost or total net realizable value
3. Lower of total cost or total net realizable value by department (Short Answer)
4.9/5 (91)
(91) Inventory costing methods are influenced by industry practice and the types of merchandise available for sale.
(True/False)
4.8/5 (78)
(78) In applying the lower of cost or net realizable value rule, "net realizable value" is defined as the price at which the last unit was purchased.
(True/False)
4.8/5 (68)
(68) The inventory valuation used will affect the net income or net loss reported on the income statement.
(True/False)
4.8/5 (76)
(76) When the replacement cost of an item is below its original purchase cost, it is necessary to value the inventory at net realizable value in order to reflect the lower current value in the firm's financial records.
(True/False)
5.0/5 (72)
(72) In highly competitive businesses where inventory is subject to price fluctuations and model or style upgrades, it is desirable to utilize the weighted average method costing method.
(True/False)
4.8/5 (95)
(95) The average cost method of inventory valuation will always result in the lowest reported net income.
(True/False)
4.9/5 (76)
(76) Which of the following is NOT a way to apply the lower of cost or net realizable value rule?
(Multiple Choice)
4.8/5 (95)
(95) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)