



 Chat with AI
Exam 18: Property, Plant, and Equipment

Exam 1: Accounting: The Language of Business84 Questions
Exam 2: Analyzing Business Transactions100 Questions
Exam 3: Analyzing Business Transactions Using T Accounts116 Questions
Exam 4: The General Journal and the General Ledger98 Questions
Exam 5: Adjustments and the Worksheet97 Questions
Exam 6: Closing Entries and Teh Postclosing Trial Balance97 Questions
Exam 7: Accounting for Sales and Accounts Receivable99 Questions
Exam 8: Accounting for Purchases and Accounts Payable111 Questions
Exam 9: Cash Receipts, Cash Payments, and Banking Procedures92 Questions
Exam 10: Payroll Computations, Records, and Payment89 Questions
Exam 11: Payroll Taxes, Deposits, and Reports88 Questions
Exam 12: Accruals, Deferrals, and the Worksheet94 Questions
Exam 13: Financial Statements and Closing Procedures92 Questions
Exam 14: Accounting Principles and Reporting Standards95 Questions
Exam 15: Accounts Receivable and Uncollectible Accounts93 Questions
Exam 16: Notes Payable and Notes Receivable101 Questions
Exam 17: Merchandise Inventory114 Questions
Exam 18: Property, Plant, and Equipment123 Questions
Exam 19: Accounting for Partnerships118 Questions
Exam 20: Corporations: Formation and Capital Stock Transactions104 Questions
Exam 21: Corporate Earnings and Capital Transactions118 Questions
Exam 22: Long-Term Bonds114 Questions
Exam 23: Financial Statement Analysis131 Questions
Exam 24: The Statement of Cash Flows154 Questions
Exam 25: Departmentalized Profit and Cost Centers121 Questions
Exam 26: Accounting for Manufacturing Activities114 Questions
Exam 27: Job Order Cost Accounting111 Questions
Exam 28: Process Cost Accounting99 Questions
Exam 29: Controlling Manufacturing Costs: Standard Costs126 Questions
Exam 30: Cost-Revenue Analysis for Decision Making126 Questions
Select questions type


The conservatism principle requires choosing a depreciation method which matches the cost of the asset to the periods when the asset provides benefits to the business.
(True/False)
4.9/5  (76)
(76) To calculate declining-balance depreciation, the-------------- of an asset is multiplied by a predetermined appropriate rate.
(Short Answer)
4.7/5 (87)
(87) A company purchased equipment for $16,000 cash. In addition, the company paid $1,120 in sales taxes, $930 to have the equipment delivered and $500 to have it installed. The cost of this asset for financial accounting purposes is:
(Multiple Choice)
4.9/5 (73)
(73) The allocation of the costs of natural resources, such as minerals, to expense as the resource is extracted is referred to as:
(Multiple Choice)
4.9/5 (81)
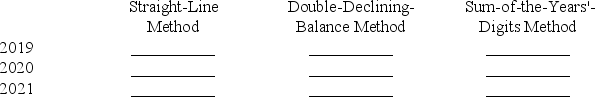
(81) On January 2, 2019, the Hanover Company purchased some office equipment for $26,000. The equipment is expected to have a useful life of five years and a salvage value of $2,000. Prepare a schedule showing the annual depreciation for each of the first three years of the asset's life under the straight-line method, the double-declining-balance method, and the sum-of-the-years'-digits method.
(Essay)
4.8/5 (76)
(76) The Modified Accelerated Cost Recovery System (MACRS)is required for----------- purposes.
(Short Answer)
5.0/5 (87)
(87) On, January 2, 2019, Rubble Sand and Gravel Company purchased equipment for $77,000. The equipment was to be used for five years and had a $2,000 estimated residual value.
On January 2, 2019, equipment was sold for $35,000. Record the transactions on page 9 of a genera journal. Omit descriptions.
(Essay)
4.9/5 (90)
(90) On, January 2, 2016, Rubble Sand and Gravel Company purchased equipment for $77,000 The equipment was to be used for five years and had a $2,000 estimated residual value.
On January 2, 2019, equipment was sold for $30,000. Record the transactions on page 9 of a general journal. Omit descriptions.
(Essay)
4.8/5 (78)
(78) If the property used in a business has physical substance and is not real estate it is-----------property.
(Short Answer)
4.9/5 (68)
(68) Book value is used in calculating a gain or loss on the disposal of an asset.
(True/False)
4.9/5 (86)
(86) The modified accelerated cost recovery system (MACRS)is acceptable for financial accounting purposes because it matches the costs of assets with the revenues produced by those assets.
(True/False)
4.7/5 (82)
(82) Before an asset is sold, the depreciation must be updated to the date of sale.
(True/False)
5.0/5 (79)
(79) The allocation of the acquisition cost of an intangible asset to expense during its estimated useful life is called----------- .
(Short Answer)
4.8/5 (84)
(84) In 2019 a mining company paid $180,000 for mining rights. It is estimated that a total of 225,000 tons of ore are available to be extracted. During 2019, 21,000 tons of ore were mined. What is the amount of Depletion Expense recorded in the adjusting entry for 2019?
(Short Answer)
4.8/5 (82)
(82) The acquisition cost of an intangible asset should be charged to expense over the shorter of its legal or useful life, whichever is shorter.
(True/False)
4.8/5 (79)
(79) Accelerated depreciation methods allocate greater amounts of depreciation expense in the asset's early years of useful life which provides an investment incentive to businesses to take this
non-cash deduction and reduce current period income taxes.
(True/False)
4.9/5 (88)
(88) Which method of depreciation is not acceptable for financial accounting purposes?
(Multiple Choice)
4.8/5 (96)
(96) An asset that cost $35,000 was sold for $6,000 cash. Accumulated depreciation on the asset was
$29,000. The entry to record this transaction includes the recognition of:
(Multiple Choice)
4.9/5 (76)
(76) Selected transactions of the Harrel Company are listed below. The company uses the straight-line method of depreciation. Record the transactions on page 9 of a general journal. Omit descriptions.
2019
Jan. 5 Purchased office equipment at a price of $6,000 FOB. The freight charge was
$48; the installation charge was $200.
April 1 Sold warehouse equipment for $5,000 in cash. The equipment was purchased on January 3, 2016, for $18,000. The equipment has a useful life of five years and a salvage value of $1,000. Depreciation was last recorded on December 31, 2018.
July 1 Sold office equipment for $2,500 in cash. The equipment was purchased on July 3, 2016, for $3,500. The equipment has a useful life of five years and a salvage value of $500. Depreciation was last recorded on December 31, 2018.
2020
Jan. 2 Traded in office equipment for new equipment that is similar. The list price of the new office equipment is $15,000. Paid $9,000 cash and received a trade-in allowance of $6,000 for the old equipment. The old equipment had been purchased on January 3, 2016, for $12,000. The old equipment had an estimated useful life of five years and a salvage value of $2,000. Depreciation on the old equipment was last recorded on December 31, 2019. (Use the income tax method to record the trade-in.)
Jan. 4 Traded in warehouse equipment for new equipment that is similar. The list price of the new warehouse equipment is $26,000. Paid $20,000 cash and received a trade-in allowance of $6,000 for the old equipment. The old equipment had been purchased on January 4, 2016, for $24,000. The old equipment had an estimated useful life of five years and a salvage value of $4,000. Depreciation on the old equipment was last recorded on December 31, 2020. (Use the fair market value method to record the trade-in.)
(Essay)
5.0/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)