



 Chat with AI
Exam 22: Long-Term Bonds

Exam 1: Accounting: The Language of Business84 Questions
Exam 2: Analyzing Business Transactions100 Questions
Exam 3: Analyzing Business Transactions Using T Accounts116 Questions
Exam 4: The General Journal and the General Ledger98 Questions
Exam 5: Adjustments and the Worksheet97 Questions
Exam 6: Closing Entries and Teh Postclosing Trial Balance97 Questions
Exam 7: Accounting for Sales and Accounts Receivable99 Questions
Exam 8: Accounting for Purchases and Accounts Payable111 Questions
Exam 9: Cash Receipts, Cash Payments, and Banking Procedures92 Questions
Exam 10: Payroll Computations, Records, and Payment89 Questions
Exam 11: Payroll Taxes, Deposits, and Reports88 Questions
Exam 12: Accruals, Deferrals, and the Worksheet94 Questions
Exam 13: Financial Statements and Closing Procedures92 Questions
Exam 14: Accounting Principles and Reporting Standards95 Questions
Exam 15: Accounts Receivable and Uncollectible Accounts93 Questions
Exam 16: Notes Payable and Notes Receivable101 Questions
Exam 17: Merchandise Inventory114 Questions
Exam 18: Property, Plant, and Equipment123 Questions
Exam 19: Accounting for Partnerships118 Questions
Exam 20: Corporations: Formation and Capital Stock Transactions104 Questions
Exam 21: Corporate Earnings and Capital Transactions118 Questions
Exam 22: Long-Term Bonds114 Questions
Exam 23: Financial Statement Analysis131 Questions
Exam 24: The Statement of Cash Flows154 Questions
Exam 25: Departmentalized Profit and Cost Centers121 Questions
Exam 26: Accounting for Manufacturing Activities114 Questions
Exam 27: Job Order Cost Accounting111 Questions
Exam 28: Process Cost Accounting99 Questions
Exam 29: Controlling Manufacturing Costs: Standard Costs126 Questions
Exam 30: Cost-Revenue Analysis for Decision Making126 Questions
Select questions type


To calculate the gain or loss on the retirement of bonds, the carrying value of the bonds is subtracted from the repurchase price.
(True/False)
4.8/5  (72)
(72) Any gain or loss recognized from the early retirement of bonds should be reported on the income statement for the period in which the bonds were retired.
(True/False)
4.9/5 (84)
(84) A corporation paid $103,000 to retire bonds with a face value of $100,000 and an unamortized discount balance of $2,500. The entry to record the early retirement of the bonds will include the recognition of a loss of
(Multiple Choice)
4.9/5 (81)
(81) The issuing corporation amortizes the bond discount from the date of issue to the maturity date, which will----------- the bond interest expense shown on the income statement.
(Short Answer)
4.9/5 (79)
(79) Galoot Corporation pays and records the semiannual interest on its $500,000, 10-year, 6% bonds outstanding on July 1, 2019. On the same date, amortization of the discount of $10,000 received on $200,000 of those bonds is recorded. Prepare the journal entries recorded by Galoot Corporation.
(Essay)
5.0/5 (89)
(89) Bonds are often issued as a means of raising capital to pay off short-term debt.
(True/False)
4.8/5 (73)
(73) If a corporation plans to issue $4,000,000 of 5% bonds at a time when the market rate of interest for similar bonds is 6%, the bonds will sell at:
(Multiple Choice)
4.7/5 (81)
(81) Match the following definitions with the proper terms.
Correct Answer: Verified
Premises:
Responses:
(Matching)
4.8/5 (84)
(84) If bonds with a face value of $100,000 and a carrying value of $103,000 are retired early by paying cash of $101,000, a---------- will be reported on the income statement for the period.
(Short Answer)
4.9/5 (77)
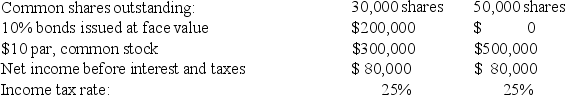
(77) Given the following information about a company's financing and net earnings, show in partial income statement format, why it might be advantageous to a stockholder for a company to issue bonds rather than stock to raise additional capital. Include an analysis of return on equity investmen
(Essay)
4.8/5 (89)
(89) If the market rate of interest is higher than the contract rate of interest offered on the bonds being sold, they will be sold at
(Multiple Choice)
4.8/5 (79)
(79) A company issues 9%, 20-year bonds with a face value of $400,000. The current market rate of interest is 8%. The amount of interest owed to the bondholders for each semiannual interest payment is:
(Multiple Choice)
4.8/5 (81)
(81) The Crowley Corporation issued $600,000 face value of 10-year, 8 percent bonds dated April 1, 2019, and maturing on April 1, 2029. Interest is payable semiannually on April 1 and October 1. The bonds were issued at 103. Record the transactions to issue the bonds on April 1, 2019, and to pay interest and amortize the bond discount on October 1, on page 9 of a general journal. Omit descriptions.
(Essay)
4.8/5 (86)
(86) Ten-year bonds with a face value of $600,000 were issued at 96 on January 1, 2019. The carrying value of the bond on December 31, 2020, after two years of interest payments and straight-line amortization is:
(Multiple Choice)
4.8/5 (82)
(82) When bonds are issued at a price below face value, the Discount on Bonds Payable account is------------for the difference between the issue price and the face value.
(Short Answer)
4.7/5 (76)
(76) Amortizing a bond premium over the period from the issue date to the maturity date reduces the amount of bond interest expense shown on the income statement.
(True/False)
5.0/5 (76)
(76) On September 1, 2019, a corporation paid $620,000 to retire bonds with a face value of $600,000 and an unamortized bond premium of $10,000. Record the transaction on page 8 of a general journal. Omit the description.
(Essay)
4.9/5 (91)
(91) The board of directors of the Merced Corporation authorized the issuance of $200,000 face value of 10-year, 12 percent bonds dated April 1, 2019, and maturing on April 1, 2029. Interest is payable semiannually on April 1 and October 1. Each bond has a face value of $1,000. Because the funds to be raised were not immediately needed, no bonds were issued until 2021. Record the following transactions on page 9 of a general journal. Omit descriptions.
2021
Apr. 1 Issued $40,000 of bonds at 96
Oct. 1 Paid the semiannual bond interest
1 Recorded the amortization of the discount on the bonds sold on April 1 using the straight-line method
1 Issued $30,000 of bonds at face value
Dec. 31 Recorded the adjusting entry to accrue the bond interest and to amortize the discount
31 Closed the Bond Interest Expense account into the Income Summary account
(Essay)
4.9/5 (77)
(77) Using borrowed funds to earn a profit higher than the interest charged for borrowing is called
(Multiple Choice)
4.9/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)