



 Chat with AI
Exam 22: Accounting for Superannuation Plans

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


Superannuation funds are monitored and regulated by the Australian Vigilance Regulation Authority and the Australian Securities and Investments Commission.
(True/False)
4.8/5  (72)
(72) The disclosure requirements for a defined contribution plan include:
(Multiple Choice)
4.9/5 (83)
(83) AAS 25 Financial Reporting by Superannuation Plans deals with accounting in an employer's financial reports for employee entitlements,including retirement benefits.
(True/False)
4.8/5 (73)
(73) Use of professional judgment to establish the net market values of assets is not permitted on which of the following matters?
(Multiple Choice)
4.8/5 (79)
(79) For a defined contribution plan and a defined benefit plan,the changes in net market values of the plan's financial liabilities since the beginning of the reporting period shall be included in the profit or loss for the reporting period.
(True/False)
5.0/5 (74)
(74) AAS 25 requires that all the assets of superannuation plans be measured at:
(Multiple Choice)
4.7/5 (84)
(84) The argument in support of AAS 25's selected method of measuring assets for superannuation plans is that:
(Multiple Choice)
4.9/5 (91)
(91) Long-lived Superannuation Plan provides the following information regarding its assets and receipts for the year ended 30 June 2014: 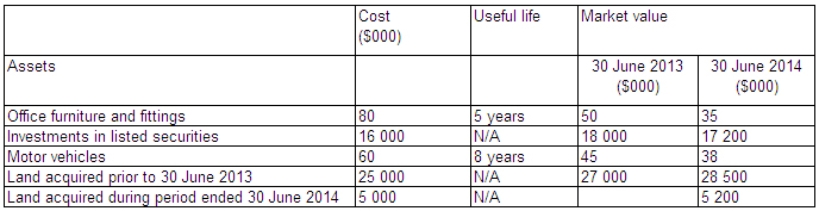 During the period,land acquired before 30 June 2013 was sold.The land had a cost of $1 million,a market value at 30 June 2013 of $2 million,and was sold for $2.8 million.What is the revenue of the superannuation plan for the period in accordance with AAS 25?
 (Multiple Choice)
4.8/5 (83)
(83) According to AAS 25,the revenue of a superannuation fund should include the changes in net market value of all plan assets over the period.
(True/False)
4.9/5 (75)
(75) Maestro Superannuation Plan provides the following information relating to the period ended 30 June 2014: Gross benefit payment to an individual based on an actuarial analysis as at 30 June 2014 \ 370000 Commonwealth government guaranteed securities 4\% Current anticipated rate of return on assets (for the period of the benefit liability) 6\% Quality corporate bond rate for the period of the benefit liability 5\% The actuarial assumption used to calculate the liability was that the individual would take the benefit as a lump sum on retirement in 8 years' time.What is the present value of the expected future benefit payment (rounded to the nearest dollar)?
(Multiple Choice)
4.9/5 (87)
(87) Contrast the measurement rules that apply to assets of superannuation funds from assets held for backing general insurance liabilities.What effects would these have on the qualitative characteristics of financial reports.
(Essay)
4.9/5 (73)
(73) Contrast the measurement of assets as required in AAS 25 for superannuation funds with that required in AASB 1023 for general insurers.
(Essay)
4.9/5 (80)
(80) Maestro Superannuation Plan provides the following information relating to the period ended 30 June 2014: Gross benefit payment to an individual based on an actuarial analysis as at 30 June 2014 \ 400000 Commonwealth government guaranteed securities 5\% Current anticipated rate of return on assets (for the period of the benefit liability) 8\% Quality corporate bond rate for the period of the benefit liability 7\% The actuarial assumption used to calculate the liability was that the individual would take the benefit as a lump sum on retirement in 10 years' time.What is the present value of the expected future benefit payment (rounded to the nearest dollar)?
(Multiple Choice)
4.8/5 (78)
(78) The revenue recognition and asset valuation methods specified in AAS 25 are likely to increase the volatility of reported earnings.This is because:
(Multiple Choice)
4.7/5 (85)
(85) The required disclosures for a defined benefit plan include:
(Multiple Choice)
4.8/5 (79)
(79) AAS 25 requires a defined benefit plan to append to its financial statements an actuarial report that contains the following information:
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)