



 Chat with AI
Exam 22: Accounting for Superannuation Plans

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


For a defined contribution plan to satisfy the reporting requirements of AAS 25 it must provide:
(Multiple Choice)
4.9/5  (83)
(83) A defined benefit superannuation plan is required to provide additional disclosures in the actuarial report most recently prepared for the plan.These disclosures include:
(Multiple Choice)
4.8/5 (92)
(92) AAS 25 is relevant for superannuation plans that are reporting entities.A reporting entity is one for which:
(Multiple Choice)
4.9/5 (92)
(92) The purpose of all superannuation plans is to guarantee a specified level of retirement,death or disability benefits for members of the plan.
(True/False)
4.9/5 (82)
(82) The following information relates to the Montigo Superannuation Plan,which is a defined benefit scheme.Amounts given for all assets are at net market value. Year ended Year ended 30 June 2014 30 June 2015 ( \0 00) ( \0 00) Government securities 4900 3600 Mortgage loans 7100 8500 Shares in listed companies 9000 10250 Fixtures and fittings 19 17 Other information ( \0 00) Cash 45 Accounts payable 60 Benefits paid 110 Investment expenses 12 General and administration expenses 48 Interest received 1000 Dividends received 800 Members' contributions received 95 Employers' contributions received 210 At balance date the scheme is owed from the current period. Interest \ 42000 Dividends \ 59000 Contributions from members \ 17000 Contributions from employers \ 28000 During the period shares in listed companies that had a net realisable value of $7 million at the beginning of the period were sold for $8.5 million.Shares were purchased during the period for $3 million. The fund has not had an actuarial review undertaken as at balance date.What are the net assets available to pay benefits at 30 June 2015?
(Multiple Choice)
4.9/5 (79)
(79) What is the accounting treatment for sale of non-current assets in a superannuation plan?
(Essay)
4.9/5 (90)
(90) AAS 25 permits use of cost or revalued basis in measuring assets of a defined contribution plan and a defined benefit plan.
(True/False)
4.9/5 (80)
(80) The following information relates to the Old Fogey's Superannuation Plan,which is a defined benefit scheme.Amounts given for all assets are at net market value. Year ended Year ended 30 June 2014 30 June 2015 (\ 000) (\ 000) Government securities 8600 7500 Mortgage loans 2500 3125 Shares in listed companies 11000 12500 Fixtures and fitting 275 250 Other information ( \0 00) Cash 50 Accounts payable 40 Benefits paid 95 Investment expenses 19 General and administration expenses 50 Interest received 940 Dividends received 20 Members' contributions received 87 Employers' contributions received 174 At balance date the scheme is owed from the current period. Interest \ 51000 Dividends \ 65000 Contributions from members \ 6000 Contributions from employers \ 12000 During the period shares in listed companies that had a net realisable value of $5 million at the beginning of the period were sold for $6.2 million.Shares were purchased during the period for $2 million. Actuarial reports on the fund are undertaken annually at balance date.The actuarial estimate of the accrued benefits were:
30 June 2000: \ 44100000 30 June 2013: \ 52300000 What is the total revenue for the plan for the period ended 30 June 2015?
(Multiple Choice)
4.8/5 (81)
(81) According to AAS 25,beneficiaries of a defined contribution plan will be interested in evaluating:
(Multiple Choice)
4.8/5 (77)
(77) Happy Days Superannuation Plan provides the following information regarding its assets and receipts for the year ended 30 June 2014: 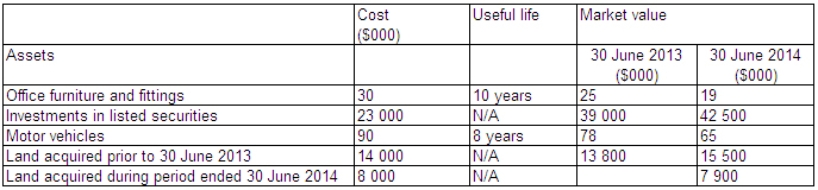 During the period land acquired before 30 June 2013 was sold.The land had a cost of $4 million,a market value at 30 June 2013 of $4.5 million,and was sold for $6 million.What is the revenue of the superannuation plan for the period in accordance with AAS 25?
 (Multiple Choice)
5.0/5 (100)
(100) The accounting treatment for the sale of non-current assets by a superannuation fund involves the following steps:
(Multiple Choice)
4.9/5 (80)
(80) In what way is the asset measurement requirement in AAS 25 Financial Reporting by Superannuation Plans inconsistent with the treatment required in AASB 1023 Financial Reporting of General Insurance Activities?
(Multiple Choice)
4.8/5 (79)
(79) According to AAS 25,superannuation plans must provide a statement of financial position,an operating statement and a statement of cash flows in which of the following situations?
(Multiple Choice)
4.9/5 (73)
(73) In the case of a defined benefit plan,the statements the trustees must provide if a detailed actuarial review has not been conducted at balance date include:
(Multiple Choice)
4.7/5 (74)
(74) Accounting standards regulate the provision of reports by superannuation plans,including information on the performance and position of the plan and individual members' contributions and entitlements.
(True/False)
4.8/5 (61)
(61) When a member remains in a defined benefit plan until retirement,the amount paid out is determined by reference to their contributions and investment earnings thereon.
(True/False)
4.8/5 (82)
(82) Maestro Superannuation Plan provides the following information relating to the period ended 30 June 2014: Gross benefit payment to an individual based on an actuarial analysis as at 30 June 2014 \ 260000 Commonwealth government guaranteed securities 4\% Current anticipated rate of return on assets (for the period of the benefit liability) 7\% Quality corporate bond rate for the period of the benefit liability 6\% The actuarial assumption used to calculate the liability was that the individual would take the benefit as a lump sum on retirement in 9 years' time.What is the present value of the expected future benefit payment (rounded to the nearest dollar)?
(Multiple Choice)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)