



 Chat with AI
Exam 25: Related Party Disclosures

Exam 1: An Overview of the Australian External Reporting Environment70 Questions
Exam 2: The Conceptual Framework of Accounting and Its Relevance to Financial Reporting72 Questions
Exam 3: Theories of Accounting76 Questions
Exam 4: An Overview of Accounting for Assets77 Questions
Exam 5: Depreciation of Property, plant and Equipment77 Questions
Exam 6: Revaluations and Impairment Testing of Non-Current Assets76 Questions
Exam 7: Inventory75 Questions
Exam 8: Accounting for Intangibles77 Questions
Exam 9: Accounting for Heritage Assets and Biological Assets76 Questions
Exam 10: An Overview of Accounting for Liabilities78 Questions
Exam 11: Accounting for Leases81 Questions
Exam 12: Accounting for Employee Benefits84 Questions
Exam 13: Share Capital and Reserves85 Questions
Exam 14: Accounting for Financial Instruments90 Questions
Exam 15: Revenue Recognition Issues79 Questions
Exam 16: The Statement of Comprehensive Income and Statement of Changes in Equity77 Questions
Exam 17: Accounting for Share-Based Payments77 Questions
Exam 18: Accounting for Income Taxes80 Questions
Exam 19: The Statement of Cash Flows77 Questions
Exam 20: Accounting for the Extractive Industries75 Questions
Exam 21: Accounting for General Insurance Contracts73 Questions
Exam 22: Accounting for Superannuation Plans77 Questions
Exam 23: Events Occurring After the End of the Reporting Period77 Questions
Exam 24: Segment Reporting77 Questions
Exam 25: Related Party Disclosures77 Questions
Exam 26: Earnings Per Share76 Questions
Exam 27: Accounting for Group Structures87 Questions
Exam 28: Further Consolidation Issues I: Accounting for Intragroup Transactions60 Questions
Exam 29: Further Consolidation Issues II: Accounting for Non-Controlling Interests44 Questions
Exam 30: Further Consolidation Issues IV: Accounting for Changes in the Degree of Ownership of a Subsidiary49 Questions
Exam 31: Accounting for Equity Investments,including Investments in Associates and Joint Arrangements70 Questions
Exam 32: Accounting for Foreign Currency Transactions78 Questions
Exam 33: Translating the Financial Statements of Foreign Operations52 Questions
Exam 34: Accounting for Corporate Social Responsibility73 Questions
Select questions type


Entities included in a wholly owned group as defined by AASB 124 include:
(Multiple Choice)
4.9/5  (80)
(80) The most common form of relationship based on significant influence is that between:
(Multiple Choice)
4.9/5 (76)
(76) Some business leaders argue that related-party transactions have benefits for the reporting entity.The benefits are said to include:
(Multiple Choice)
4.9/5 (74)
(74) Which of the following transactions is usually not considered a 'related party' in AASB 124?
(Multiple Choice)
4.9/5 (75)
(75) Which of the following disclosures on key management personnel is/are required in AASB 124 for disclosing entities?
(Multiple Choice)
4.9/5 (86)
(86) The most common example of a relationship reflecting control is that between an investor and its associate company.
(True/False)
4.9/5 (88)
(88) Which of the following is typically a related-party transaction within the provisions of AASB 124 Related Party Disclosures?
(Multiple Choice)
4.8/5 (80)
(80) In AASB 124 Related Party Disclosures,two entities having a director in common are assumed related parties.
(True/False)
4.7/5 (82)
(82) With respect to loans made to a related party,which of the following statements is correct in accordance with AASB 124?
(Multiple Choice)
4.8/5 (67)
(67) AASB 124 requires a standard,detailed set of disclosure requirements for all related-party transactions.
(True/False)
4.8/5 (81)
(81) The Business Council of Australia (BCA)is opposed to the extensive disclosure requirements of directors' and executives' remuneration.Discuss the unintended consequences put forward by BCA in their submission to the Parliamentary Joint Committee on Corporations and Financial Services on the CLERP Bill.Comment on the validity of the points raised by BCA.
(Essay)
4.9/5 (82)
(82) Bartholomeusz writes that the non-binding votes by shareholders on remuneration introduced under the Corporate Law Economic Reform Program (CLERP)9 is described as an 'empty gesture' in response to fierce criticism of excessive remuneration.Discuss.
(Essay)
4.8/5 (77)
(77) The annual remuneration report of the entity is to be put to a non-binding vote of the shareholders.
(True/False)
4.8/5 (94)
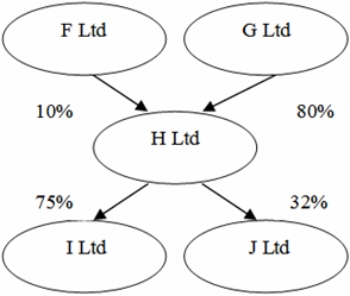
(94) The following diagram shows five companies and their associated equity ownership percentages.Which of the companies shown would most likely be considered related entities?
(Multiple Choice)
4.7/5 (93)
(93) The disclosures that AASB 124 requires for other related parties are:
(Multiple Choice)
4.9/5 (88)
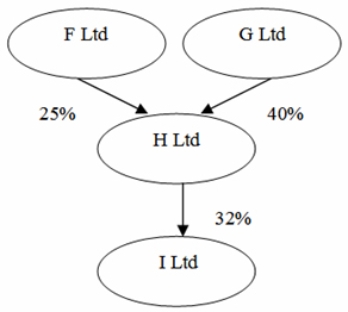
(88) The following diagram shows four companies and their associated equity ownership percentages.Which of the companies shown would most likely be considered related entities?
(Multiple Choice)
4.8/5 (81)
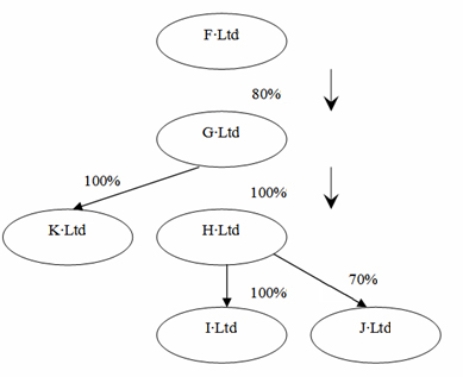
(81) In the following diagram,which entities would be included in a wholly owned group according to the definition in AASB 124?
(Multiple Choice)
4.8/5 (73)
(73) Directors' income is defined in AASB 124 as including only:
(Multiple Choice)
4.9/5 (79)
(79) AASB 124 requires an entity to disclose total compensation of key management personnel.What items are included in key management personnel's remuneration/compensation?
(Essay)
4.8/5 (77)
(77) AASB 124 Related Party Disclosures,requires relationships between parents and subsidiaries be disclosed irrespective of whether there have been transactions between those related parties.
(True/False)
5.0/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)