



 Chat with AI
Exam 8: Interest Rate Risk I

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


Duration Bank has the following assets and liabilities as of year-end. All assets and liabilities are currently priced at par and pay interest annually. 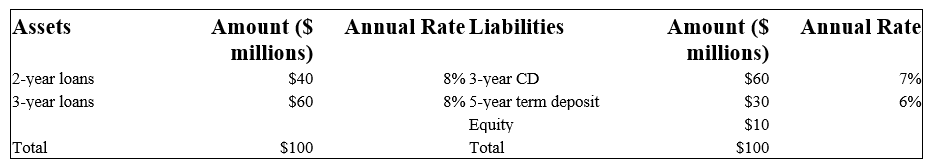 -What is the FI's maturity gap?
 (Multiple Choice)
4.9/5  (91)
(91) The balance sheet of ARGH Insurance shows the following fixed and rate-sensitive assets and liabilities. 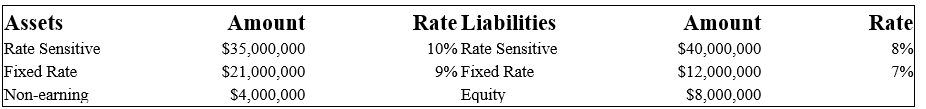 -What will be the FI's net interest income at year-end if interest rates do not change?
 (Multiple Choice)
5.0/5 (87)
(87) When repricing all interest-sensitive assets and all interest-sensitive liabilities in a balance sheet,the cumulative gap will be
(Multiple Choice)
4.8/5 (82)
(82) For a given change in interest rates,fixed-rate liabilities with longer-term maturities will have smaller changes in price than liabilities with shorter maturities.
(True/False)
4.9/5 (83)
(83) A bank with a negative repricing (or funding)gap faces reinvestment risk.
(True/False)
4.8/5 (84)
(84) The balance sheet of ARGH Insurance shows the following fixed and rate-sensitive assets and liabilities.
-Suppose short-term interest rates increase by 1 percent.Calculate the change in net interest income after the interest rate increase.
-Suppose short-term interest rates increase by 1 percent.Calculate the change in net interest income after the interest rate increase. (Multiple Choice)
4.9/5 (79)
(79) The following is the balance sheet of Boston Bank. The average maturity of demand deposits is estimated at 2 years. 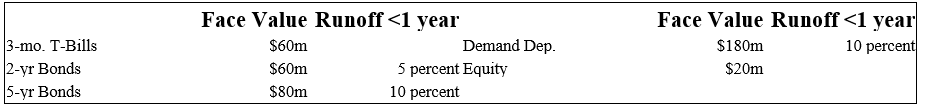 -What is the repricing gap if a 0 to 3 month maturity gap is used? Ignore runoffs.
 (Multiple Choice)
4.9/5 (74)
(74) Few DIs consider demand deposits to be "core" or long-term sources of funds.
(True/False)
4.9/5 (76)
(76) Hadbucks National Bank current balance sheet appears below. All assets and liabilities are currently priced at par and pay interest annually.
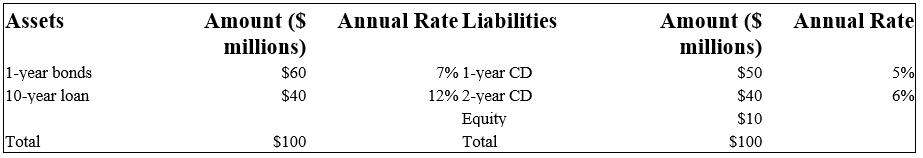 -What is this FI's maturity gap?
 (Multiple Choice)
4.9/5 (91)
(91) Can the FI immunize itself from interest rate risk exposure by setting the maturity gap equal to zero?
(Multiple Choice)
4.9/5 (84)
(84) The gap ratio is useful because it indicates the scale of the interest rate exposure by dividing the gap by the asset size of the institution.
(True/False)
4.8/5 (87)
(87) Overaggregation within maturity buckets using the repricing model causes inaccurate accounting of asset and liability cash flows and,ultimately,net interest income.
(True/False)
4.7/5 (83)
(83) What does Gotbucks Bank's 91-day gap positions reveal about the bank management's interest rate forecasts and the bank's interest rate risk exposure?
(Multiple Choice)
4.8/5 (81)
(81) The balance sheet of XYZ Bank appears below. All figures in millions of U.S. dollars.
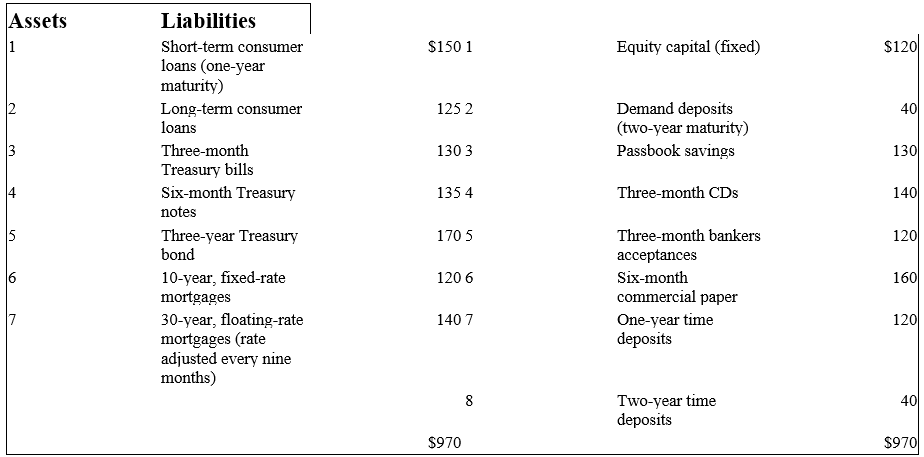 -The gap ratio is
 (Multiple Choice)
4.9/5 (84)
(84) If the average maturity of assets is 5 years and the average maturity of liabilities is 7 years,then the FI has no interest rate risk exposure.
(True/False)
4.9/5 (72)
(72) When the Fed finds it necessary to slow economic activity,it allows interest rates to fall.
(True/False)
4.9/5 (76)
(76) If the chosen maturity buckets have a time period that is too long,the repricing model may produce inaccurate results because
(Multiple Choice)
4.9/5 (69)
(69) Is the bank exposed to interest rate increases or decreases and why?
(Multiple Choice)
4.9/5 (76)
(76) For a given change in interest rates,fixed-rate assets with long-term maturities will have smaller changes in price than assets with shorter maturities.
(True/False)
4.8/5 (77)
(77) The market value of a fixed-rate liability will decrease as interest rates rise,just as the market value of a fixed-rate asset will decrease as interest rates rise.
(True/False)
4.8/5 (64)
(64) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)