



 Chat with AI
Exam 8: Interest Rate Risk I

Exam 1: Why Are Financial Institutions Special100 Questions
Exam 2: Financial Services: Depository Institutions226 Questions
Exam 3: Financial Services: Finance Companies82 Questions
Exam 4: Financial Services: Securities Firms and Investment Banks119 Questions
Exam 5: Financial Services: Mutual Fund and Hedge Fund Companies129 Questions
Exam 6: Financial Services: Insurance Companies124 Questions
Exam 7: Risks of Financial Institutions128 Questions
Exam 8: Interest Rate Risk I124 Questions
Exam 9: Interest Rate Risk II124 Questions
Exam 10: Credit Risk: Individual Loan Risk119 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk65 Questions
Exam 12: Liquidity Risk108 Questions
Exam 13: Foreign Exchange Risk109 Questions
Exam 14: Sovereign Risk94 Questions
Exam 15: Market Risk104 Questions
Exam 16: Off-Balance-Sheet Risk109 Questions
Exam 17: Technology and Other Operational Risks113 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees108 Questions
Exam 20: Capital Adequacy139 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards130 Questions
Exam 23: Options, Caps, Floors, and Collars120 Questions
Exam 24: Swaps104 Questions
Exam 25: Loan Sales96 Questions
Exam 26: Securitization120 Questions
Select questions type


If interest rates decrease 50 basis points for an FI that has a gap of +$5 million,the expected change in net interest income is
(Multiple Choice)
4.9/5  (70)
(70) The balance sheet of XYZ Bank appears below. All figures in millions of U.S. dollars.
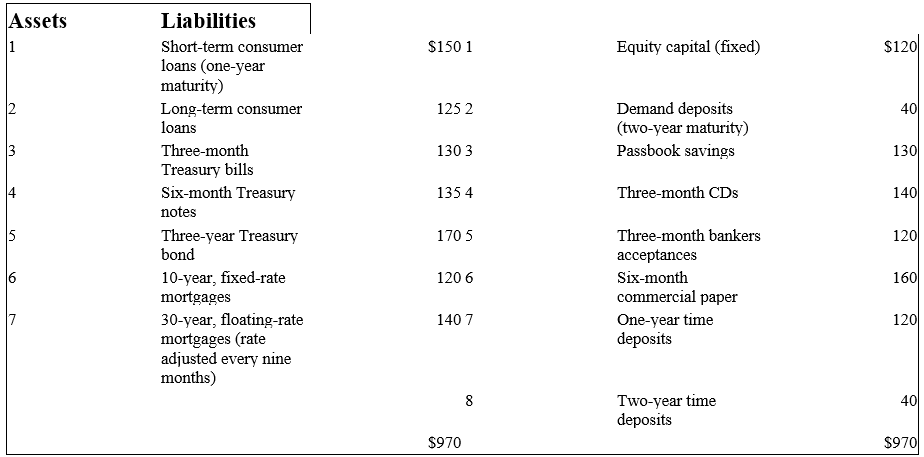 -Total one-year rate-sensitive liabilities is
 (Multiple Choice)
4.9/5 (68)
(68) A positive gap implies that an increase in interest rates will cause _______ in net interest income.
(Multiple Choice)
4.9/5 (82)
(82) The following are the assets and liabilities of a government security dealer.
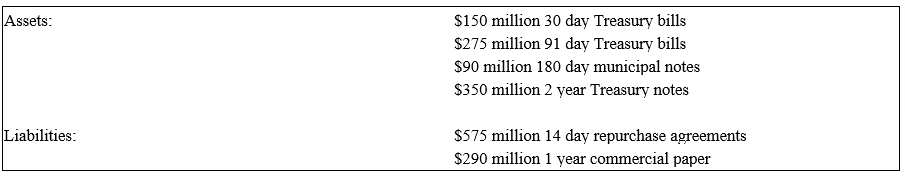 -Use the repricing model to determine the funding gap for a maturity bucket of 365 days.
 (Multiple Choice)
4.7/5 (87)
(87) What is the change in the value of its liabilities if all interest rates decrease by 1 percent?
(Multiple Choice)
4.9/5 (68)
(68) A bank with a negative repricing (or funding)gap faces refinancing risk.
(True/False)
4.8/5 (77)
(77) One reason to include demand deposits when estimating a bank's repricing gap is because rising interest rates could lead to high withdrawals from these accounts.
(True/False)
5.0/5 (72)
(72) An FI finances a $250,000 2-year fixed-rate loan with a $200,000 1-year fixed-rate CD.Use the repricing model to determine (a)the FI's repricing (or funding)gap using a 1-year maturity bucket,and (b)the impact of a 100 basis point (0.01)decrease in interest rates on the FI's annual net interest income?
(Multiple Choice)
4.8/5 (68)
(68) If interest rates increase 75 basis points for an FI that has a gap of -$15 million,the expected change in net interest income is
(Multiple Choice)
4.9/5 (72)
(72) The repricing model ignores market value effects of interest rate changes.
(True/False)
4.7/5 (89)
(89) Hadbucks National Bank current balance sheet appears below. All assets and liabilities are currently priced at par and pay interest annually.
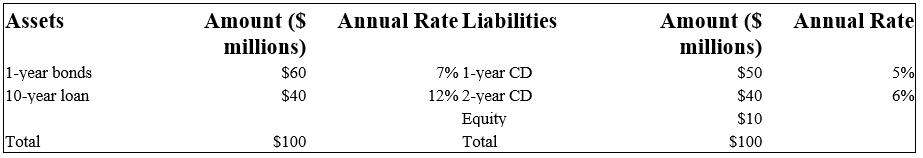 -What is market value of the one-year CD if all market interest rates increase by 2 percent?
 (Multiple Choice)
4.9/5 (73)
(73) The repricing gap does not accurately measure FI interest rate risk exposure because
(Multiple Choice)
4.8/5 (85)
(85) The maturity of a portfolio of assets or liabilities is a weighted average of the maturities of the assets or liabilities that comprise that portfolio.
(True/False)
4.9/5 (83)
(83) If interest rates decrease 40 basis points (0.40 percent)for an FI that has a cumulative gap of -$25 million,the expected change in net interest income is
(Multiple Choice)
4.9/5 (69)
(69) A bank that finances long-term fixed-rate mortgages with short-term deposits is exposed to
(Multiple Choice)
4.9/5 (79)
(79) The gap ratio expresses the reprice gap for a given time period as a percentage of
(Multiple Choice)
4.8/5 (81)
(81) Duration Bank has the following assets and liabilities as of year-end. All assets and liabilities are currently priced at par and pay interest annually. 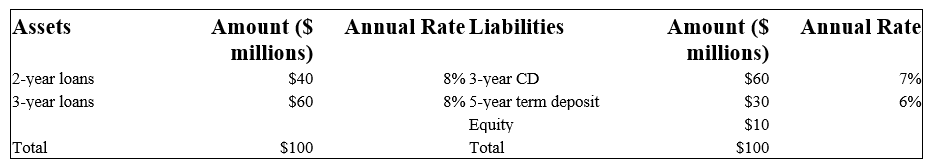 -What is the weighted average maturity of the assets of the FI?
 (Multiple Choice)
4.8/5 (88)
(88) What is the impact over the next 30 days on the dealer's net interest income if all interest rates increase by 50 basis points?
(Multiple Choice)
4.9/5 (91)
(91) The average maturity of the liabilities of an FI's balance sheet is equal to
(Multiple Choice)
4.7/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)