



 Chat with AI
Exam 8: Management of Transaction Exposure

Exam 1: Globalization and the Multinational Firm100 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange98 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure98 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market103 Questions
Exam 12: International Bond Market100 Questions
Exam 13: International Equity Markets100 Questions
Exam 14: Interest Rate and Currency Swaps100 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital100 Questions
Exam 18: International Capital Budgeting102 Questions
Exam 19: Multinational Cash Management100 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing99 Questions
Select questions type


XYZ Corporation, located in the United States, has an accounts payable obligation of ¥750 million payable in one year to a bank in Tokyo. The current spot rate is ¥116/$1.00 and the one year forward rate is ¥109/$1.00. The annual interest rate is 3 percent in Japan and 6 percent in the United States. XYZ can also buy a one-year call option on yen at the strike price of $0.0086 per yen for a premium of 0.012 cent per yen. The future dollar cost of meeting this obligation using the money market hedge is
(Multiple Choice)
4.8/5  (76)
(76) A Japanese EXPORTER has a €1,000,000 receivable due in one year. Spot and forward exchange rate data is given in the table:  The one-year risk free rates are i$ = 4.03%; i€ = 6.05%; and i¥ = 1%. Detail a strategy using forward contract that will hedge exchange rate risk.
 (Multiple Choice)
4.9/5 (74)
(74) Your firm is a U.K.-based importer of bicycles. You have placed an order with an Italian firm for €1,000,000 worth of bicycles. Payment (in euro) is due in 12 months. Use a money market hedge to redenominate this one-year receivable into a pound-denominated receivable with a one-year maturity.  The following were computed without rounding. Select the answer closest to yours.
 (Multiple Choice)
5.0/5 (90)
(90) Suppose that the exchange rate is €1.25 = £1.00. Options (calls and puts) are available on the Philadelphia exchange in units of €10,000 with strike prices of $1.60/€1.00.
Options (calls and puts) are available on the Philadelphia exchange in units of £10,000 with strike prices of $2.00/£1.00.
For a U.S. firm to hedge a €100,000 payable,
(Multiple Choice)
4.9/5 (80)
(80) Your firm is a Swiss exporter of bicycles. You have sold an order to a British firm for £1,000,000 worth of bicycles. Payment from the British firm (in pounds sterling) is due in 12 months. Detail a strategy using futures contracts that will hedge your exchange rate risk. Have an estimate of how many contracts of what type and maturity. 
(Multiple Choice)
4.8/5 (77)
(77) Your firm is a U.K.-based importer of bicycles. You have placed an order with an Italian firm for €1,000,000 worth of bicycles. Payment (in euro) is due in 12 months. Detail a strategy using futures contracts that will hedge your exchange rate risk. Have an estimate of how many contracts of what type and maturity. 
(Multiple Choice)
4.9/5 (78)
(78) ABC Inc., an exporting firm, expects to earn $20 million if the dollar depreciates, but only $10 million if the dollar appreciates. Assume that the dollar has an equal chance of appreciating or depreciating. Calculate the expected tax of ABC if it is operating in a foreign country that has progressive corporate taxes as shown below: Corporate income tax rate = 15% for the first $7,500,000.
Corporate income tax rate = 30% for earnings exceeding $7,500,000.
(Multiple Choice)
4.9/5 (86)
(86) XYZ Corporation, located in the United States, has an accounts payable obligation of ¥750 million payable in one year to a bank in Tokyo. The current spot rate is ¥116/$1.00 and the one year forward rate is ¥109/$1.00. The annual interest rate is 3 percent in Japan and 6 percent in the United States. XYZ can also buy a one-year call option on yen at the strike price of $0.0086 per yen for a premium of 0.012 cent per yen. Assume that the forward rate is the best predictor of the future spot rate. The future dollar cost of meeting this obligation using the option hedge is
(Multiple Choice)
4.8/5 (76)
(76) Your firm is a U.K.-based exporter of bicycles. You have sold an order to a Swiss firm for SFr. 1,000,000 worth of bicycles. Payment from the Swiss firm (in Swiss francs) is due in 12 months. Detail a strategy using futures contracts that will hedge your exchange rate risk. Have an estimate of how many contracts of what type and maturity. 
(Multiple Choice)
4.8/5 (85)
(85) Your firm is a U.K.-based exporter of bicycles. You have sold an order to a Swiss firm for SFr. 1,000,000 worth of bicycles. Payment from the Swiss firm (in Swiss francs) is due in 12 months. Use a money market hedge to redenominate this one-year receivable into a euro-denominated receivable with a one-year maturity.  The following were computed without rounding. Select the answer closest to yours.
 (Multiple Choice)
4.9/5 (77)
(77) If you own a foreign currency denominated bond, you can hedge with
(Multiple Choice)
4.8/5 (78)
(78) Your firm is an Italian exporter of bicycles. You have sold an order to a Swiss firm for SFr. 2,000,000 worth of bicycles. Payment from the customer (in Swiss francs) is due in 12 months. Detail a strategy using futures contracts that will hedge your exchange rate risk. Have an estimate of how many contracts of what type and maturity. 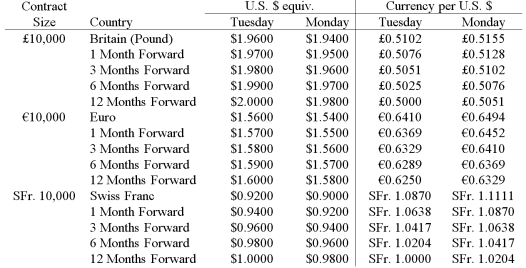
(Multiple Choice)
4.8/5 (74)
(74) Your firm is a Swiss importer of bicycles. You have placed an order with an Italian firm for €1,000,000 worth of bicycles. Payment (in euro) is due in 12 months. Detail a strategy using futures contracts that will hedge your exchange rate risk. Have an estimate of how many contracts of what type and maturity. 
(Multiple Choice)
5.0/5 (81)
(81) Suppose that the exchange rate is €1.25 = £1.00. Options (calls and puts) are available on the London exchange in units of €10,000 with strike prices of £0.80 = €1.00. Options (calls and puts) are available on the Frankfurt exchange in units of £10,000 with strike prices of €1.25 = £1.00. For a French firm to hedge a £100,000 receivable,
(Multiple Choice)
4.9/5 (98)
(98) Suppose that the exchange rate is €1.25 = £1.00. Options (calls and puts) are available on the London exchange in units of €10,000 with strike prices of £0.80 = €1.00.
Options (calls and puts) are available on the Frankfurt exchange in units of £10,000 with strike prices of €1.25 = £1.00.
For an Italian firm to hedge a £100,000 payable,
(Multiple Choice)
4.7/5 (85)
(85) An exporter faced with exposure to a depreciating currency can reduce transaction exposure with a strategy of
(Multiple Choice)
4.7/5 (89)
(89) Your firm has a British customer that is willing to place a $1 million order, but wants to pay in pounds instead of dollars. The spot exchange rate is $1.85 = £1.00 and the one-year forward rate is $1.90 = £1.00. The lead time on the order is such that payment is due in one year. What is the fairest exchange rate to use?
(Multiple Choice)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)