



 Chat with AI
Exam 11: International Banking and Money Market

Exam 1: Globalization and the Multinational Firm100 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange98 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure98 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market103 Questions
Exam 12: International Bond Market100 Questions
Exam 13: International Equity Markets100 Questions
Exam 14: Interest Rate and Currency Swaps100 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital100 Questions
Exam 18: International Capital Budgeting102 Questions
Exam 19: Multinational Cash Management100 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing99 Questions
Select questions type


A bank bought a "three against six" $5,000,000 FRA for a three-month period beginning three months from today and ending six months from today. The reason that the bank bought the FRA was to hedge: the bank accepted a 3-month deposit and made a six-month loan. The agreement rate with the seller is 5.0%. Assume that three months from today the settlement rate is 5.25%. Who pays whom? How much? When? The actual number of days in the FRA is 90.
(Multiple Choice)
4.9/5  (86)
(86) A bank may establish a multinational operation for the reason of wholesale defensive strategy. The underlying rationale being that
(Multiple Choice)
4.8/5 (75)
(75) Consider the balance sheets of Bank A and Bank B. Bank A is in London, Bank B is in New York. The current exchange rate is £1.00 = $2.00. Show the correct balances in each account if a currency trader employed at Bank A buys £50,000 from a currency trader at bank B for $100,000 using its correspondent relationship with Bank B.. 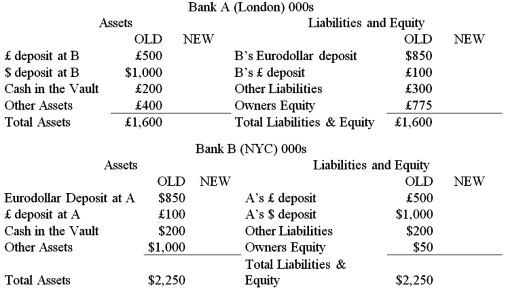
(Essay)
5.0/5 (70)
(70) A DECREASE in the implied three-month LIBOR yield causes Eurodollar futures price
(Multiple Choice)
4.8/5 (85)
(85) The current exchange rate is €1.00 = $1.50. Compute the correct balances in Bank A's correspondent account(s) with bank B if a currency trader employed at Bank A buys €100,000 from a currency trader at bank B for $150,000 using its correspondent relationship with Bank B.
(Multiple Choice)
4.7/5 (81)
(81) A bank may establish a multinational operation for the reason of low marginal costs. The underlying rationale being that
(Multiple Choice)
4.9/5 (86)
(86) Consider the balance sheets of Bank A and Bank B. Bank A is in London, Bank B is in New York. The current exchange rate is £1.00 = $2.00. Show the correct balances in each account if a currency trader employed at Bank A buys £45,000 from a currency trader at bank B for $90,000 using its correspondent relationship with Bank B. 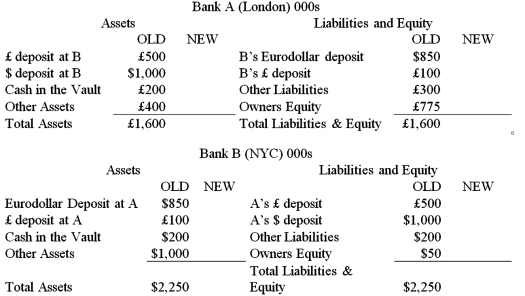
(Essay)
4.8/5 (83)
(83) ABC International can borrow $4,000,000 at LIBOR plus a lending margin of .65 percent per annum on a three-month rollover basis from Barclays in London. Three month LIBOR is currently 5.5 percent. Suppose that over the second three-month interval LIBOR falls to 5.0 percent. How much will ABC pay in interest to Barclays over the six-month period for the Eurodollar loan?
(Multiple Choice)
5.0/5 (76)
(76) A domestic bank that follows a multinational client abroad to preserve that banking relationship
(Multiple Choice)
4.7/5 (73)
(73) A bank may establish a multinational operation for the reason of risk reduction. The underlying rationale being that
(Multiple Choice)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)