



 Chat with AI
Exam 12: International Bond Market

Exam 1: Globalization and the Multinational Firm100 Questions
Exam 2: International Monetary System100 Questions
Exam 3: Balance of Payments100 Questions
Exam 4: Corporate Governance Around the World100 Questions
Exam 5: The Market for Foreign Exchange98 Questions
Exam 6: International Parity Relationships and Forecasting Foreign Exchange Rates100 Questions
Exam 7: Futures and Options on Foreign Exchange100 Questions
Exam 8: Management of Transaction Exposure98 Questions
Exam 9: Management of Economic Exposure100 Questions
Exam 10: Management of Translation Exposure81 Questions
Exam 11: International Banking and Money Market103 Questions
Exam 12: International Bond Market100 Questions
Exam 13: International Equity Markets100 Questions
Exam 14: Interest Rate and Currency Swaps100 Questions
Exam 15: International Portfolio Investment101 Questions
Exam 16: Foreign Direct Investment and Cross-Border Acquisitions100 Questions
Exam 17: International Capital Structure and the Cost of Capital100 Questions
Exam 18: International Capital Budgeting102 Questions
Exam 19: Multinational Cash Management100 Questions
Exam 20: International Trade Finance100 Questions
Exam 21: International Tax Environment and Transfer Pricing99 Questions
Select questions type


Two major clearing systems for international bond transactions are
(Multiple Choice)
4.9/5  (87)
(87) In contrast to many domestic bonds, which make _________ coupon payments, coupon interest on Eurobonds is typically paid _________.
(Multiple Choice)
4.9/5 (91)
(91) Assuming that the bond sells at par, the implicit $/£ exchange rate at maturity of a British pound-U.S. dollar dual currency bonds that pay £581.40 at maturity per $1,000 of par value is:
(Multiple Choice)
5.0/5 (95)
(95) Eurobond market makers and dealers are members of the ______________, a self-regulatory body based in Zurich.
(Multiple Choice)
4.8/5 (77)
(77) Consider a British pound-U.S. dollar dual currency bonds that pay £581.40 at maturity per $1,000 of par value. If at maturity, the exchange rate is $1.90 = £1.00,
(Multiple Choice)
4.8/5 (78)
(78) In any given year, about what percent of new international bonds are likely to be Eurobonds rather than foreign bonds?
(Multiple Choice)
4.7/5 (94)
(94) Find the value of a three-year dual currency bond with annual coupons (paid in U.S. dollars at a 5 percent coupon rate) that pays £500 per $1,000 par value at maturity. The cash flows of the bond are: 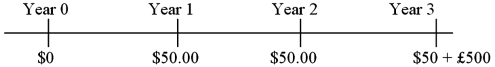 The dollar-based yield to maturity is i$ = 3%; the spot exchange rate is $1.80 = £1.00; expected inflation over the next three years is π$ = 2% in the U.S. and π£ = 3% in the U.K.
 (Multiple Choice)
4.7/5 (74)
(74) A convertible bond pays interest annually at a coupon rate of 5% on a par value of $1,000. The bond has 10 years maturity remaining and the discount rate on other-wise identical non-convertible debt is 5%. The bond is convertible into shares of common stock at a conversion price of $25 per share (i.e. the bond is exchangeable for 40 shares). Today's closing stock price was $31.25. What is the floor value of this bond?
(Multiple Choice)
4.9/5 (71)
(71) A five-year, 4 percent Euroyen bond sells at par. A comparable risk five-year, 5.5 percent yen/dollar dual-currency bond pays $833.33 at maturity per ¥100,000 of face value. It sells for ¥110,000. What is the implied ¥/$ exchange rate at maturity?
(Multiple Choice)
4.9/5 (63)
(63) Six-month U.S. dollar LIBOR is currently 4.375%; your firm issued floating-rate notes indexed to six-month U.S. dollar LIBOR plus 50 basis points. What is the amount of the next semi-annual coupon payment per U.S. $1,000 of face value?
(Multiple Choice)
4.8/5 (74)
(74) Find the value today of a 2-year dual currency bond with annual coupons (paid in U.S. dollars at a 5 percent coupon rate) that pays £500 per $1,000 par value at maturity. The cash flows of the bond are: 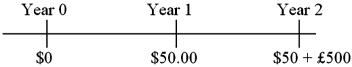 The dollar-based yield to maturity is i$ = 3%; the spot exchange rate is $1.80 = £1.00; the pound-based yield to maturity is i£ = 4%.
 (Multiple Choice)
4.9/5 (82)
(82) A five-year, 4 percent euro denominated bond sells at par. A comparable risk five-year, 5.5 percent euro/dollar dual-currency bond pays $1,500 at maturity per €1,000 of face value. It sells for €1,250. What is the implied $/€ exchange rate at maturity?
(Multiple Choice)
4.8/5 (85)
(85) Zero-coupon bonds issued in 2006 are due in 2016. If they were originally sold at 55 percent of face value, the implied yield to maturity at issuance is
(Multiple Choice)
4.8/5 (79)
(79) A 1-year, 4 percent pound denominated bond sells at par. A comparable risk 1-year, 5.5 percent pound/dollar dual-currency bond pays $2,000 at maturity per £1,000 of face value. It sells for £900. What is the implied direct $/£ exchange rate at maturity?
(Multiple Choice)
4.7/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)