



 Chat with AI
Exam 7: Capital Pricing and Arbitrage Pricing Theory

Exam 1: Investments: Background and Issues55 Questions
Exam 2: Asset Classes and Financial Instruments59 Questions
Exam 3: Securities Markets60 Questions
Exam 4: Managed Funds and Other Investment Companies60 Questions
Exam 5: Risk and Return: Past and Prologue58 Questions
Exam 6: Efficient Diversification56 Questions
Exam 7: Capital Pricing and Arbitrage Pricing Theory59 Questions
Exam 8: The Efficient Market Hypothesis and Behavioral Finance60 Questions
Exam 9: Bond Prices and Yields58 Questions
Exam 10: Managing Bond Portfolios60 Questions
Exam 11: Equity Valuation60 Questions
Exam 12: Macroeconomic and Industry Analysis58 Questions
Exam 13: Financial Statement Analysis55 Questions
Exam 14: Options and Risk Management60 Questions
Exam 15: Futures and Risk Management60 Questions
Exam 16: Investors and the Investment Process60 Questions
Exam 17: Hedge Funds60 Questions
Exam 18: Portfolio Performance Evaluation54 Questions
Select questions type


You consider buying a share at a price of $25. The share is expected to pay a dividend of $1.50 next year and your advisory service tells you that you can expect to sell the share in one year for $28. The share's beta is 1.1, rf is 6% and E[rm] = 16%. What is the share's abnormal return?
(Multiple Choice)
4.8/5  (80)
(80) Two investment advisors are comparing performance. Advisor A averaged a 20% return with a portfolio beta of 1.5 and Advisor B averaged a 15% return with a portfolio beta of 1.2. If the T-bond rate was 5% and the market return during the period was 13%, which advisor was the better share picker?
(Multiple Choice)
4.9/5 (89)
(89) The graph of the relationship between expected return and beta in the CAPM context is called the ________.
(Multiple Choice)
4.9/5 (67)
(67) If enough investors decide to purchase shares they are likely to drive up share prices thereby causing ________ and ________.
(Multiple Choice)
4.9/5 (74)
(74) Security A has an expected rate of return of 12% and a beta of 1.10. The market expected rate of return is 8% and the risk-free rate is 5%. The alpha of the share is ________.
(Multiple Choice)
5.0/5 (83)
(83) If the simple CAPM is valid and all portfolios are priced correctly, which of the situations below are possible?
Consider each situation independently and assume the risk-free rate is 5%. 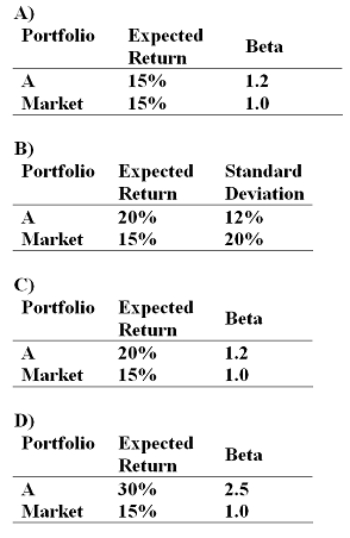
(Multiple Choice)
4.9/5 (92)
(92) Consider the CAPM. The risk-free rate is 5% and the expected return on the market is 15%. What is the beta on a share with an expected return of 17%?
(Multiple Choice)
4.7/5 (75)
(75) The measure of unsystematic risk can be found from an index model as ________.
(Multiple Choice)
4.8/5 (85)
(85) The SML is valid for ________ and the CML is valid for ________.
(Multiple Choice)
4.8/5 (80)
(80) In his famous critique of the CAPM, Roll argued that the CAPM ________.
(Multiple Choice)
4.8/5 (84)
(84) The expected return on the market is the risk-free rate plus the ________.
(Multiple Choice)
4.9/5 (84)
(84) One of the main problems with the arbitrage pricing theory is ________.
(Multiple Choice)
4.8/5 (72)
(72) What is the expected return on a share with a beta of 0.8, given a risk-free rate of 3.5% and an expected market return of 15.5%?
(Multiple Choice)
4.9/5 (62)
(62) According to the CAPM, investors are compensated for all but which of the following?
(Multiple Choice)
4.8/5 (77)
(77) The most significant conceptual difference between the arbitrage pricing theory (APT) and the capital asset pricing model (CAPM) is that the CAPM ________.
(Multiple Choice)
4.9/5 (75)
(75) In a simple CAPM world which of the following statements is/are correct?
I. All investors will choose to hold the market portfolio, which includes all risky assets in the world
II. Investors' complete portfolio will vary depending on their risk aversion
III. The return per unit of risk will be identical for all individual assets
IV. The market portfolio will be on the efficient frontier and it will be the optimal risky portfolio
(Multiple Choice)
4.7/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)