



 Chat with AI
Exam 7: Capital Pricing and Arbitrage Pricing Theory

Exam 1: Investments: Background and Issues55 Questions
Exam 2: Asset Classes and Financial Instruments59 Questions
Exam 3: Securities Markets60 Questions
Exam 4: Managed Funds and Other Investment Companies60 Questions
Exam 5: Risk and Return: Past and Prologue58 Questions
Exam 6: Efficient Diversification56 Questions
Exam 7: Capital Pricing and Arbitrage Pricing Theory59 Questions
Exam 8: The Efficient Market Hypothesis and Behavioral Finance60 Questions
Exam 9: Bond Prices and Yields58 Questions
Exam 10: Managing Bond Portfolios60 Questions
Exam 11: Equity Valuation60 Questions
Exam 12: Macroeconomic and Industry Analysis58 Questions
Exam 13: Financial Statement Analysis55 Questions
Exam 14: Options and Risk Management60 Questions
Exam 15: Futures and Risk Management60 Questions
Exam 16: Investors and the Investment Process60 Questions
Exam 17: Hedge Funds60 Questions
Exam 18: Portfolio Performance Evaluation54 Questions
Select questions type


The variance of the return on the market portfolio is .0400 and the expected return on the market portfolio is 20%. If the risk-free rate of return is 10%, the market degree of risk aversion, A, is ________.

Free
(Multiple Choice)
4.9/5  (80)
(80) Correct Answer: Verified
B
The two factor model on a share provides a risk premium for exposure to market risk of 9%, a risk premium for exposure to interest rate of (-1.3%), and a risk-free rate of 3.5%. What is the expected return on the share?
Free
(Multiple Choice)
4.7/5 (86)
(86) Correct Answer:Verified
VerifiedA
A share has a beta of 1.3. The unsystematic risk of this share is ________ the stock market as a whole.
Free
(Multiple Choice)
4.8/5 (77)
(77) Correct Answer:Verified
VerifiedA
According to capital asset pricing theory, the key determinant of portfolio returns is ________.
(Multiple Choice)
4.9/5 (89)
(89) Using the index model, the alpha of a share is 3.0%, the beta if 1.1 and the market return is 10%. What is the residual given an actual return of 15%?
(Multiple Choice)
4.8/5 (81)
(81) If the beta of the market index is 1.0 and the standard deviation of the market index increases from 12% to 18%, what is the new beta of the market index?
(Multiple Choice)
4.8/5 (80)
(80) The two factor model on a share provides a risk premium for exposure to market risk of 12%, a risk premium for exposure to silver commodity prices of 3.5% and a risk-free rate of 4.0%. What is the expected return on the share?
(Multiple Choice)
4.9/5 (92)
(92) If all investors become more risk averse the SML will ________ and share prices will ________.
(Multiple Choice)
4.7/5 (86)
(86) There are two independent economic factors M1 and M2. The risk-free rate is 5% and all shares have independent firm-specific components with a standard deviation of 25%. Portfolios A and B are well diversified. Given the data below which equation provides the correct pricing model? 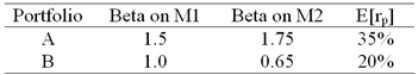
(Multiple Choice)
4.8/5 (87)
(87) The risk-free rate is 4%. The expected market rate of return is 11%. If you expect share X with a beta of .8 to offer a rate of return of 12 per cent, then you should ________.
(Multiple Choice)
4.9/5 (86)
(86) Assume that both X and Y are well-diversified portfolios and the risk-free rate is 8%. Portfolio X has an expected return of 14% and a beta of 1.00. Portfolio Y has an expected return of 9.5% and a beta of 0.25. In this situation, you would conclude that portfolios X and Y ________.
(Multiple Choice)
4.8/5 (82)
(82) In a well-diversified portfolio, ________ risk is negligible.
(Multiple Choice)
4.9/5 (65)
(65) Which of the following are assumptions of the simple CAPM model?
I. Individual trades of investors do not affect a share's price
II. All investors plan for one identical holding period
III. All investors analyse securities in the same way and share the same economic view of the world
IV. All investors have the same level of risk aversion
(Multiple Choice)
4.8/5 (93)
(93) According to the capital asset pricing model, fairly priced securities have ________.
(Multiple Choice)
4.9/5 (73)
(73) The measure of risk used in the Capital Asset Pricing Model is ________.
(Multiple Choice)
4.8/5 (81)
(81) Consider the single factor APT. Portfolio A has a beta of 0.2 and an expected return of 13%. Portfolio B has a beta of 0.4 and an expected return of 15%. The risk-free rate of return is 10%. If you wanted to take advantage of an arbitrage opportunity, you should take a short position in portfolio ________ and a long position in portfolio ________.
(Multiple Choice)
4.8/5 (81)
(81) Consider the multi-factor APT with two factors. Portfolio A has a beta of 0.5 on factor 1 and a beta of 1.25 on factor 2. The risk premiums on the factors 1 and 2 portfolios are 1% and 7% respectively. The risk-free rate of return is 7%. The expected return on portfolio A is ________ if no arbitrage opportunities exist.
(Multiple Choice)
4.7/5 (70)
(70) The risk premium for exposure to aluminum commodity prices is 4% and the firm has a beta relative to aluminum commodity prices of 0.6. The risk premium for exposure to GDP changes is 6% and the firm has a beta relative to GDP of 1.2. If the risk-free rate is 4.0%, what is the expected return on this share?
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)