



 Chat with AI
Exam 14: Options and Risk Management

Exam 1: Investments: Background and Issues55 Questions
Exam 2: Asset Classes and Financial Instruments59 Questions
Exam 3: Securities Markets60 Questions
Exam 4: Managed Funds and Other Investment Companies60 Questions
Exam 5: Risk and Return: Past and Prologue58 Questions
Exam 6: Efficient Diversification56 Questions
Exam 7: Capital Pricing and Arbitrage Pricing Theory59 Questions
Exam 8: The Efficient Market Hypothesis and Behavioral Finance60 Questions
Exam 9: Bond Prices and Yields58 Questions
Exam 10: Managing Bond Portfolios60 Questions
Exam 11: Equity Valuation60 Questions
Exam 12: Macroeconomic and Industry Analysis58 Questions
Exam 13: Financial Statement Analysis55 Questions
Exam 14: Options and Risk Management60 Questions
Exam 15: Futures and Risk Management60 Questions
Exam 16: Investors and the Investment Process60 Questions
Exam 17: Hedge Funds60 Questions
Exam 18: Portfolio Performance Evaluation54 Questions
Select questions type


Which of the following is a true statement?

Free
(Multiple Choice)
4.8/5  (77)
(77) Correct Answer: Verified
A
You buy a call option on Merritt Corp. with an exercise price of $50 and an expiration date in July and write a call option on Merritt Corp. with an exercise price of $55 with an expiration date in July. This is called a ________.
Free
(Multiple Choice)
4.8/5 (81)
(81) Correct Answer:Verified
VerifiedD
If you know that a call option will be profitably exercised then the Black-Scholes model price will simplify to ________.
Free
(Multiple Choice)
4.9/5 (77)
(77) Correct Answer:Verified
VerifiedC
The 14 September 2009 price quotation for a Boeing call option with a strike price of $50 due to expire in November is $3.50 while the share price of Boeing is $51. The premium on one Boeing November 50 call contract is ________.
(Multiple Choice)
4.8/5 (83)
(83) The common stock of the Avalon Corporation has been trading in a narrow range around $40 per share for months and you believe it is going to stay in that range for the next three months. The price of a three-month put option with an exercise price of $40 is $3 and a call with the same expiration date and exercise price sells for $4. What would be a simple options strategy using a put and a call to exploit your conviction about the share price's future movement?
(Multiple Choice)
4.9/5 (92)
(92) If a share price increases, the price of a put option on the share will ________ and the price of a call option on the share will ________.
(Multiple Choice)
5.0/5 (69)
(69) Before expiration the time value of an out-of-the money share option is ________.
(Multiple Choice)
4.9/5 (84)
(84) An investor purchases a long call at a price of $2.50. The expiration price is $35.00. If the current share price is $35.10, what is the break-even point for the investor?
(Multiple Choice)
4.8/5 (81)
(81) Hedge ratios for long call position are ________ and hedge ratios for long put positions are ________.
(Multiple Choice)
4.9/5 (92)
(92) You invest in the share of Rayleigh Corp. and write a call option on Rayleigh Corp. This strategy is called a ________.
(Multiple Choice)
4.9/5 (77)
(77) All else the same, an American style option will be ________ valuable than a ________ style option.
(Multiple Choice)
4.8/5 (79)
(79) A put on Sanders stock with a strike price of $35 is priced at $2 per share while a call with a strike price of $35 is priced at $3.50. The maximum per share loss to the writer of an uncovered put is ________ and the maximum per share gain to the writer of an uncovered call is ________.
(Multiple Choice)
4.8/5 (69)
(69) A one dollar increase in a share's price would result in ________ in the call option's value of ________ than one dollar.
(Multiple Choice)
4.9/5 (98)
(98) The share price of Ajax Inc. is currently $105. The share price a year from now will be either $130 or $90 with equal probabilities. The interest rate at which investors can borrow is 10%. Using the binomial OPM, the value of a call option with an exercise price of $110 and an expiration date one year from now should be worth ________ today.
(Multiple Choice)
4.8/5 (65)
(65) The current share price of Alcoa is $70 and the share does not pay dividends. The instantaneous risk free rate of return is 6%. The instantaneous standard deviation of Alcoa's shares is 40%. A put option on this share with an exercise price of $75 and an expiration date 30 days from now. According to the Black-Scholes OPM, you should hold ________ shares of stock per 100 put options to hedge your risk.
(Multiple Choice)
4.9/5 (92)
(92) You buy a call option and a put option on General Electric. Both the call option and the put option have the same exercise price and expiration date. This strategy is called a ________.
(Multiple Choice)
4.8/5 (81)
(81) You are cautiously bullish on the common share of the Wildwood Corporation over the next several months. The current price of the share is $50 per share. You want to establish a bullish money spread to help limit the cost of your option position. You find the following option quotes: 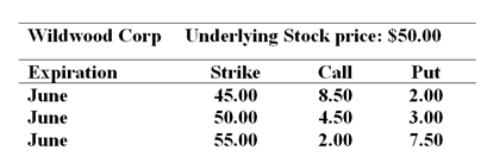 Ignoring commissions, the cost to establish the bull money spread with calls would be ________.
 (Multiple Choice)
4.9/5 (89)
(89) You are considering purchasing a put option on a share with a current price of $33. The exercise price is $35 and the price of the corresponding call option is $2.25. According to the put-call parity theorem, if the risk-free rate of interest is 4% and there are 90 days until expiration, the value of the put should be ________.
(Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)