



 Chat with AI
Exam 7: Capital Pricing and Arbitrage Pricing Theory

Exam 1: Investments: Background and Issues55 Questions
Exam 2: Asset Classes and Financial Instruments59 Questions
Exam 3: Securities Markets60 Questions
Exam 4: Managed Funds and Other Investment Companies60 Questions
Exam 5: Risk and Return: Past and Prologue58 Questions
Exam 6: Efficient Diversification56 Questions
Exam 7: Capital Pricing and Arbitrage Pricing Theory59 Questions
Exam 8: The Efficient Market Hypothesis and Behavioral Finance60 Questions
Exam 9: Bond Prices and Yields58 Questions
Exam 10: Managing Bond Portfolios60 Questions
Exam 11: Equity Valuation60 Questions
Exam 12: Macroeconomic and Industry Analysis58 Questions
Exam 13: Financial Statement Analysis55 Questions
Exam 14: Options and Risk Management60 Questions
Exam 15: Futures and Risk Management60 Questions
Exam 16: Investors and the Investment Process60 Questions
Exam 17: Hedge Funds60 Questions
Exam 18: Portfolio Performance Evaluation54 Questions
Select questions type


Research has identified two systematic factors that affect US stock (share) returns. The factors are growth in industrial production and changes in long term interest rates. Industrial production growth is expected to be 3% and long term interest rates are expected to increase by 1%. You are analysing a share that has a beta of 1.2 on the industrial production factor and 0.5 on the interest rate factor. It currently has an expected return of 12%. However, if industrial production actually grows 5% and interest rates drop 2% what is your best guess of the share's return?
(Multiple Choice)
4.8/5  (74)
(74) According to the CAPM, the risk premium an investor expects to receive on any share or portfolio is ________.
(Multiple Choice)
4.8/5 (80)
(80) In the context of the capital asset pricing model, the systematic measure of risk is captured by ________.
(Multiple Choice)
4.8/5 (80)
(80) You have a $50 000 portfolio consisting of Intel, GE and Con Edison. You put $20 000 in Intel, $12 000 in GE and the rest in Con Edison. Intel, GE and Con Edison have betas of 1.3, 1.0 and 0.8 respectively. What is your portfolio beta?
(Multiple Choice)
4.9/5 (85)
(85) Which of the following variables do Fama and French claim do a better job explaining share returns than beta?
I. Book to market ratio
II. Unexpected change in industrial production
III. Firm size
(Multiple Choice)
4.7/5 (76)
(76) Security X has an expected rate of return of 13% and a beta of 1.15. The risk-free rate is 5% and the market expected rate of return is 15%. According to the capital asset pricing model, security X is ________.
(Multiple Choice)
4.8/5 (68)
(68) An important characteristic of market equilibrium is ________.
(Multiple Choice)
4.8/5 (66)
(66) According to the CAPM, what is the market risk premium given an expected return on a security of 13.6%, a share beta of 1.2, and a risk-free interest rate of 4.0%?
(Multiple Choice)
4.8/5 (89)
(89) Consider the CAPM. The risk-free rate is 6% and the expected return on the market is 18%. What is the expected return on a share with a beta of 1.3?
(Multiple Choice)
4.9/5 (81)
(81) Standard deviation of portfolio returns is a measure of ________.
(Multiple Choice)
4.9/5 (76)
(76) According to the CAPM, what is the expected market return given an expected return on a security of 15.8%, a share beta of 1.2, and a risk-free interest rate of 5.0%?
(Multiple Choice)
4.9/5 (73)
(73) Investors require a risk premium as compensation for bearing ________.
(Multiple Choice)
4.9/5 (79)
(79) You run a regression of a share's returns versus a market index and find the following: 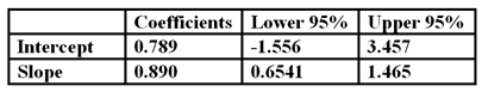 Based on the data you know that the share
 (Multiple Choice)
4.8/5 (71)
(71) The expected return on the market portfolio is 15%. The risk-free rate is 8%. The expected return on SDA Corp. common shares is 16%. The beta of SDA Corp. common shares is 1.25. Within the context of the capital asset pricing model, ________.
(Multiple Choice)
4.8/5 (72)
(72) Consider the one-factor APT. The variance of the return on the factor portfolio is .08. The beta of a well-diversified portfolio on the factor is 1.2. The variance of the return on the well-diversified portfolio is approximately ________.
(Multiple Choice)
5.0/5 (74)
(74) In a single factor market model the beta of a share ________.
(Multiple Choice)
4.9/5 (73)
(73) The risk premium for exposure to exchange rates is 5% and the firm has a beta relative to exchanges rates of 0.4. The risk premium for exposure to the consumer price index is -6% and the firm has a beta relative to the CPI of 0.8. If the risk-free rate is 3.0%, what is the expected return on this share?
(Multiple Choice)
4.9/5 (88)
(88) Consider the single factor APT. Portfolio A has a beta of 1.3 and an expected return of 21%. Portfolio B has a beta of 0.7 and an expected return of 17%. The risk-free rate of return is 8%. If you wanted to take advantage of an arbitrage opportunity, you should take a short position in portfolio ________ and a long position in portfolio ________.
(Multiple Choice)
4.8/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)