



 Chat with AI
Exam 7: Technology Production and Costs

Exam 1: Economics: Foundations and Models159 Questions
Exam 2: Choices and Trade-Offs in the Market192 Questions
Exam 3: Where Prices Come From: The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply224 Questions
Exam 5: Economic Efficiency, Government Price Setting and Taxes187 Questions
Exam 6: Consumer Choice and Behavioural Economics254 Questions
Exam 7: Technology Production and Costs301 Questions
Exam 8: Firms in Perfectly Competitive Markets269 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition: The Competitive Model in a More Realistic255 Questions
Exam 11: Oligopoly: Markets With Few Competitors186 Questions
Exam 12: The Markets for Labour and Other Factors of Production250 Questions
Exam 13: Comparative Advantage and the Gains From International Trade131 Questions
Exam 14: Government Intervention in the Market113 Questions
Exam 15: Externalities, Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy121 Questions
Select questions type


Explain why the marginal cost of production must increase if the marginal product of a variable resource is decreasing.
__________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
5.0/5  (69)
(69) Jill Johnson owns a pizzeria.She currently produces 10 000 pizzas per month at a total cost of $500.If she produced one more pizza her total cost rises to $500.11.What does this tell us about Jill's marginal cost of producing pizzas?
(Multiple Choice)
4.8/5 (86)
(86) What is minimum efficient scale? What is likely to happen in the long run to firms that do not reach minimum efficient scale?
__________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
5.0/5 (74)
(74) As the level of output increases, what happens to the value of average fixed cost, and what happens to the difference between the value of average total cost and average variable cost?
__________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
4.9/5 (84)
(84) Figure 7.11  Figure 7.11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 7.11.If the firm chooses to produce and sell 25 000 frames per month by operating in the short run with a scale operation represented by ATCc
Figure 7.11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 7.11.If the firm chooses to produce and sell 25 000 frames per month by operating in the short run with a scale operation represented by ATCc (Multiple Choice)
4.7/5 (99)
(99) Figure 7.11 Figure 7.11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 7.11.Constant returns to scale
Figure 7.11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 7.11.Constant returns to scale (Multiple Choice)
4.9/5 (73)
(73) The change in a firm's total cost from producing one more unit of a good or service is
(Multiple Choice)
4.9/5 (74)
(74) If diminishing marginal returns have already set in for Golden Lark Woodworks, and the marginal product of the 6th carpenter is 8 chairs, what is the marginal product of the 7th carpenter?
(Multiple Choice)
4.9/5 (57)
(57) Minimum efficient scale is defined as the level of output at which
(Multiple Choice)
4.8/5 (90)
(90) If average total cost is falling, marginal cost must also be falling.
(True/False)
4.8/5 (79)
(79) Figure 7.11 Figure 7.11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 7.11.In the short run, if the firm sells fewer than 5000 picture frames per month,
Figure 7.11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 7.11.In the short run, if the firm sells fewer than 5000 picture frames per month, (Multiple Choice)
4.9/5 (73)
(73) If a firm decreases its plant size and finds that its long-run average costs have decreased, then
(Multiple Choice)
4.9/5 (77)
(77) Figure 7.11 Figure 7.11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 7.11.At what rate of output is the minimum efficient scale of output reached?
Figure 7.11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 7.11.At what rate of output is the minimum efficient scale of output reached? (Multiple Choice)
4.9/5 (74)
(74) Table 7.6 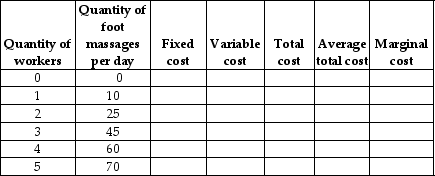 -Refer to Table 7.6.Alicia Gregory owns a foot massage business.She leases 4 computer-controlled massage booths, for which she pays $125 per day.She cannot increase the number machines she leases without giving the manufacturer 3 months notice.She can hire as many workers as she wants at a cost of $75 per day per worker.These are the only two inputs she uses in her business.Use this information to fill in the columns in the above table.
 (Essay)
4.8/5 (78)
(78) In the short run, marginal product of labour increases at first and then falls because
(Multiple Choice)
4.7/5 (84)
(84) Figure 7.13  -Refer to Figure 7.13.The lines shown in the diagram are isocost lines.A movement from CE to BD occurs when
 (Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)