



 Chat with AI
Exam 7: Technology Production and Costs

Exam 1: Economics: Foundations and Models159 Questions
Exam 2: Choices and Trade-Offs in the Market192 Questions
Exam 3: Where Prices Come From: The Interaction of Demand and Supply202 Questions
Exam 4: Elasticity: The Responsiveness of Demand and Supply224 Questions
Exam 5: Economic Efficiency, Government Price Setting and Taxes187 Questions
Exam 6: Consumer Choice and Behavioural Economics254 Questions
Exam 7: Technology Production and Costs301 Questions
Exam 8: Firms in Perfectly Competitive Markets269 Questions
Exam 9: Monopoly Markets281 Questions
Exam 10: Monopolistic Competition: The Competitive Model in a More Realistic255 Questions
Exam 11: Oligopoly: Markets With Few Competitors186 Questions
Exam 12: The Markets for Labour and Other Factors of Production250 Questions
Exam 13: Comparative Advantage and the Gains From International Trade131 Questions
Exam 14: Government Intervention in the Market113 Questions
Exam 15: Externalities, Environmental Policy and Public Goods212 Questions
Exam 16: The Distribution of Income and Social Policy121 Questions
Select questions type


If, when a firm doubles all its inputs, its average cost of production decreases, then production displays
(Multiple Choice)
4.8/5  (77)
(77) Figure 7.9 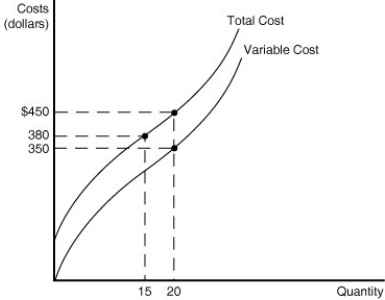 -Refer to Figure 7.9 above to solve the following problems.
a.Calculate the fixed cost of production.
b.Calculate the average total cost of production when the firm produces 20 units of output.
c.Calculate the average variable cost of production when the firm produces 20 units of output.
d.Calculate the average fixed cost of production when the firm produces 20 units of output.
e.Calculate the average fixed cost of production when the firm produces 15 units of output.
f.If the firm increases output from 15 to 20 units what is the marginal cost of output?
__________________________________________________________________________________________________________________________________________________________________________________________
-Refer to Figure 7.9 above to solve the following problems.
a.Calculate the fixed cost of production.
b.Calculate the average total cost of production when the firm produces 20 units of output.
c.Calculate the average variable cost of production when the firm produces 20 units of output.
d.Calculate the average fixed cost of production when the firm produces 20 units of output.
e.Calculate the average fixed cost of production when the firm produces 15 units of output.
f.If the firm increases output from 15 to 20 units what is the marginal cost of output?
__________________________________________________________________________________________________________________________________________________________________________________________ (Essay)
4.9/5 (79)
(79) Stan owns a software design business.He does not have time to expand his office space or redesign the layout of his office.He can increase the amount of work he does by working more hours, asking his current employees to work more hours, or hiring more employees.The relationship between Stan's inputs and the maximum output his firm can produce is called his
(Multiple Choice)
4.9/5 (98)
(98) The marginal rate of technical substitution is measured by
(Multiple Choice)
4.7/5 (88)
(88) Figure 7.14  -Refer to Figure 7.14.What is the combination of inputs that produces 200 gooseberry pies at the lowest cost?
 (Multiple Choice)
4.8/5 (72)
(72) The slope of an isocost line ________ and equals the negative of ________.
(Multiple Choice)
4.9/5 (74)
(74) The total cost schedule shows the relationship between different amounts of inputs and the resulting level of output.
(True/False)
4.8/5 (78)
(78) Which of the following are implicit costs for a typical firm?
(Multiple Choice)
4.8/5 (86)
(86) When a firm produces more output using the same inputs or the same output using fewer inputs we say that the firm
(Multiple Choice)
4.9/5 (99)
(99) Figure 7.6  Figure 7.6 contains information about the short-run cost structure of a firm.
-Refer to Figure 7.6.In the figure above, which letter represents the marginal cost curve?
Figure 7.6 contains information about the short-run cost structure of a firm.
-Refer to Figure 7.6.In the figure above, which letter represents the marginal cost curve? (Multiple Choice)
4.9/5 (70)
(70) State the law of diminishing marginal returns.
__________________________________________________________________________________________________________________________________________________________________________________________
(Essay)
4.9/5 (80)
(80) Figure 7.1  -Refer to Figure 7.1.What is the average product of the 4th worker?
 (Multiple Choice)
4.7/5 (85)
(85) Minimum efficient scale is defined as the level of output at which the short-run average total cost stops decreasing.
(True/False)
4.8/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)