



 Chat with AI
Exam 24: Portfolio Performance Evaluation

Exam 1: The Investment Environment58 Questions
Exam 2: Asset Classes and Financial Instruments86 Questions
Exam 3: How Securities Are Traded69 Questions
Exam 4: Mutual Funds and Other Investment Companies72 Questions
Exam 5: Risk, Return, and the Historical Record85 Questions
Exam 6: Capital Allocation to Risky Assets70 Questions
Exam 7: Optimal Risky Portfolios80 Questions
Exam 8: Index Models87 Questions
Exam 9: The Capital Asset Pricing Model83 Questions
Exam 10: Arbitrage Pricing Theory and Multifactor Models of Risk and Return80 Questions
Exam 11: The Efficient Market Hypothesis71 Questions
Exam 12: Behavioral Finance and Technical Analysis54 Questions
Exam 13: Empirical Evidence on Security Returns56 Questions
Exam 14: Bond Prices and Yields129 Questions
Exam 15: The Term Structure of Interest Rates49 Questions
Exam 16: Managing Bond Portfolios84 Questions
Exam 17: Macroeconomic and Industry Analysis90 Questions
Exam 18: Equity Valuation Models130 Questions
Exam 19: Financial Statement Analysis91 Questions
Exam 20: Options Markets: Introduction108 Questions
Exam 21: Option Valuation90 Questions
Exam 22: Futures Markets91 Questions
Exam 23: Futures, Swaps, and Risk Management56 Questions
Exam 24: Portfolio Performance Evaluation83 Questions
Exam 25: International Diversification52 Questions
Exam 26: Hedge Funds49 Questions
Exam 27: The Theory of Active Portfolio Management50 Questions
Exam 28: Investment Policy and the Framework of the Cfa Institute83 Questions
Select questions type


You want to evaluate three mutual funds using the Sharpe measure for performance evaluation.The risk-free return during the sample period is 5%.The average returns, standard deviations, and betas for the three funds are given below, as are the data for the S&P 500 Index. 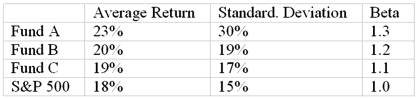 The investment with the highest Sharpe measure is
 (Multiple Choice)
4.8/5  (85)
(85) Suppose the risk-free return is 4%.The beta of a managed portfolio is 1.2, the alpha is 1%, and the average return is 14%.Based on Jensen's measure of portfolio performance, you would calculate the return on the market portfolio as
(Multiple Choice)
4.8/5 (79)
(79) You invested $1,000 through your broker three years ago.Your account balance at the beginning of each period is shown in the table below.
(Essay)
4.8/5 (67)
(67) Suppose two portfolios have the same average return, the same standard deviation of returns, but Aggie Fund has a higher beta than Raider Fund.According to the Sharpe measure, the performance of Aggie Fund
(Multiple Choice)
4.9/5 (85)
(85) Morningstar's RAR method I) is one of the most widely used performance measures.
II. indicates poor performance by placing up to 5 darts next to the fund's name.
III. computes fund returns adjusted for loads.
IV. computes fund returns adjusted for risk.
V. produces ranking results that are the same as those produced with the Sharpe measure.
(Multiple Choice)
4.8/5 (89)
(89) You want to evaluate three mutual funds using the Treynor measure for performance evaluation.The risk-free return during the sample period is 6%.The average returns, standard deviations, and betas for the three funds are given below, in addition to information regarding the S&P 500 Index. 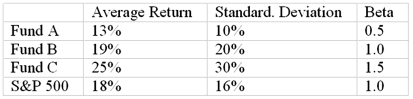 The fund with the highest Treynor measure is
 (Multiple Choice)
4.9/5 (74)
(74) The following data are available relating to the performance of Sooner Stock Fund and the market portfolio: 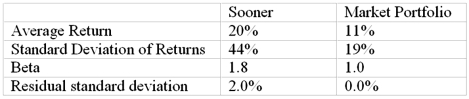 The risk-free return during the sample period was 3%. What is the Treynor measure of performance evaluation for Sooner Stock Fund
 (Multiple Choice)
4.8/5 (87)
(87) Suppose you own two stocks, A and B.In year 1, stock A earns a 2% return and stock B earns a 9% return.In year 2, stock A earns an 18% return and stock B earns an 11% return.Which stock has the higher geometric average return?
(Multiple Choice)
4.8/5 (85)
(85) Suppose two portfolios have the same average return, the same standard deviation of returns, but Buckeye Fund has a higher beta than Gator Fund.According to the Sharpe measure, the performance of Buckeye Fund
(Multiple Choice)
4.7/5 (78)
(78) The following data are available relating to the performance of Wildcat Fund and the market portfolio: 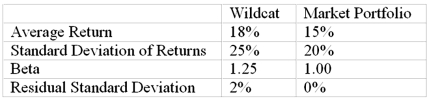 The risk-free return during the sample period was 7%. Calculate Treynor's measure of performance for Wildcat Fund.
 (Multiple Choice)
4.9/5 (84)
(84) In a particular year, Aggie Mutual Fund earned a return of 15% by making the following investments in the following asset classes: 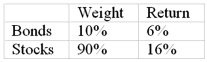 The return on a bogey portfolio was 10%, calculated as follows:
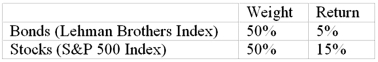 The contribution of asset allocation across markets to the total excess return was
The return on a bogey portfolio was 10%, calculated as follows: The contribution of asset allocation across markets to the total excess return was (Multiple Choice)
4.8/5 (82)
(82) In a particular year, Razorback Mutual Fund earned a return of 1% by making the following investments in asset classes: 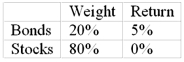 The return on a bogey portfolio was 2%, calculated from the following information.
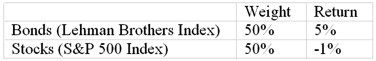 The contribution of asset allocation across markets to the Razorback Fund's total excess return was
The return on a bogey portfolio was 2%, calculated from the following information. The contribution of asset allocation across markets to the Razorback Fund's total excess return was (Multiple Choice)
4.9/5 (84)
(84) A pension fund that begins with $500,000 earns 15% the first year and 10% the second year.At the beginning of the second year, the sponsor contributes another $300,000.The dollar-weighted and time-weighted rates of return, respectively, were
(Multiple Choice)
4.8/5 (75)
(75) The following data are available relating to the performance of Seminole Fund and the market portfolio: 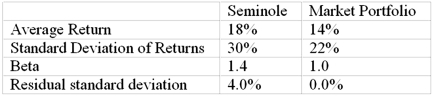 The risk-free return during the sample period was 6%. If you wanted to evaluate the Seminole Fund using the M2 measure, what percent of the adjusted portfolio would need to be invested in T-Bills
 (Multiple Choice)
5.0/5 (83)
(83) Mutual funds show ____________ evidence of serial correlation and hedge funds show ____________ evidence of serial correlation.
(Multiple Choice)
4.8/5 (77)
(77) You want to evaluate three mutual funds using the information ratio measure for performance evaluation.The risk-free return during the sample period is 6%, and the average return on the market portfolio is 19%.The average returns, residual standard deviations, and betas for the three funds are given below. 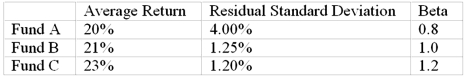 The fund with the highest information ratio measure is
 (Multiple Choice)
4.9/5 (80)
(80) Suppose two portfolios have the same average return, the same standard deviation of returns, but Aggie Fund has a lower beta than Raider Fund.According to the Treynor measure, the performance of Aggie Fund
(Multiple Choice)
4.9/5 (74)
(74) The following data are available relating to the performance of Sooner Stock Fund and the market portfolio: 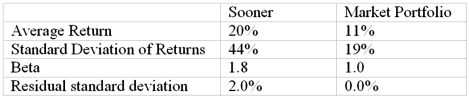 The risk-free return during the sample period was 3%. What is the Sharpe measure of performance evaluation for Sooner Stock Fund
 (Multiple Choice)
5.0/5 (89)
(89) Suppose you purchase 100 shares of GM stock at the beginning of year 1 and purchase another 100 shares at the end of year 1.You sell all 200 shares at the end of year 2.Assume that the price of GM stock is $50 at the beginning of year 1, $55 at the end of year 1, and $65 at the end of year 2.Assume no dividends were paid on GM stock.Your dollar-weighted return on the stock will be __________ your time-weighted return on the stock.
(Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)