



 Chat with AI
Exam 24: Portfolio Performance Evaluation


The following data are available relating to the performance of Wildcat Fund and the market portfolio: 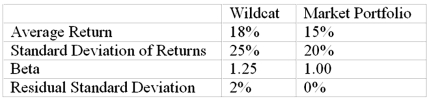 The risk-free return during the sample period was 7%. Calculate Sharpe's measure of performance for Wildcat Fund.
 (84)
 Verified
C
Suppose you purchase one share of the stock of Cereal Correlation Company at the beginning of year 1 for $50.At the end of year 1, you receive a $1 dividend and buy one more share for $72.At the end of year 2, you receive total dividends of $2 (i.e., $1 for each share) and sell the shares for $67.20 each.The dollar-weighted return on your investment is
(84) VerifiedB
Discuss the M2 measure of performance by answering the following questions.Why is M2 better than the Sharpe measure
What measure of risk does M2 use
How do you construct a managed portfolio, P, to use in computing the M2 measure
What is the formula for M2
Draw a graph that shows how M2 would be measured.Be sure to label the axes and all relevant points.
(72) VerifiedThe Sharpe measure indicates whether a portfolio underperformed the market index, but the difference between the market's Sharpe measure and the portfolio's Sharpe measure is difficult to interpret.M2 uses the same measure of risk as the Sharpe measure-variation in total return, calculated as the standard deviation.For managed portfolio P an adjusted portfolio P* is formed by combining P with borrowing or lending at the risk-free rate to the point where P* has the same volatility as a market index (M).Then since M and P have the same standard deviation they can be directly compared using the M2 measure.M2 = rP* - rM.If P* outperforms M the measure will be positive, which means the CAL on which P* lies will have a steeper slope than the CML on which M lies.M2 is the distance between the CAL and the CML.
The graph should look like the one in Figure 24.2.
Feedback: This question tests whether the student understands the characteristics and the construction of the M2 measure.
__________ did not develop a popular method for risk-adjusted performance evaluation of mutual funds.
(86) The following data are available relating to the performance of Long Horn Stock Fund and the market portfolio: 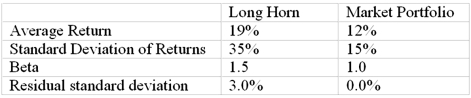 The risk-free return during the sample period was 6%. Calculate the information ratio for Long Horn Stock Fund.
 (84) The Sharpe, Treynor, and Jensen portfolio performance measures are derived from the CAPM,
(78) The following data are available relating to the performance of Seminole Fund and the market portfolio: 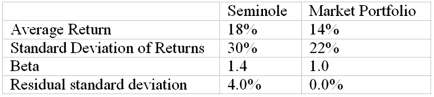 The risk-free return during the sample period was 6%. Calculate the M2 measure for the Seminole Fund.
 (86) You want to evaluate three mutual funds using the Sharpe measure for performance evaluation.The risk-free return during the sample period is 4%.The average returns, standard deviations, and betas for the three funds are given below, as are the data for the S&P 500 Index. 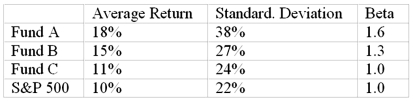 The fund with the highest Sharpe measure is
 (84) What is the problem with using the Sharpe measure for evaluation of an active portfolio management strategy
(98) In a particular year, Aggie Mutual Fund earned a return of 15% by making the following investments in the following asset classes: 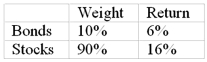 The return on a bogey portfolio was 10%, calculated as follows:
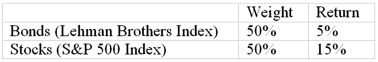 The contribution of selection within markets to total excess return was
The return on a bogey portfolio was 10%, calculated as follows: The contribution of selection within markets to total excess return was (87) The following data are available relating to the performance of Monarch Stock Fund and the market portfolio: 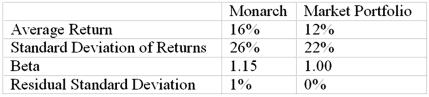 The risk-free return during the sample period was 4%. What is the information ratio measure of performance evaluation for Monarch Stock Fund
 (63) Suppose you purchase one share of the stock of Cereal Correlation Company at the beginning of year 1 for $50.At the end of year 1, you receive a $1 dividend and buy one more share for $72.At the end of year 2, you receive total dividends of $2 (i.e., $1 for each share) and sell the shares for $67.20 each.The time-weighted return on your investment is
(87) Suppose you own two stocks, A and B.In year 1, stock A earns a 2% return and stock B earns a 9% return.In year 2, stock A earns an 18% return and stock B earns an 11% return.__________ has the higher arithmetic average return.
(74) A portfolio manager's ranking within a comparison universe may not provide a good measure of performance because
(59) Suppose you purchase one share of the stock of Volatile Engineering Corporation at the beginning of year 1 for $36.At the end of year 1, you receive a $2 dividend and buy one more share for $30.At the end of year 2, you receive total dividends of $4 (i.e., $2 for each share) and sell the shares for $36.45 each.The time-weighted return on your investment is
(84) Suppose two portfolios have the same average return, the same standard deviation of returns, but Buckeye Fund has a higher beta than Gator Fund.According to the Treynor measure, the performance of Buckeye Fund
(71) The following data are available relating to the performance of Sooner Stock Fund and the market portfolio: 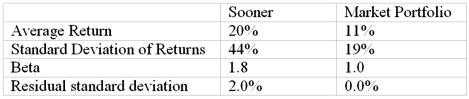 The risk-free return during the sample period was 3%. Calculate the information ratio for Sooner Stock Fund.
 (73) Suppose two portfolios have the same average return, the same standard deviation of returns, but Buckeye Fund has a lower beta than Gator Fund.According to the Treynor measure, the performance of Buckeye Fund
(75) Suppose a particular investment earns an arithmetic return of 10% in year 1, 20% in year 2 and 30% in year 3.The geometric average return for the year period will be
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)