



 Chat with AI
Exam 23: Futures, Swaps, and Risk Management

Exam 1: The Investment Environment58 Questions
Exam 2: Asset Classes and Financial Instruments86 Questions
Exam 3: How Securities Are Traded69 Questions
Exam 4: Mutual Funds and Other Investment Companies72 Questions
Exam 5: Risk, Return, and the Historical Record85 Questions
Exam 6: Capital Allocation to Risky Assets70 Questions
Exam 7: Optimal Risky Portfolios80 Questions
Exam 8: Index Models87 Questions
Exam 9: The Capital Asset Pricing Model83 Questions
Exam 10: Arbitrage Pricing Theory and Multifactor Models of Risk and Return80 Questions
Exam 11: The Efficient Market Hypothesis71 Questions
Exam 12: Behavioral Finance and Technical Analysis54 Questions
Exam 13: Empirical Evidence on Security Returns56 Questions
Exam 14: Bond Prices and Yields129 Questions
Exam 15: The Term Structure of Interest Rates49 Questions
Exam 16: Managing Bond Portfolios84 Questions
Exam 17: Macroeconomic and Industry Analysis90 Questions
Exam 18: Equity Valuation Models130 Questions
Exam 19: Financial Statement Analysis91 Questions
Exam 20: Options Markets: Introduction108 Questions
Exam 21: Option Valuation90 Questions
Exam 22: Futures Markets91 Questions
Exam 23: Futures, Swaps, and Risk Management56 Questions
Exam 24: Portfolio Performance Evaluation83 Questions
Exam 25: International Diversification52 Questions
Exam 26: Hedge Funds49 Questions
Exam 27: The Theory of Active Portfolio Management50 Questions
Exam 28: Investment Policy and the Framework of the Cfa Institute83 Questions
Select questions type


Suppose that the risk-free rates in the United States and in the Canada are 3% and 5%, respectively.The spot exchange rate between the dollar and the Canadian dollar (C$) is $0.80/C$.What should the futures price of the C$ for a one-year contract be to prevent arbitrage opportunities, ignoring transactions costs.

Free
(Multiple Choice)
4.8/5  (76)
(76) Correct Answer: Verified
D
Explain how a firm that has issued $1 million of long-term bonds with a fixed 6% interest rate can convert its fixed-rate debt into floating-rate debt.Give two numerical examples that show the possible outcomes, one favorable and one unfavorable.
Free
(Essay)
4.9/5 (75)
(75) Correct Answer:Verified
VerifiedThe firm can enter a swap arrangement, committing to pay .06 × $1 million = $60,000 in exchange for receiving payments equal to $1 million times the LIBOR rate.If the LIBOR rate is 5, the cash inflow would be $1 million × .05 = $50,000.The net cash flow would be -$10,000 in this case, which is unfavorable.If the LIBOR rate is 8%, the firm will have a cash inflow of $1 million × .08 = $80,000.The net cash flow in this case is $20,000, which is favorable.
Feedback: This is a basic question about the mechanics of a swap agreement.
Suppose that the risk-free rates in the United States and in the Canada are 5% and 3%, respectively.The spot exchange rate between the dollar and the Canadian dollar (C$) is $0.80/C$.What should the futures price of the C$ for a one-year contract be to prevent arbitrage opportunities, ignoring transactions costs.
Free
(Multiple Choice)
5.0/5 (77)
(77) Correct Answer:Verified
VerifiedB
Suppose that the risk-free rates in the United States and in Japan are 5.25% and 4.5%, respectively.The spot exchange rate between the dollar and the yen is $0.008828/yen.What should the futures price of the yen for a one-year contract be to prevent arbitrage opportunities, ignoring transactions costs
(Multiple Choice)
4.9/5 (72)
(72) You are given the following information about a portfolio you are to manage.For the long-term you are bullish, but you think the market may fall over the next month. 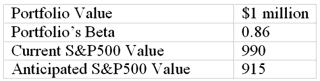 How many contracts should you buy or sell to hedge your position Allow fractions of contracts in your answer.
 (Multiple Choice)
4.9/5 (82)
(82) The most common short term interest rate used in the swap market is
(Multiple Choice)
4.9/5 (76)
(76) Which one of the following stock index futures has a multiplier of 10 euros times the index
(Multiple Choice)
4.8/5 (84)
(84) Foreign exchange futures markets are __________ and the foreign exchange forward markets are __________.
(Multiple Choice)
4.8/5 (84)
(84) You are given the following information about a portfolio you are to manage.For the long-term you are bullish, but you think the market may fall over the next month. 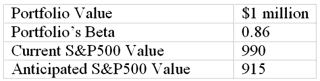 If the anticipated market value materializes, what will be your expected loss on the portfolio
 (Multiple Choice)
4.9/5 (87)
(87) Which one of the following stock index futures has a multiplier of $250 times the index value
(Multiple Choice)
5.0/5 (86)
(86) If you took a short position in three S&P 500 futures contracts at a price of 900 and closed the position when the index futures was 885, you incurred:
(Multiple Choice)
4.7/5 (82)
(82) You are given the following information about a portfolio you are to manage.For the long-term you are bullish, but you think the market may fall over the next month. 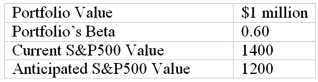 What is the dollar value of your expected loss
 (Multiple Choice)
4.9/5 (68)
(68) Which one of the following stock index futures has a multiplier of $10 times the index value
(Multiple Choice)
5.0/5 (75)
(75) Suppose that the risk-free rates in the United States and in the United Kingdom are 6% and 4%, respectively.The spot exchange rate between the dollar and the pound is $1.60/BP.What should the futures price of the pound for a one-year contract be to prevent arbitrage opportunities, ignoring transactions costs.
(Multiple Choice)
4.8/5 (83)
(83) Which one of the following stock index futures has a multiplier of 50 Hong Kong dollars times the index
(Multiple Choice)
4.9/5 (74)
(74) You are given the following information about a portfolio you are to manage.For the long-term you are bullish, but you think the market may fall over the next month. 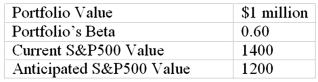 If the anticipated market value materializes, what will be your expected loss on the portfolio
 (Multiple Choice)
4.7/5 (89)
(89) If you purchased one S&P 500 Index futures contract at a price of 1,550 and closed your position when the index futures was 1,547, you incurred:
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)