



 Chat with AI
Exam 24: Portfolio Performance Evaluation

Exam 1: The Investment Environment58 Questions
Exam 2: Asset Classes and Financial Instruments86 Questions
Exam 3: How Securities Are Traded69 Questions
Exam 4: Mutual Funds and Other Investment Companies72 Questions
Exam 5: Risk, Return, and the Historical Record85 Questions
Exam 6: Capital Allocation to Risky Assets70 Questions
Exam 7: Optimal Risky Portfolios80 Questions
Exam 8: Index Models87 Questions
Exam 9: The Capital Asset Pricing Model83 Questions
Exam 10: Arbitrage Pricing Theory and Multifactor Models of Risk and Return80 Questions
Exam 11: The Efficient Market Hypothesis71 Questions
Exam 12: Behavioral Finance and Technical Analysis54 Questions
Exam 13: Empirical Evidence on Security Returns56 Questions
Exam 14: Bond Prices and Yields129 Questions
Exam 15: The Term Structure of Interest Rates49 Questions
Exam 16: Managing Bond Portfolios84 Questions
Exam 17: Macroeconomic and Industry Analysis90 Questions
Exam 18: Equity Valuation Models130 Questions
Exam 19: Financial Statement Analysis91 Questions
Exam 20: Options Markets: Introduction108 Questions
Exam 21: Option Valuation90 Questions
Exam 22: Futures Markets91 Questions
Exam 23: Futures, Swaps, and Risk Management56 Questions
Exam 24: Portfolio Performance Evaluation83 Questions
Exam 25: International Diversification52 Questions
Exam 26: Hedge Funds49 Questions
Exam 27: The Theory of Active Portfolio Management50 Questions
Exam 28: Investment Policy and the Framework of the Cfa Institute83 Questions
Select questions type


__________ developed a popular method for risk-adjusted performance evaluation of mutual funds.
(Multiple Choice)
4.8/5  (77)
(77) The following data are available relating to the performance of Monarch Stock Fund and the market portfolio: 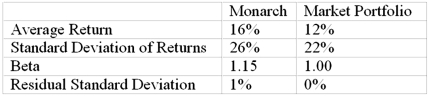 The risk-free return during the sample period was 4%. Calculate Treynor's measure of performance for Monarch Stock Fund.
 (Multiple Choice)
4.7/5 (69)
(69) Risk-adjusted mutual fund performance measures have decreased in popularity because
(Multiple Choice)
4.7/5 (91)
(91) The following data are available relating to the performance of Wildcat Fund and the market portfolio: 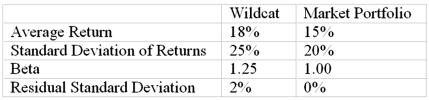 The risk-free return during the sample period was 7%. Calculate Jensen's measure of performance for Wildcat Fund.
 (Multiple Choice)
4.8/5 (81)
(81) The following data are available relating to the performance of Sooner Stock Fund and the market portfolio: 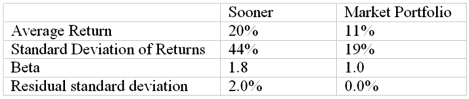 The risk-free return during the sample period was 3%. Calculate the Jensen measure of performance evaluation for Sooner Stock Fund.
 (Multiple Choice)
4.9/5 (84)
(84) In a particular year, Aggie Mutual Fund earned a return of 15% by making the following investments in the following asset classes: 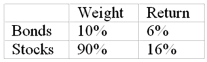 The return on a bogey portfolio was 10%, calculated as follows:
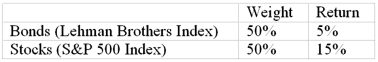 The total excess return on the Aggie managed portfolio was
The return on a bogey portfolio was 10%, calculated as follows: The total excess return on the Aggie managed portfolio was (Multiple Choice)
4.8/5 (88)
(88) To determine whether portfolio performance is statistically significant requires
(Multiple Choice)
4.8/5 (75)
(75) The following data are available relating to the performance of Long Horn Stock Fund and the market portfolio: 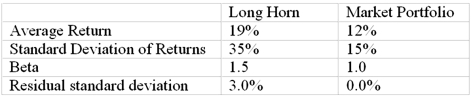 The risk-free return during the sample period was 6%. What is the Sharpe measure of performance evaluation for Long Horn Stock Fund
 (Multiple Choice)
4.7/5 (97)
(97) The following data are available relating to the performance of Monarch Stock Fund and the market portfolio: 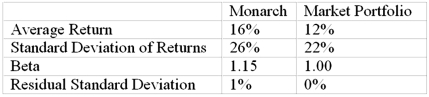 The risk-free return during the sample period was 4%. Calculate Jensen's measure of performance for Monarch Stock Fund.
 (Multiple Choice)
4.9/5 (81)
(81) Suppose the risk-free return is 6%.The beta of a managed portfolio is 1.5, the alpha is 3%, and the average return is 18%.Based on Jensen's measure of portfolio performance, you would calculate the return on the market portfolio as
(Multiple Choice)
4.8/5 (77)
(77) Studies of style analysis have found that ________ of fund returns can be explained by asset allocation alone.
(Multiple Choice)
4.8/5 (87)
(87) Suppose two portfolios have the same average return, the same standard deviation of returns, but Aggie Fund has a higher beta than Raider Fund.According to the Treynor measure, the performance of Aggie Fund
(Multiple Choice)
4.9/5 (86)
(86) Define and discuss the Sharpe, Treynor, and Jensen measures of portfolio performance evaluation and the situations in which each measure is the most appropriate measure.
(Essay)
4.8/5 (81)
(81) You want to evaluate three mutual funds using the Sharpe measure for performance evaluation.The risk-free return during the sample period is 6%.The average returns, standard deviations, and betas for the three funds are given below, as are the data for the S&P 500 Index. 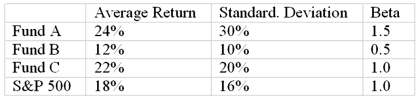 The fund with the highest Sharpe measure is
 (Multiple Choice)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)