Multiple Choice
You want to evaluate three mutual funds using the Sharpe measure for performance evaluation.The risk-free return during the sample period is 5%.The average returns, standard deviations, and betas for the three funds are given below, as are the data for the S&P 500 Index. 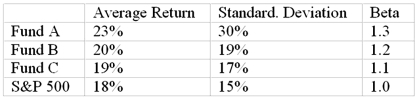 The investment with the highest Sharpe measure is
A) Fund A.
B) Fund B.
C) Fund C.
D) Funds A and B (tied for highest) .
E) Funds A and C (tied for highest) .
Correct Answer:

Verified
Correct Answer:
Verified
Q27: Suppose the risk-free return is 4%. The
Q28: Morningstar's RAR methodI) is one of the
Q32: The geometric average rate of return is
Q57: The dollar-weighted return on a portfolio is
Q58: The M-squared measure considers<br>A)only the return when
Q59: You want to evaluate three mutual funds
Q60: Discuss, in general, the performance attribution procedures.
Q62: The comparison universe is<br>A)a concept found only
Q64: You invested $1,000 through your broker three
Q65: Suppose two portfolios have the same average