



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models240 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance261 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets297 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets257 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


If the market price is $25, the average revenue of selling five units is
(Multiple Choice)
4.8/5  (73)
(73) Letters are used to represent the terms used to answer this question: price (P), quantity of output (Q), total cost (TC)and average total cost (ATC).Which of the following equations is equal to a firm's average profit?
(Multiple Choice)
4.9/5 (77)
(77) The supply curve of a perfectly competitive firm in the short run is
(Multiple Choice)
4.8/5 (79)
(79) Assume that a perfectly competitive market is in long-run equilibrium.Suppose as a result of a health hazard associated with the industry's product, demand decreases drastically.What is the immediate result of this event?
(Multiple Choice)
5.0/5 (86)
(86) If the market price is $25 in a perfectly competitive market, the marginal revenue from selling the fifth unit is
(Multiple Choice)
4.9/5 (83)
(83) Producing where marginal revenue equals marginal cost is equivalent to producing where
(Multiple Choice)
4.9/5 (77)
(77) Which of the following arguments could be made as evidence that the market for cage-free eggs is perfectly competitive?
(Multiple Choice)
4.9/5 (80)
(80) Werner & Sons is a manufacturer of three-ring binders operating in a perfectly competitive industry.Table 12-5 shows the firm's cost schedule.
Table 12-5
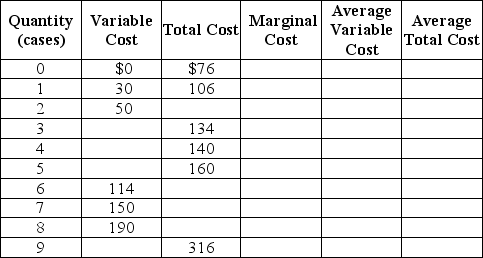 Use the table to answer the following questions.
a. Complete Table 12-5 by filling in the blank cells.
b. Werner is selling in a perfectly competitive market at a price of $40. What is the profit-maximizing or loss-minimizing output?
c. Calculate the firm's profit or loss.
d. Should the firm continue to produce in the short run? Explain.
e. If the firm's fixed costs were $30 higher what would be the profit-maximizing output level in the short run? Indicate whether the output level will increase, decrease, or remain unchanged compared to your answer in b.
f. Suppose fixed cost remains at $76. If the price of three-ring binders falls to $20 what is the profit-maximizing or loss-minimizing output?
g. Calculate the profit or loss. Should the firm continue to produce in the short run? Explain your answer.
h. Suppose the fixed cost remains at $76. What price corresponds to the shut-down point?
i. Suppose the fixed cost remains at $76. What price corresponds to the break-even point?
Use the table to answer the following questions.
a. Complete Table 12-5 by filling in the blank cells.
b. Werner is selling in a perfectly competitive market at a price of $40. What is the profit-maximizing or loss-minimizing output?
c. Calculate the firm's profit or loss.
d. Should the firm continue to produce in the short run? Explain.
e. If the firm's fixed costs were $30 higher what would be the profit-maximizing output level in the short run? Indicate whether the output level will increase, decrease, or remain unchanged compared to your answer in b.
f. Suppose fixed cost remains at $76. If the price of three-ring binders falls to $20 what is the profit-maximizing or loss-minimizing output?
g. Calculate the profit or loss. Should the firm continue to produce in the short run? Explain your answer.
h. Suppose the fixed cost remains at $76. What price corresponds to the shut-down point?
i. Suppose the fixed cost remains at $76. What price corresponds to the break-even point? (Essay)
4.8/5 (77)
(77) If a perfectly competitive apple farm's marginal revenue exceeds the marginal cost of the last bushel of apples sold, what should the farm do to maximize its profit?
(Multiple Choice)
4.7/5 (87)
(87) Assume that the personal computer industry is perfectly competitive.The fact that the price of personal computers over the last decade has fallen despite increases in demand signifies that the industry is a decreasing-cost industry.
(True/False)
4.9/5 (76)
(76) Table 12-4
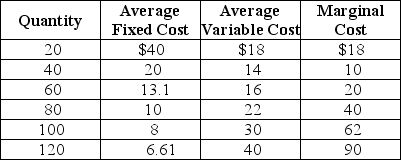 Table 12-4 shows the short-run cost data of a perfectly competitive firm. Assume that output can only be increased in batches of 20 units.
-Refer to Table 12-4.If the market price is $45 the firm will produce
Table 12-4 shows the short-run cost data of a perfectly competitive firm. Assume that output can only be increased in batches of 20 units.
-Refer to Table 12-4.If the market price is $45 the firm will produce (Multiple Choice)
4.8/5 (80)
(80) The market demand curve in a perfectly competitive market is downward sloping.
(True/False)
4.7/5 (80)
(80) Figure 12-1
 -Refer to Figure 12-1.If the firm is charging a price of $12 per unit,
 (Multiple Choice)
4.8/5 (86)
(86) Suppose the equilibrium price in a perfectly competitive industry is $15 and a firm in the industry charges $21.Which of the following will happen?
(Multiple Choice)
4.7/5 (74)
(74) A constant-cost, perfectly competitive market is in long-run equilibrium.At present, there are 1,000 firms each producing 400 units of output.The price of the good is $60.Now suppose there is a sudden increase in demand for the industry's product which causes the price of the good to rise to $64.In the new long-run equilibrium, how will the average total cost of producing the good compare to what it was before the price of the good rose?
(Multiple Choice)
4.9/5 (92)
(92) If a typical firm in a perfectly competitive industry is earning profits, then
(Multiple Choice)
4.8/5 (61)
(61) If a perfectly competitive firm's price is above its average total cost, the firm
(Multiple Choice)
4.9/5 (78)
(78) Figure 12-15
 -Refer to Figure 12-15.Suppose a typical firm in a perfectly competitive market is earning economic profits in the short run.Which of the diagrams in the figure depicts what happens in the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
5.0/5 (65)
(65) Apple introduced its iPhone 3G in July 2008 and within a month sales had topped 3 million units.By April 2009, more than 25,000 apps for the iPhone 3G were available in the iTunes store, an indication that in a competitive market,
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)