



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models240 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System258 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply242 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes208 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care171 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance261 Questions
Exam 9: Comparative Advantage and the Gains From International Trade188 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets297 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets257 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Select questions type


What is the relationship among the following variables for a perfectly competitive firm: the market price, average revenue and marginal revenue?
(Multiple Choice)
4.8/5  (63)
(63) If the market price is $40, the average revenue of selling five units is
(Multiple Choice)
4.9/5 (91)
(91) Figure 12-5
 Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the market price is $20, what is the amount of the firm's profit?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the market price is $20, what is the amount of the firm's profit? (Multiple Choice)
4.9/5 (82)
(82) Figure 12-12
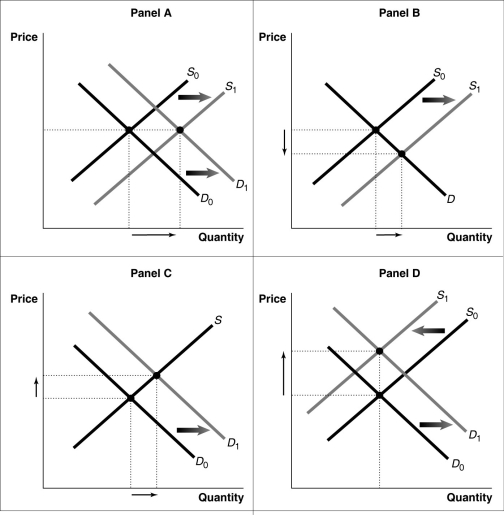 -Refer to Figure 12-12.Consider a typical firm in a perfectly competitive industry that makes short-run profits.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.9/5 (89)
(89) Assume that the market for cage-free eggs is perfectly competitive.All else equal, as more farmers choose to produce and sell cage-free eggs, what is likely to happen to the equilibrium price of the eggs and profits of these farmers in the long run?
(Multiple Choice)
4.7/5 (83)
(83) Figure 12-4
 Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30, the firm's profit-maximizing output level is
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30, the firm's profit-maximizing output level is (Multiple Choice)
4.8/5 (80)
(80) Figure 12-1
 -Refer to Figure 12-1.If the firm is producing 200 units,
 (Multiple Choice)
4.8/5 (74)
(74) In the long run, perfectly competitive firms earn zero economic profit.Why do firms enter an industry when they know that in the long-run they will not earn any profit?
(Essay)
4.8/5 (90)
(90) Figure 12-1
-Refer to Figure 12-1.If the firm is producing 500 units, what is the amount of its profit or loss?
-Refer to Figure 12-1.If the firm is producing 500 units, what is the amount of its profit or loss? (Multiple Choice)
4.7/5 (72)
(72) Perfect competition is characterized by all of the following except
(Multiple Choice)
4.7/5 (90)
(90) A perfectly competitive wheat farmer in a constant-cost industry produces 1,000 bushels of wheat at a total cost of $50,000.The prevailing market price is $48.What will happen to the market price of wheat in the long run?
(Multiple Choice)
5.0/5 (77)
(77) Table 12-3
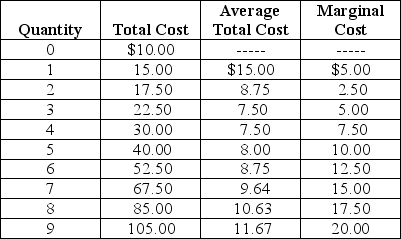 Arnie sells basketballs in a perfectly competitive market. Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC)and marginal cost (MC).
-Refer to Table 12-3.What will Arnie's output be and how much profit will he earn if the market price of basketballs is $5.00?
Arnie sells basketballs in a perfectly competitive market. Table 12-3 summarizes Arnie's output per day (Q), total cost (TC), average total cost (ATC)and marginal cost (MC).
-Refer to Table 12-3.What will Arnie's output be and how much profit will he earn if the market price of basketballs is $5.00? (Multiple Choice)
4.9/5 (59)
(59) Using two graphs, illustrate how a positive technological change in the market for notebook computers could eliminate short-run economic profit for a firm in that market.On the first graph, use a supply and demand graph to illustrate the positive technological change.On the second graph, use demand, ATC, MC, and MR curves to illustrate the elimination of economic profit resulting from the positive technological change.Explain what is taking place in each graph.
(Essay)
4.9/5 (98)
(98) Figure 12-16
 -Refer to Figure 12-16.Which panel best represents the perfectly competitive organic produce market in which some firms are earning short-run economic profits, and the Surgeon General announces that switching from non-organic produce to organic produce will add 5 years to the average life span of consumers?
 (Multiple Choice)
4.9/5 (97)
(97) The price a perfectly competitive firm receives for its output
(Multiple Choice)
4.9/5 (87)
(87) Figure 12-11
 -Refer to Figure 12-11.Suppose the prevailing price is $20 and the firm is currently producing 1,350 units.In the long-run equilibrium
 (Multiple Choice)
5.0/5 (92)
(92) Which of the following is not a characteristic of a perfectly competitive market structure?
(Multiple Choice)
4.8/5 (76)
(76) A very large number of small sellers who sell identical products imply
(Multiple Choice)
4.9/5 (85)
(85) Figure 12-1
-Refer to Figure 12-1.If the firm is producing 700 units, what is the amount of its profit or loss?
-Refer to Figure 12-1.If the firm is producing 700 units, what is the amount of its profit or loss? (Multiple Choice)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)