



 Chat with AI
Exam 9: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Market Efficiency and Market Failure465 Questions
Exam 5: The Economics of Health Care334 Questions
Exam 6: Firms, the Stock Market, and Corporate Governance250 Questions
Exam 7: Consumer Choice and Elasticity380 Questions
Exam 8: Technology, production, and Costs276 Questions
Exam 9: Firms in Perfectly Competitive Markets297 Questions
Exam 10: Monopoly and Antitrust Policy271 Questions
Exam 11: Monopolistic Competition and Oligopoly414 Questions
Exam 12: Gdp: Measuring Total Production and Income266 Questions
Exam 13: Unemployment and Inflation292 Questions
Exam 14: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 16: Money, banks, and the Federal Reserve System279 Questions
Exam 17: Monetary Policy277 Questions
Exam 18: Fiscal Policy282 Questions
Exam 19: Comparative Advantage, international Trade, and Exchange Rates446 Questions
Select questions type


Firms in perfectly competitive industries are unable to control the prices of the products they sell and earn a profit in the long run.Which of the following is one reason for this?
(Multiple Choice)
4.9/5  (86)
(86) Allocative efficiency is achieved in an industry when firms supply those goods and services that provide consumers with a marginal benefit equal to the marginal cost of producing those goods and services.
(True/False)
4.8/5 (82)
(82) Which of the following is a characteristic of a firm in a perfectly competitive market?
(Multiple Choice)
4.8/5 (83)
(83) Figure 9-10
 -Refer to Figure 9-10.Total revenue at the profit-maximizing level of output is
 (Multiple Choice)
4.9/5 (75)
(75) Figure 9-12
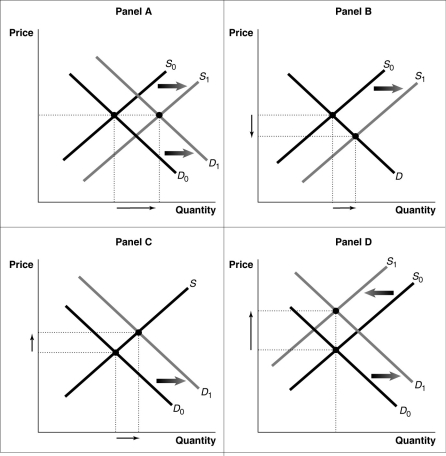 -Refer to Figure 9-12.Consider a typical firm in a perfectly competitive industry that makes short-run profits.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (85)
(85) Figure 9-4
 Figure 9-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 9-4.If the market price is $30,the firm's profit-maximizing output level is
Figure 9-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 9-4.If the market price is $30,the firm's profit-maximizing output level is (Multiple Choice)
4.9/5 (72)
(72) If the market price is $40 in a perfectly competitive market,the marginal revenue from selling the fifth unit is
(Multiple Choice)
4.9/5 (86)
(86) Which of the following is the best example of a perfectly competitive firm?
(Multiple Choice)
5.0/5 (91)
(91) Figure 9-2
 -Refer to Figure 9-2.Suppose the firm is currently producing Q₂ units.What happens if it expands output to Q₃ units?
 (Multiple Choice)
4.8/5 (75)
(75) Competition has driven the economic profits in the video rental business to zero.Surya Bacha,who owns a video rental business,would be better off leaving the industry for another alternative.
(True/False)
4.8/5 (74)
(74) A perfectly competitive wheat farmer in a constant-cost industry produces 3,000 bushels of wheat at a total cost of $36,000.The prevailing market price is $15.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.9/5 (71)
(71) For a perfectly competitive firm,average revenue is equal to
(Multiple Choice)
4.8/5 (68)
(68) Consider the market for wheat which is a perfectly competitive market.Is the market demand curve the same as the demand curve facing an individual producer? If not,explain how and why they are different? Illustrate your answer graphically.
(Essay)
4.8/5 (80)
(80) Assume that the personal computer industry is perfectly competitive.The fact that the price of personal computers over the last decade has fallen despite increases in demand signifies that the industry is a decreasing-cost industry.
(True/False)
4.9/5 (74)
(74) Figure 9-9
 Figure 9-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 9-9.At price P₄,the firm would
Figure 9-9 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 9-9.At price P₄,the firm would (Multiple Choice)
4.9/5 (75)
(75) Figure 9-5
 Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.If the market price is $20,what is the firm's profit-maximizing output?
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.If the market price is $20,what is the firm's profit-maximizing output? (Multiple Choice)
4.8/5 (80)
(80) If,as a perfectly competitive industry expands,it can supply larger quantities only at a higher long-run equilibrium price,it is
(Multiple Choice)
4.9/5 (71)
(71) Figure 9-5
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.What is the minimum price the firm requires to produce output?
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 9-5.What is the minimum price the firm requires to produce output? (Multiple Choice)
4.8/5 (84)
(84) Figure 9-1
 -Refer to Figure 9-1.If the firm is producing 700 units,
 (Multiple Choice)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)